

The NCERT PDF for Class 11 Accountancy Chapter 6 Trial Balance and Rectification of Errors explains how ledger balances are checked and how accounting mistakes are corrected, according to the 2026-27 NCERT textbook.
- Core focus: trial balance, suspense account, error types and rectification entries.
- Practice value: students learn why totals disagree and how to fix mistakes.
- PDF use: keep the chapter open while solving journal entry correction questions.
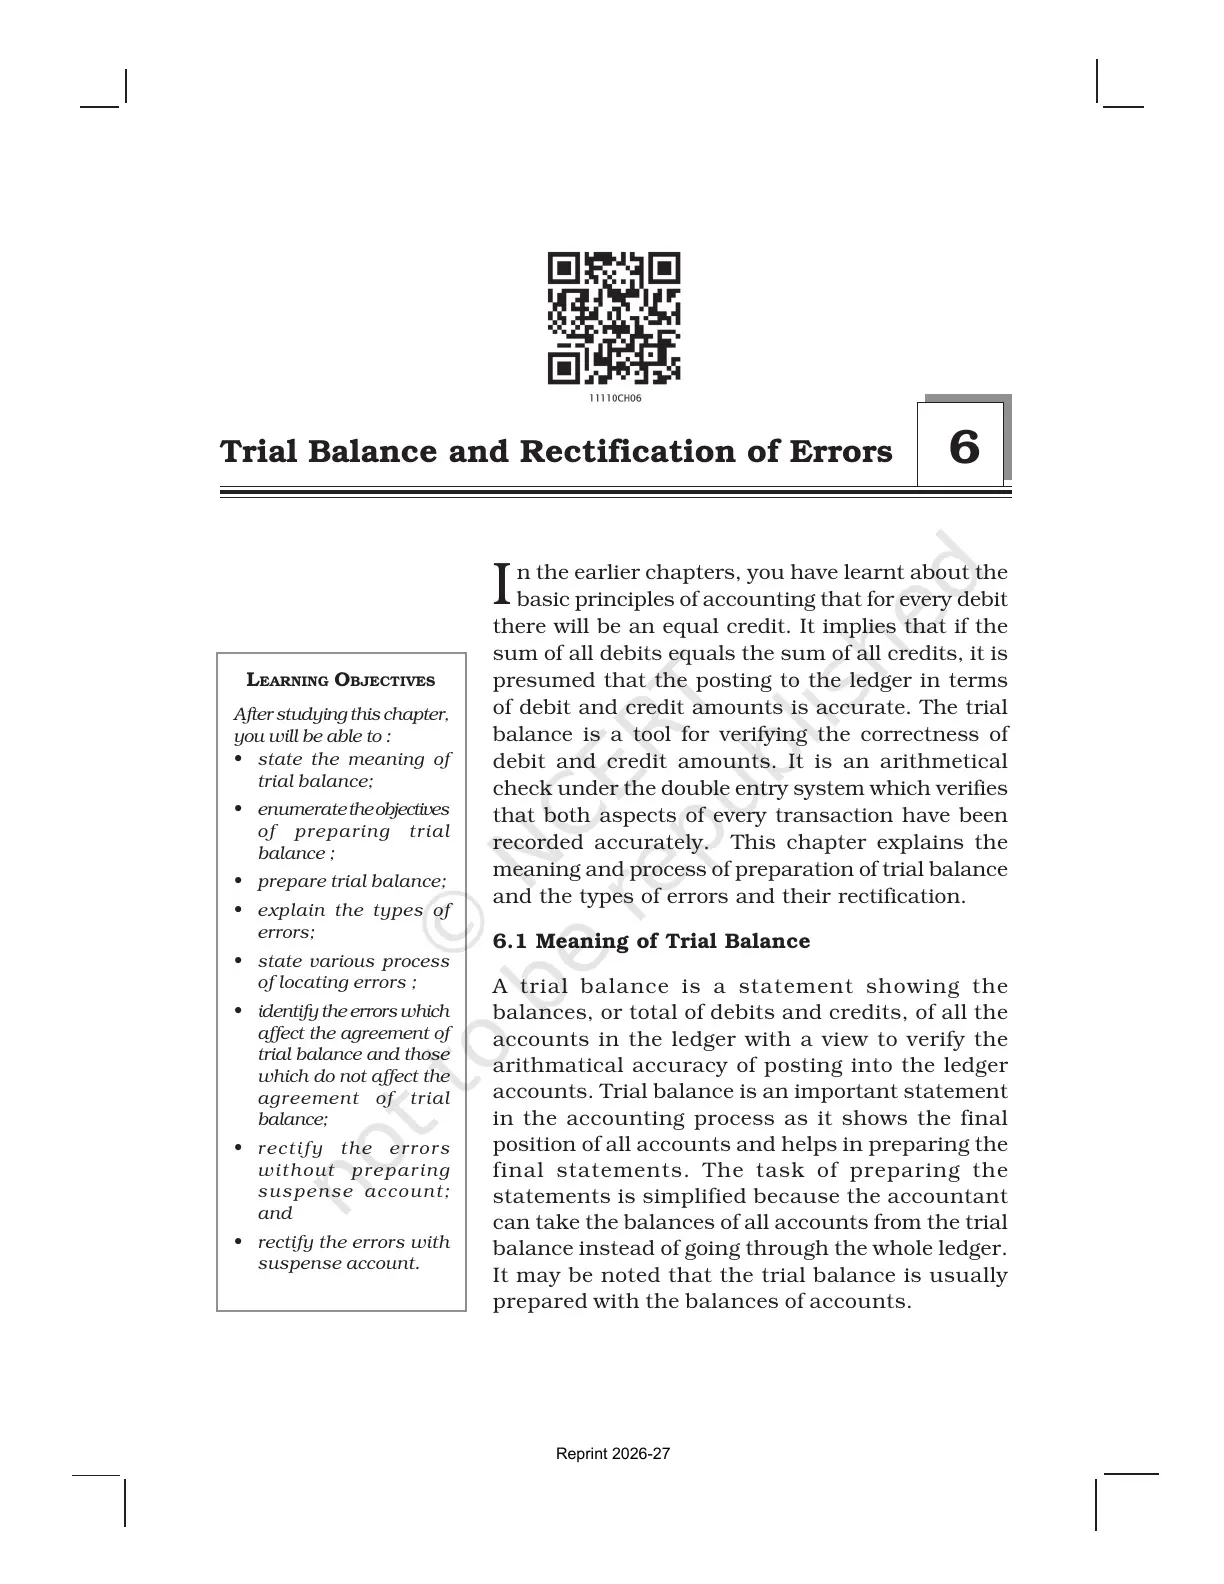
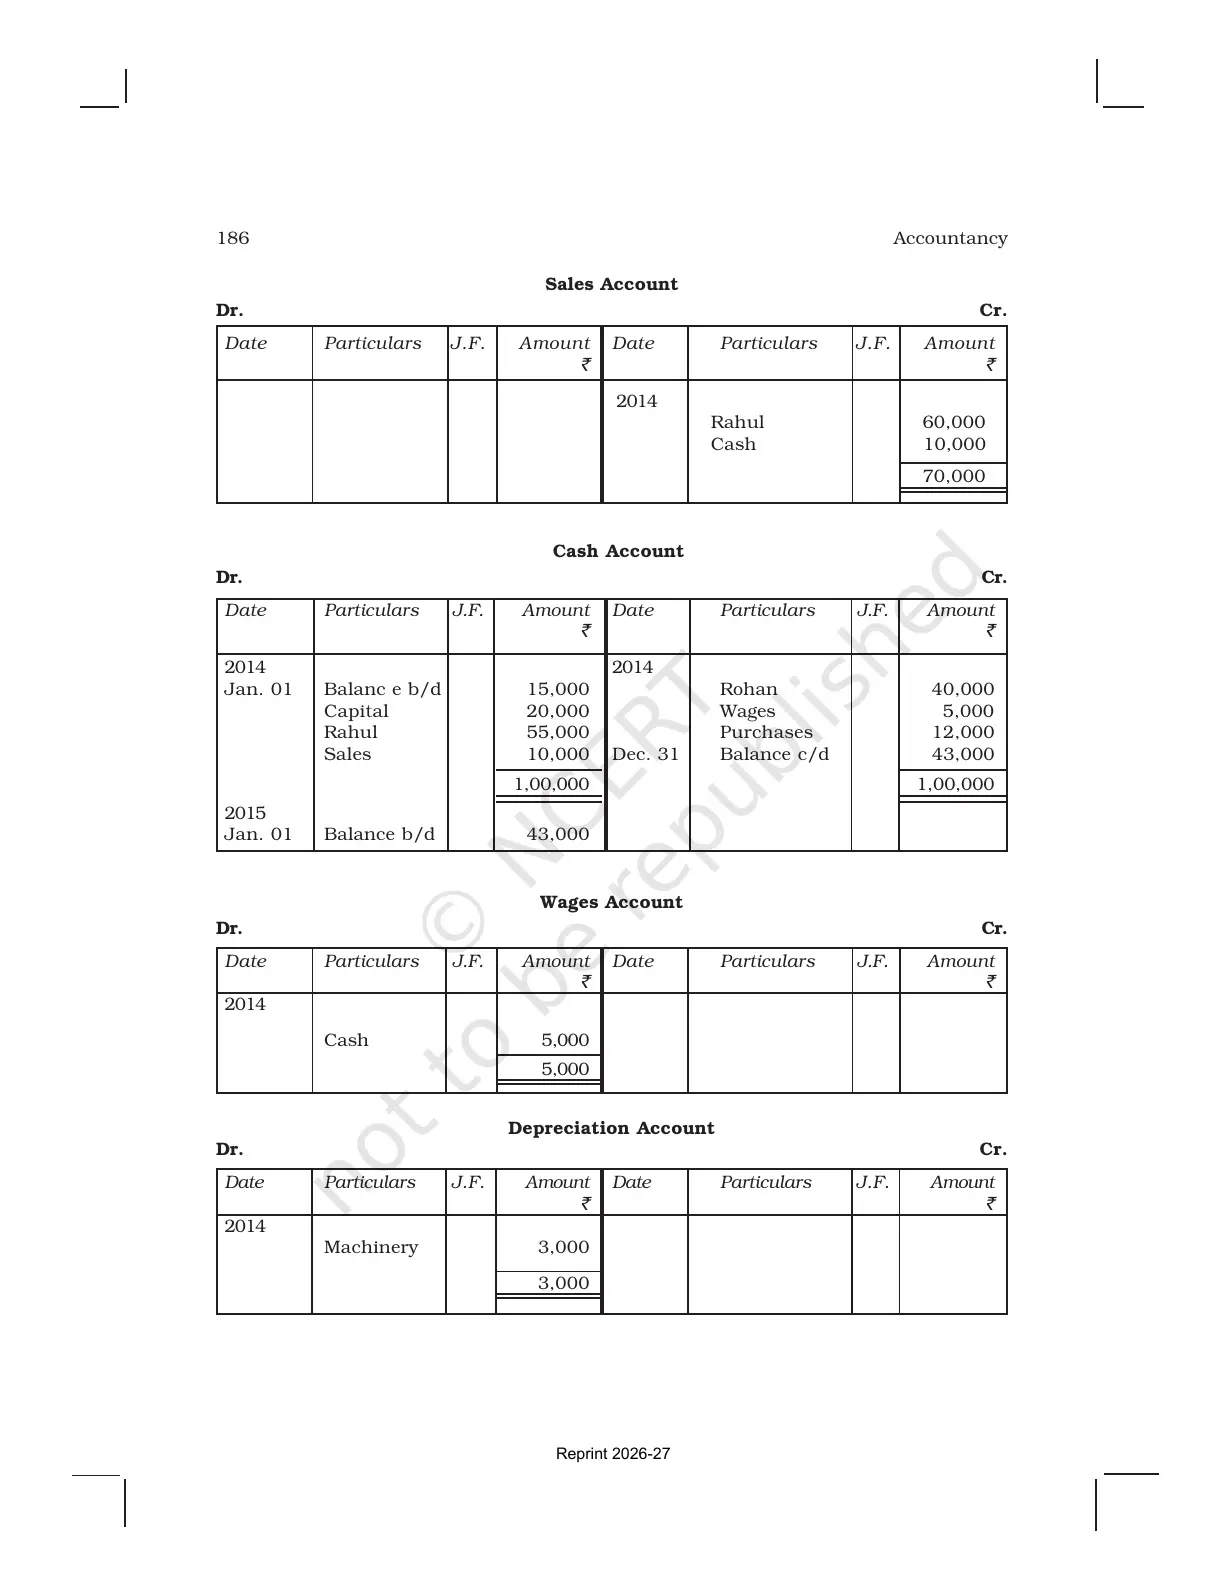
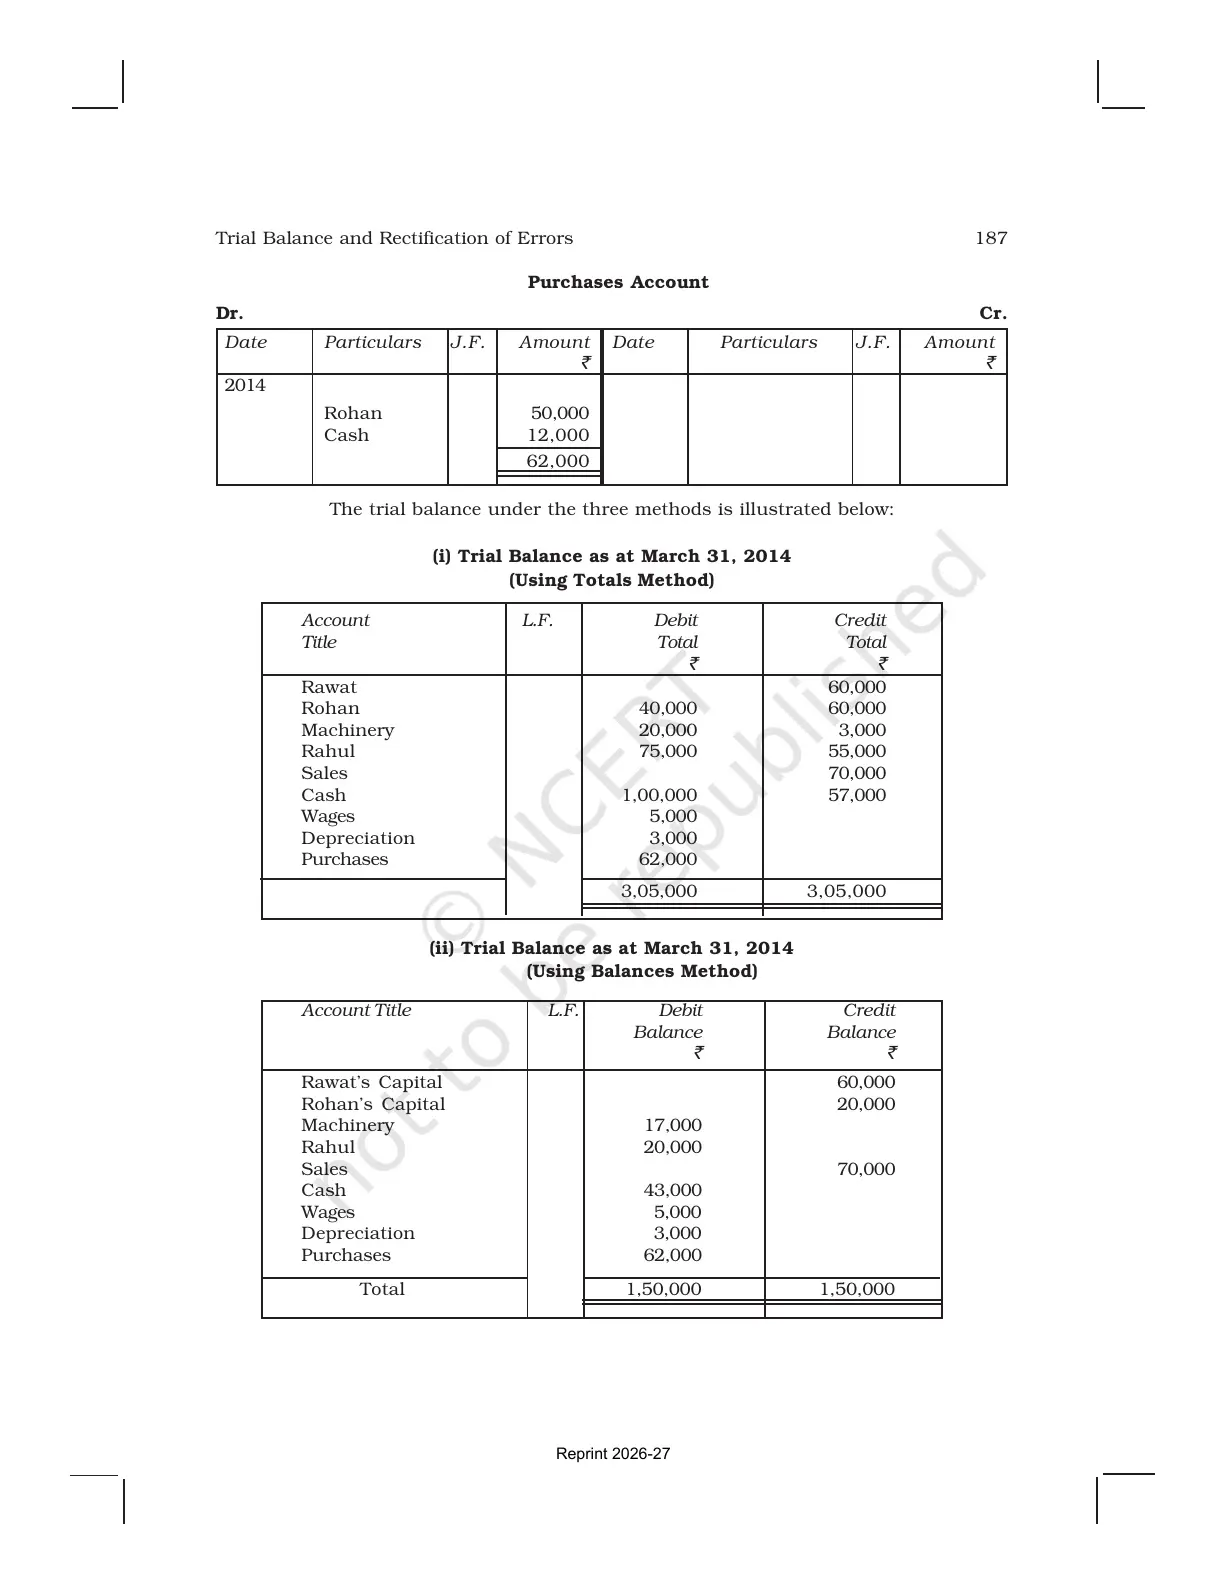
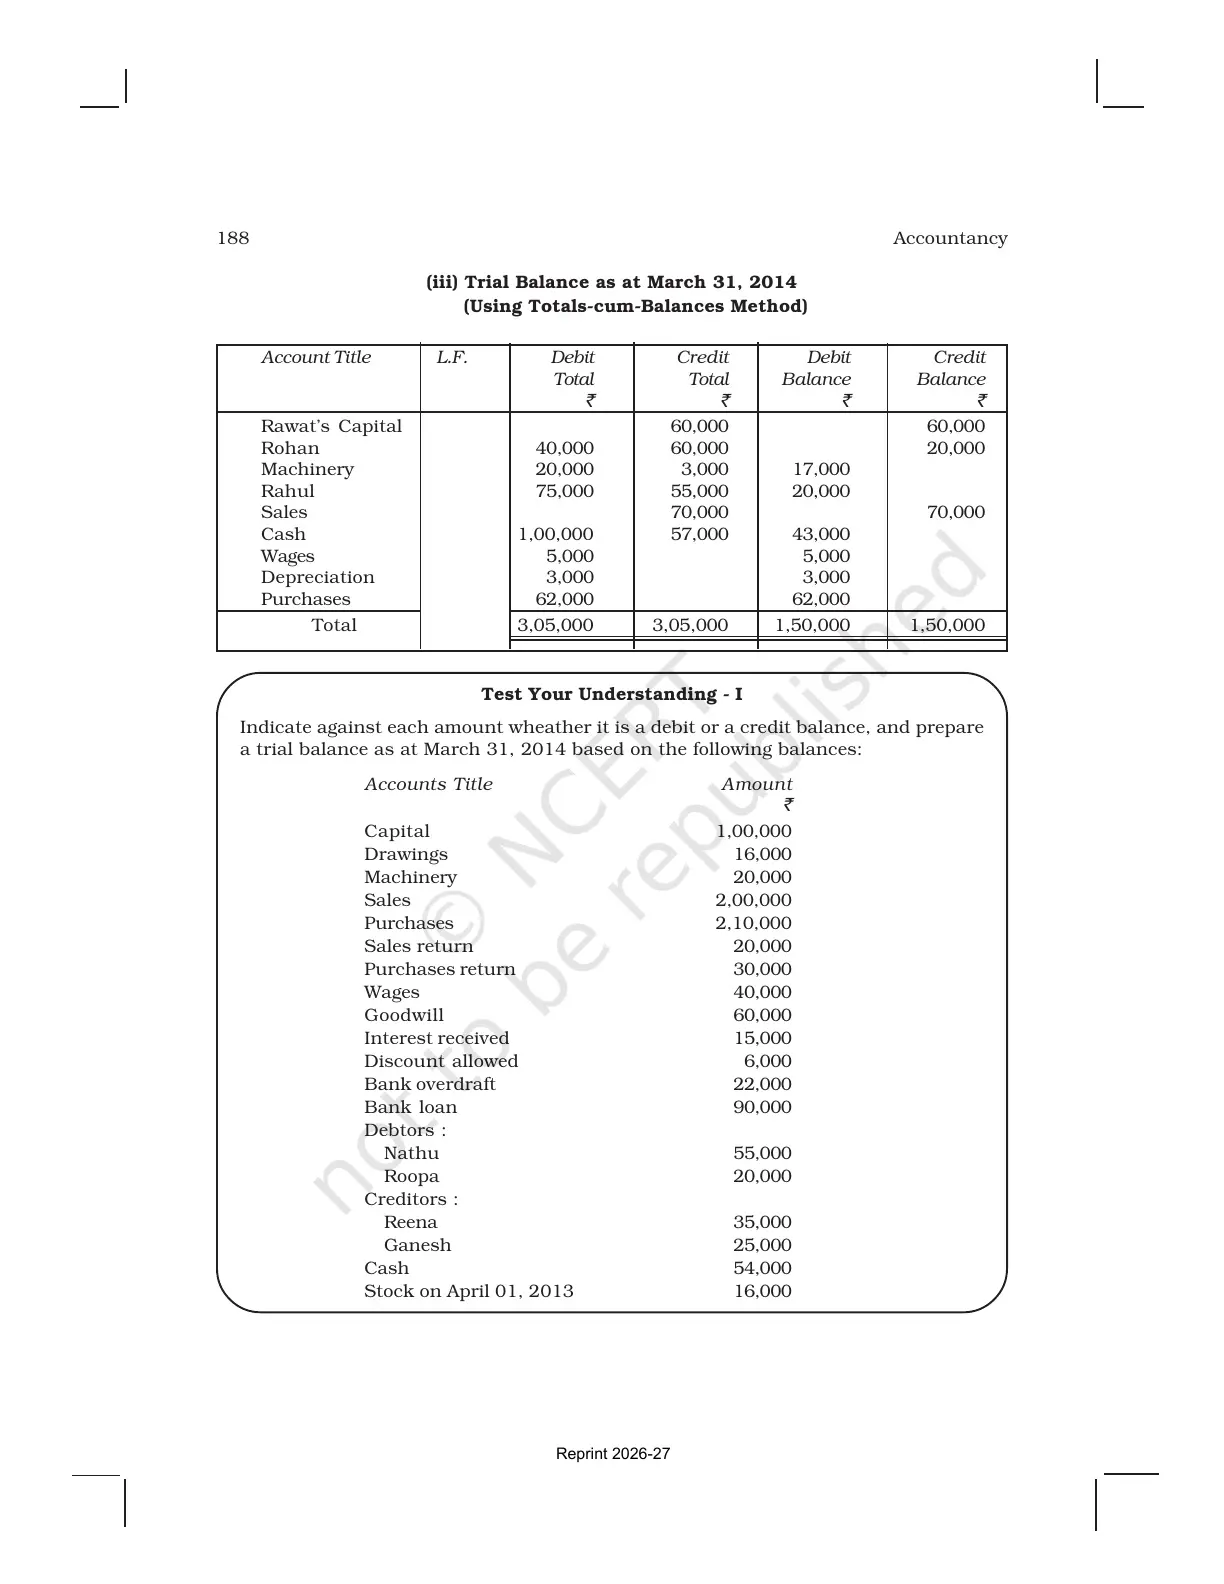
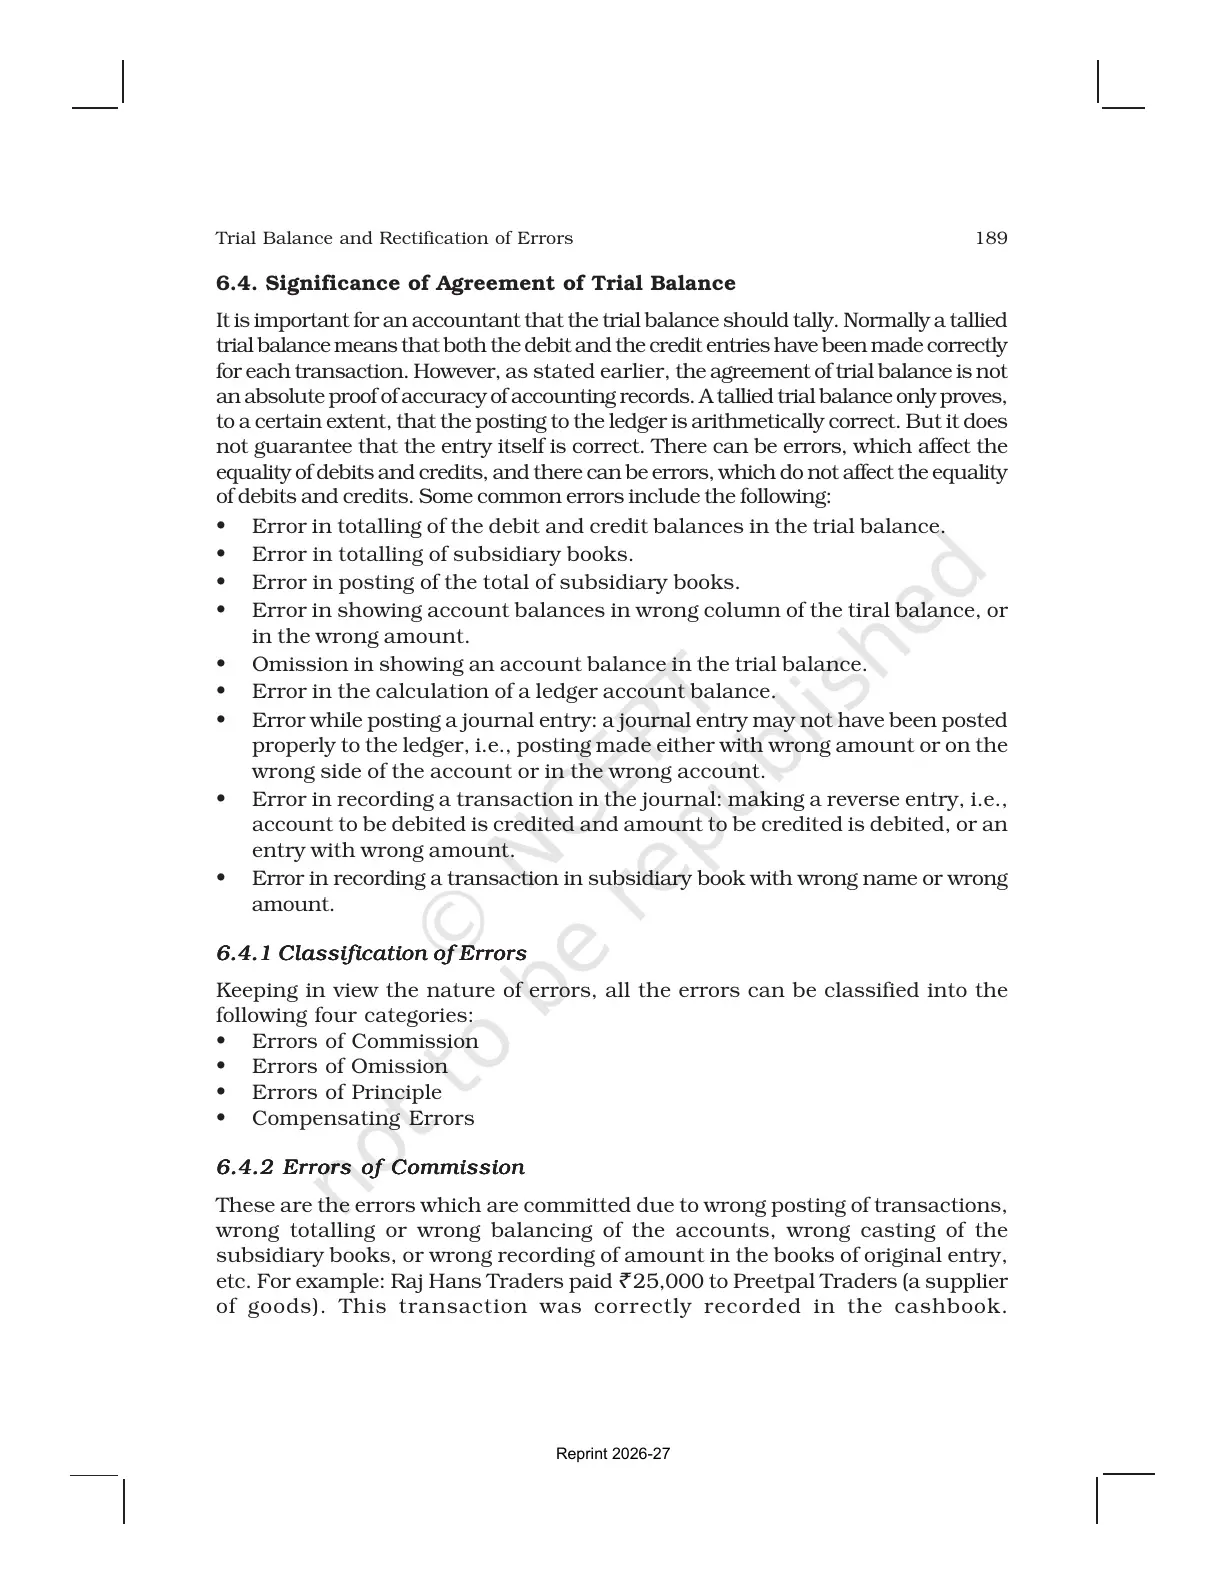
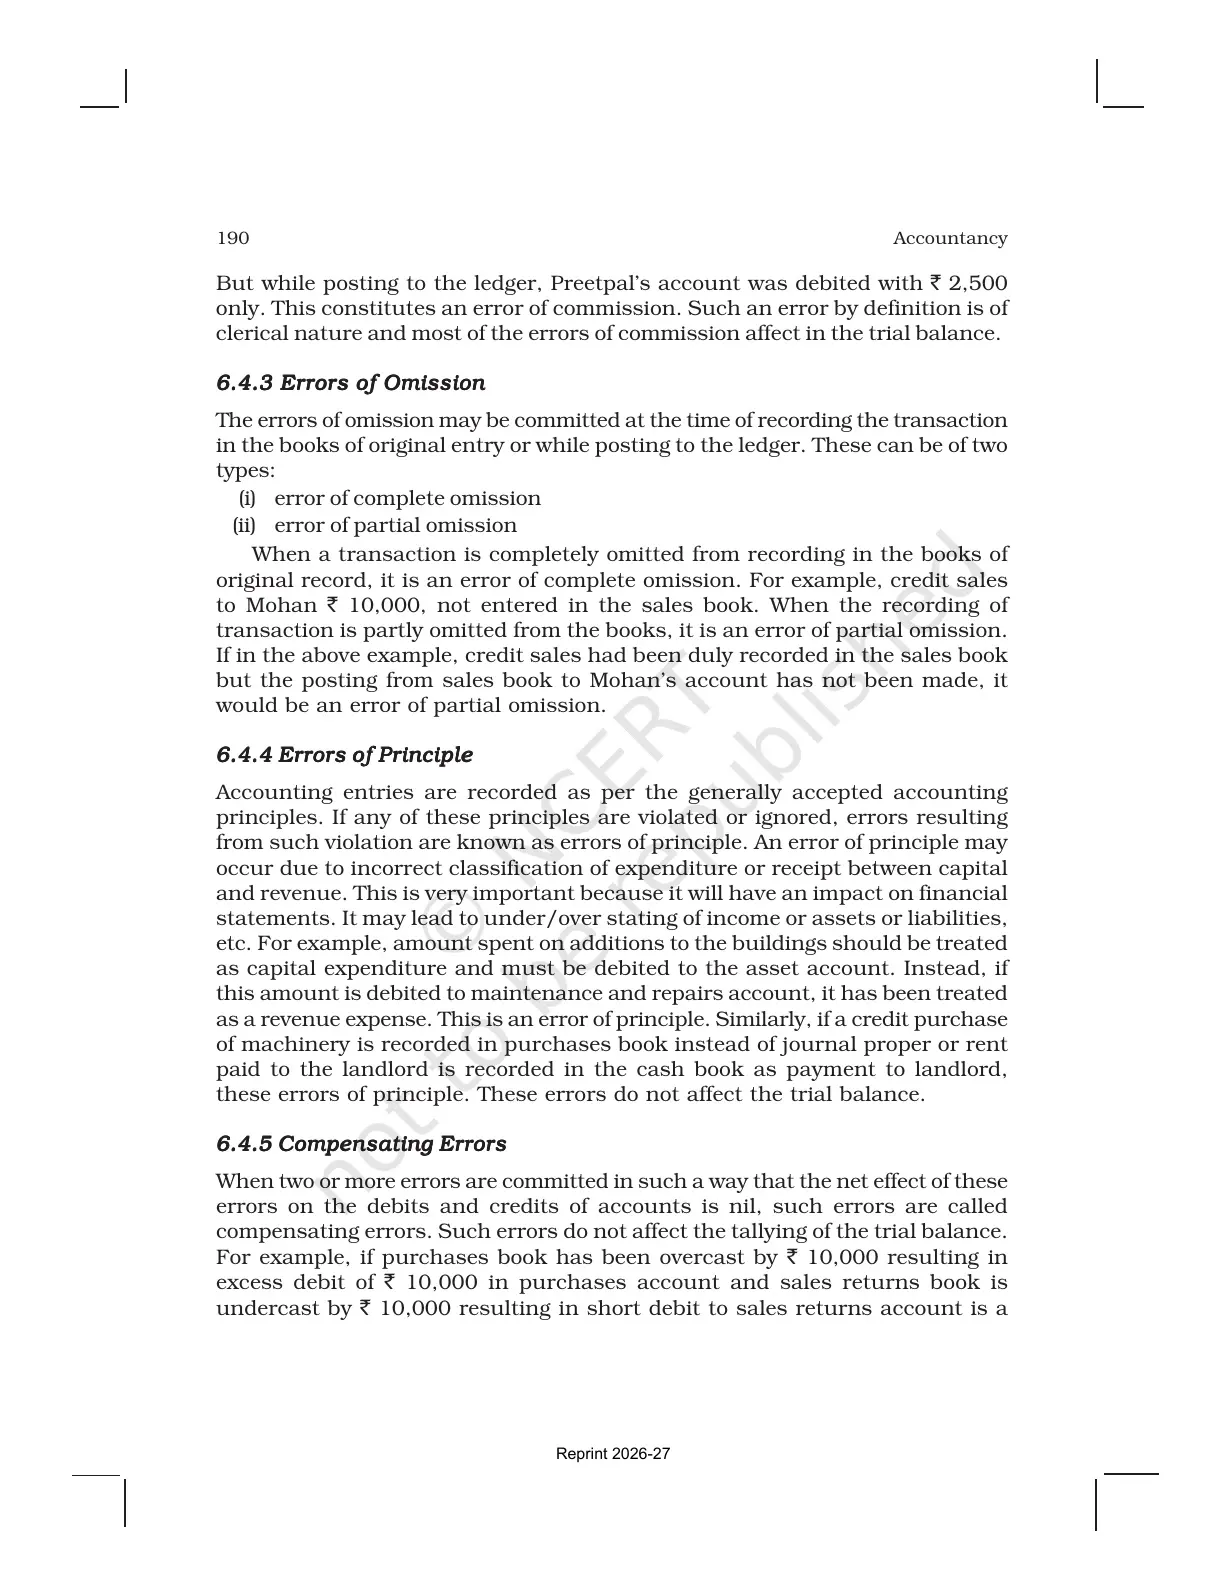
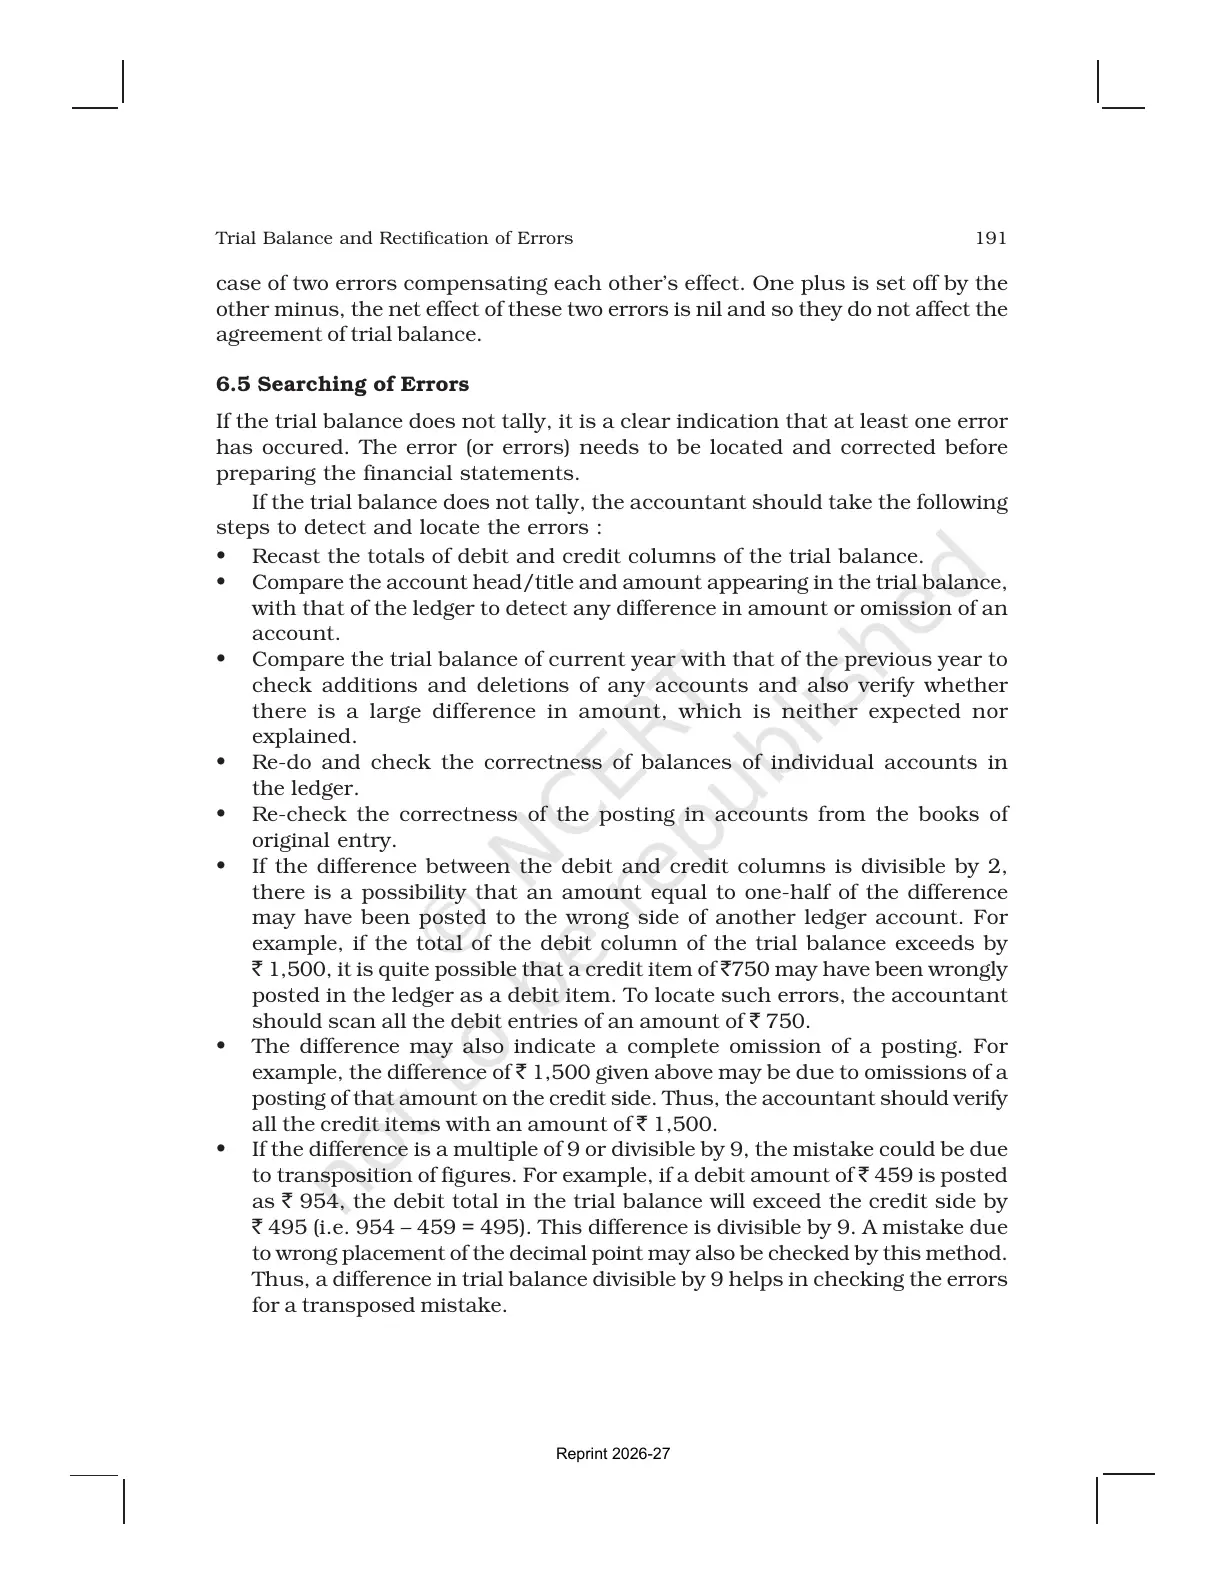
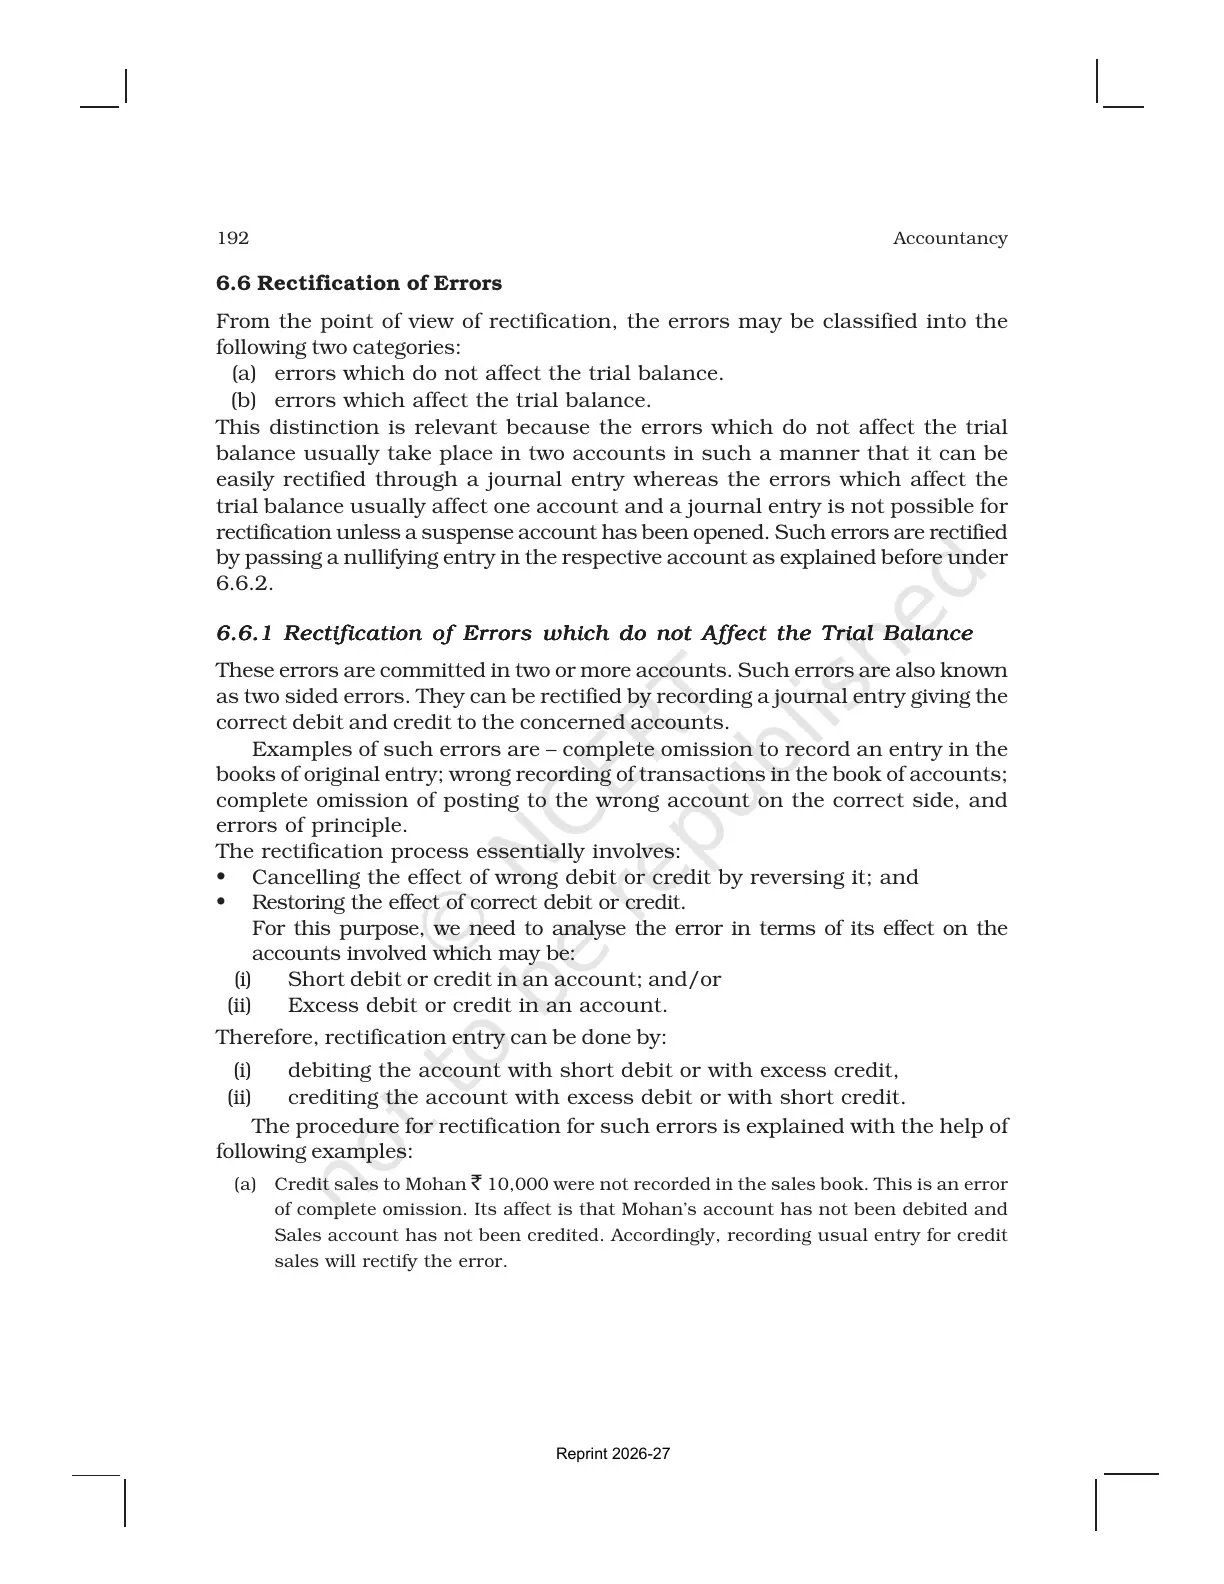
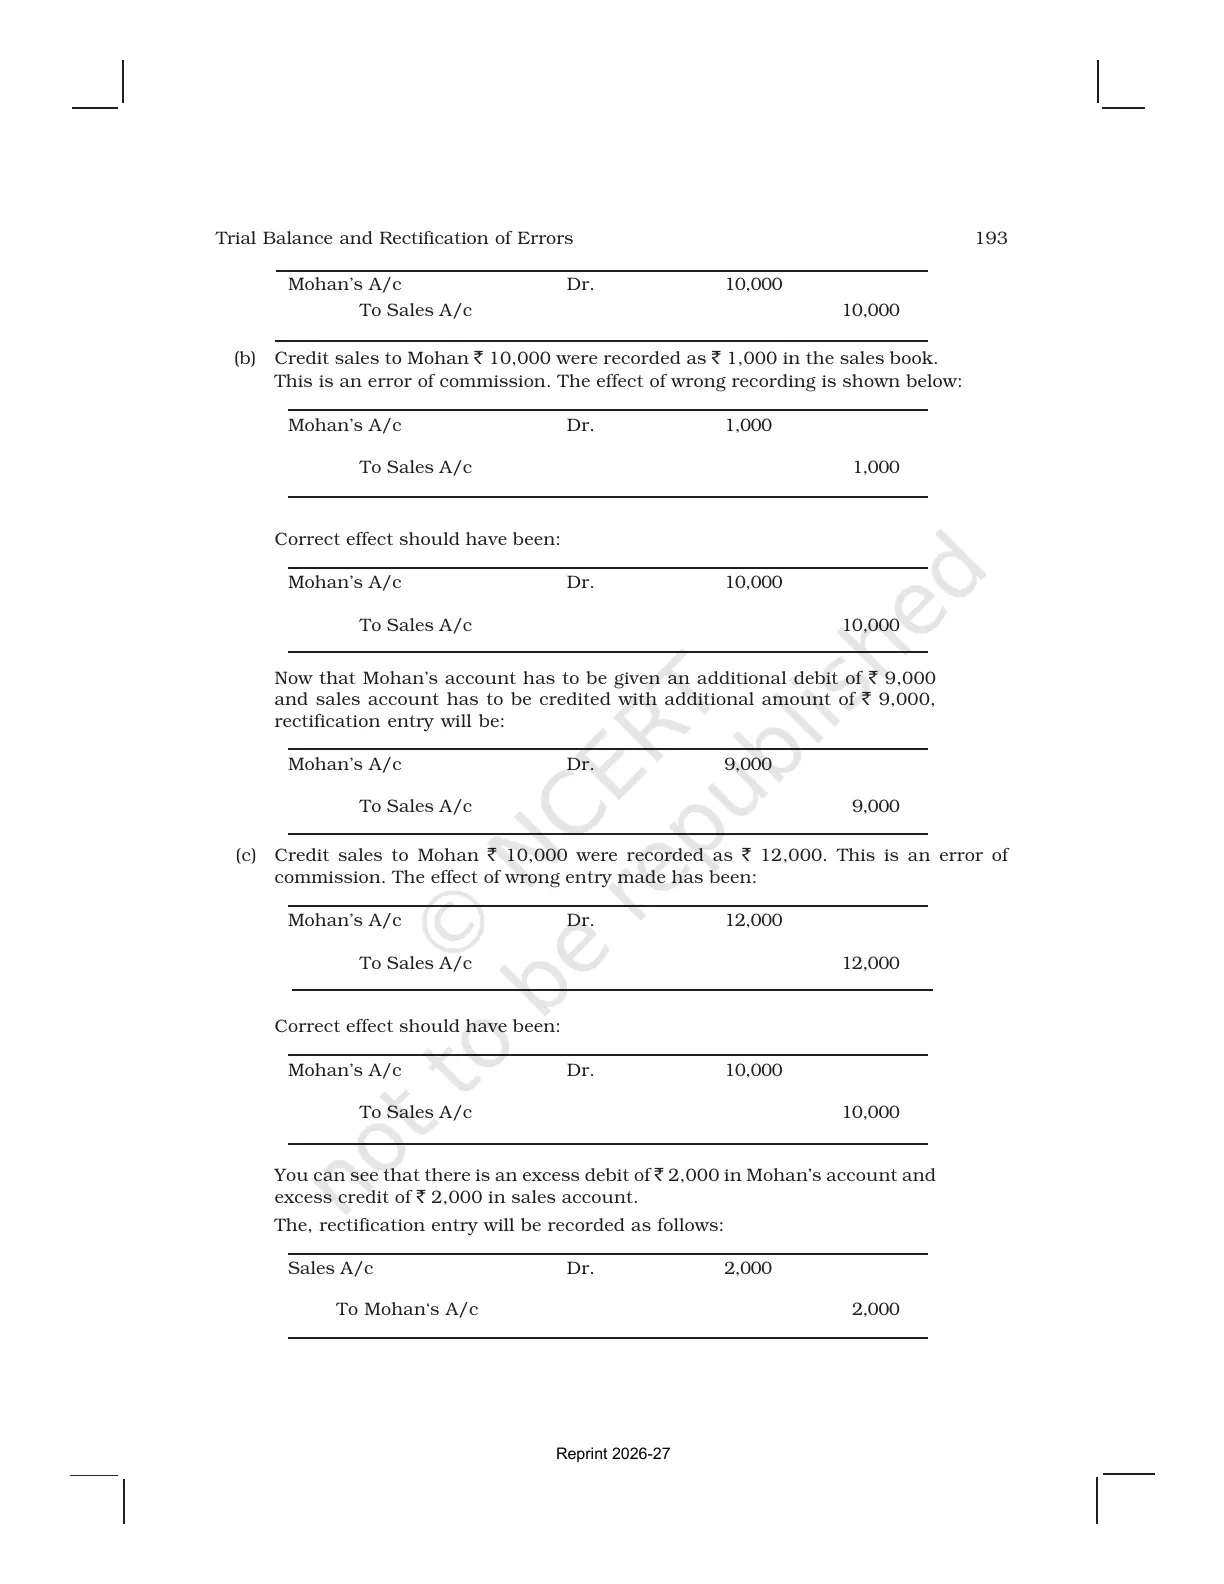
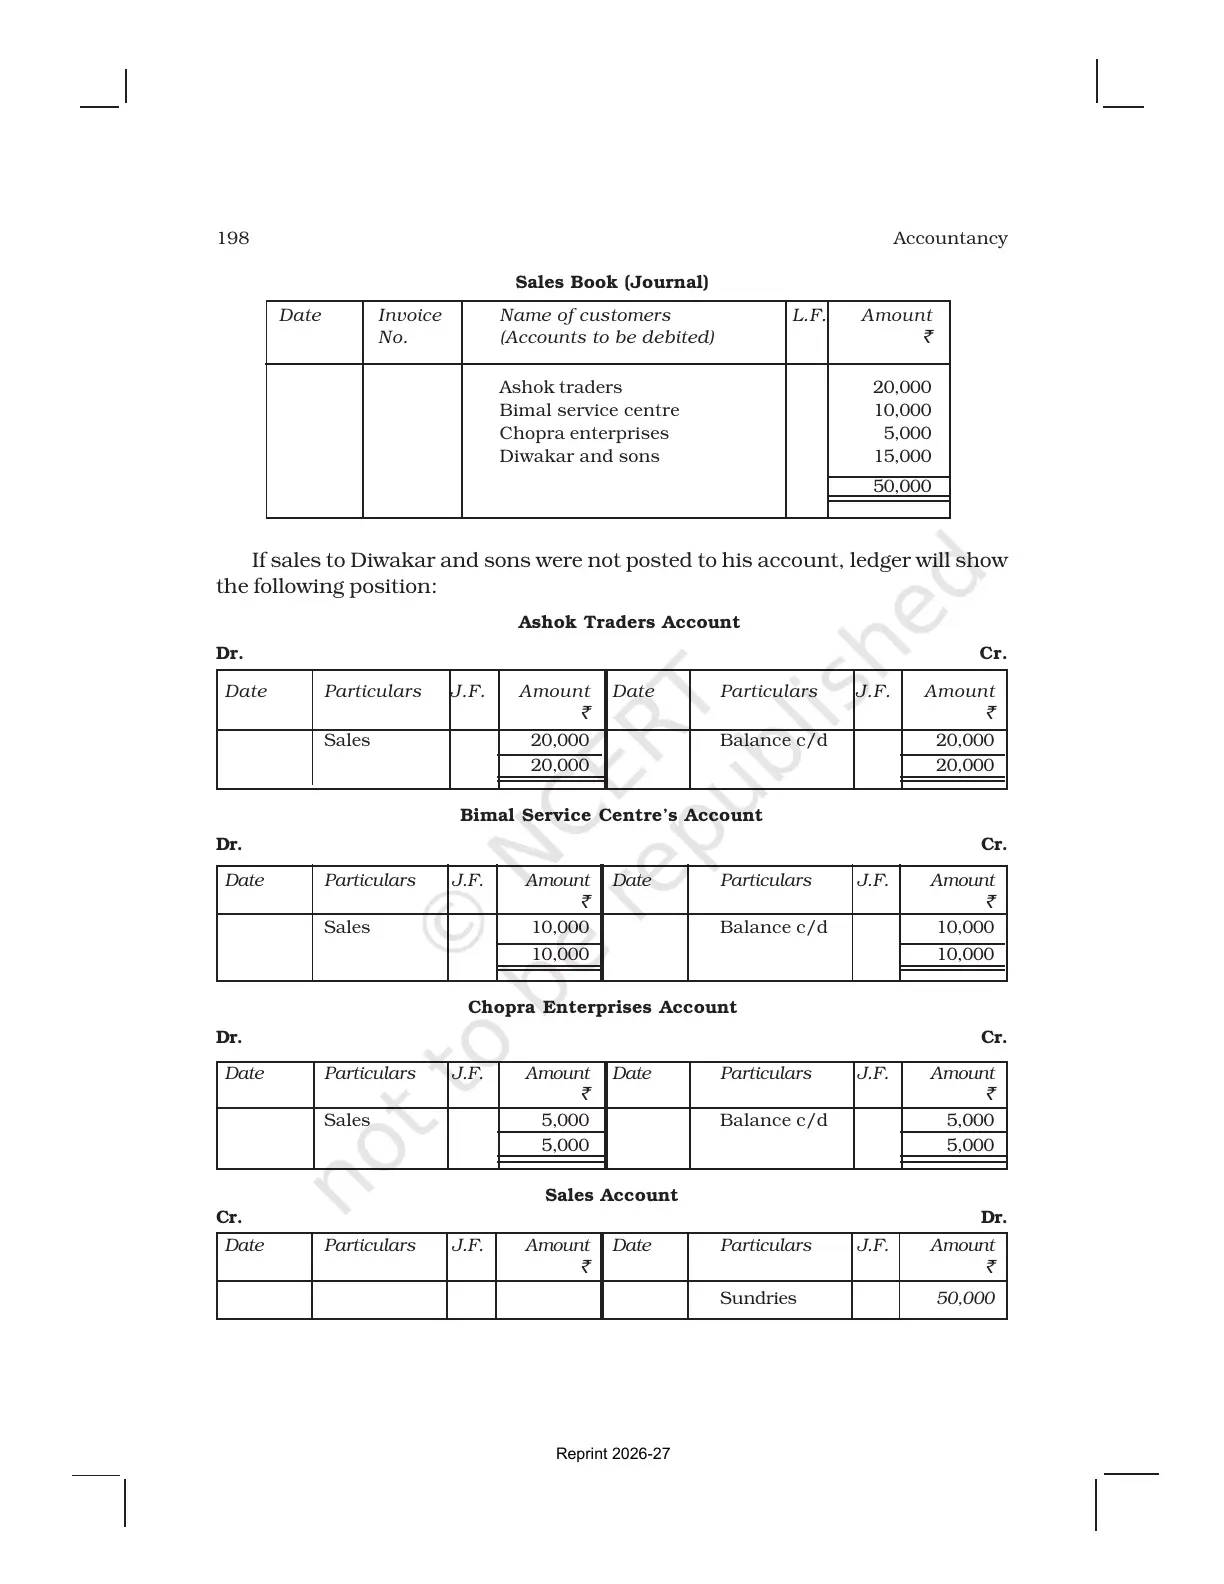
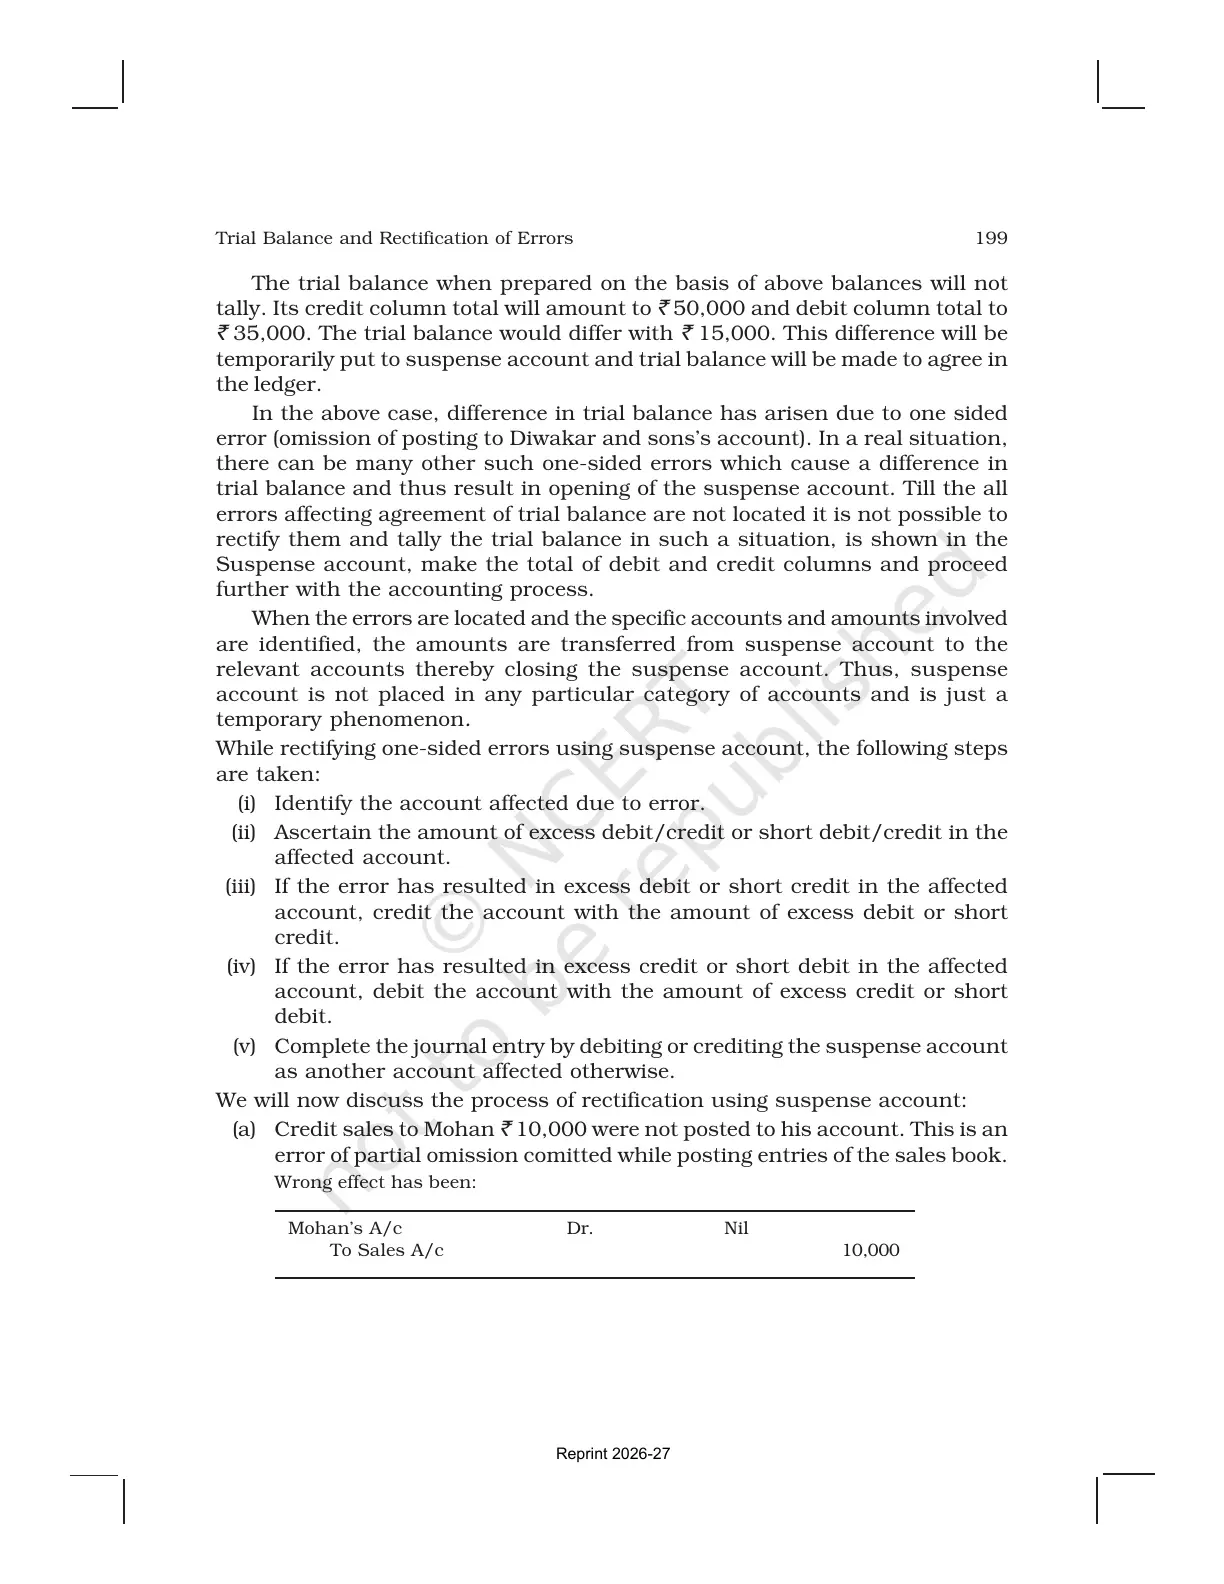
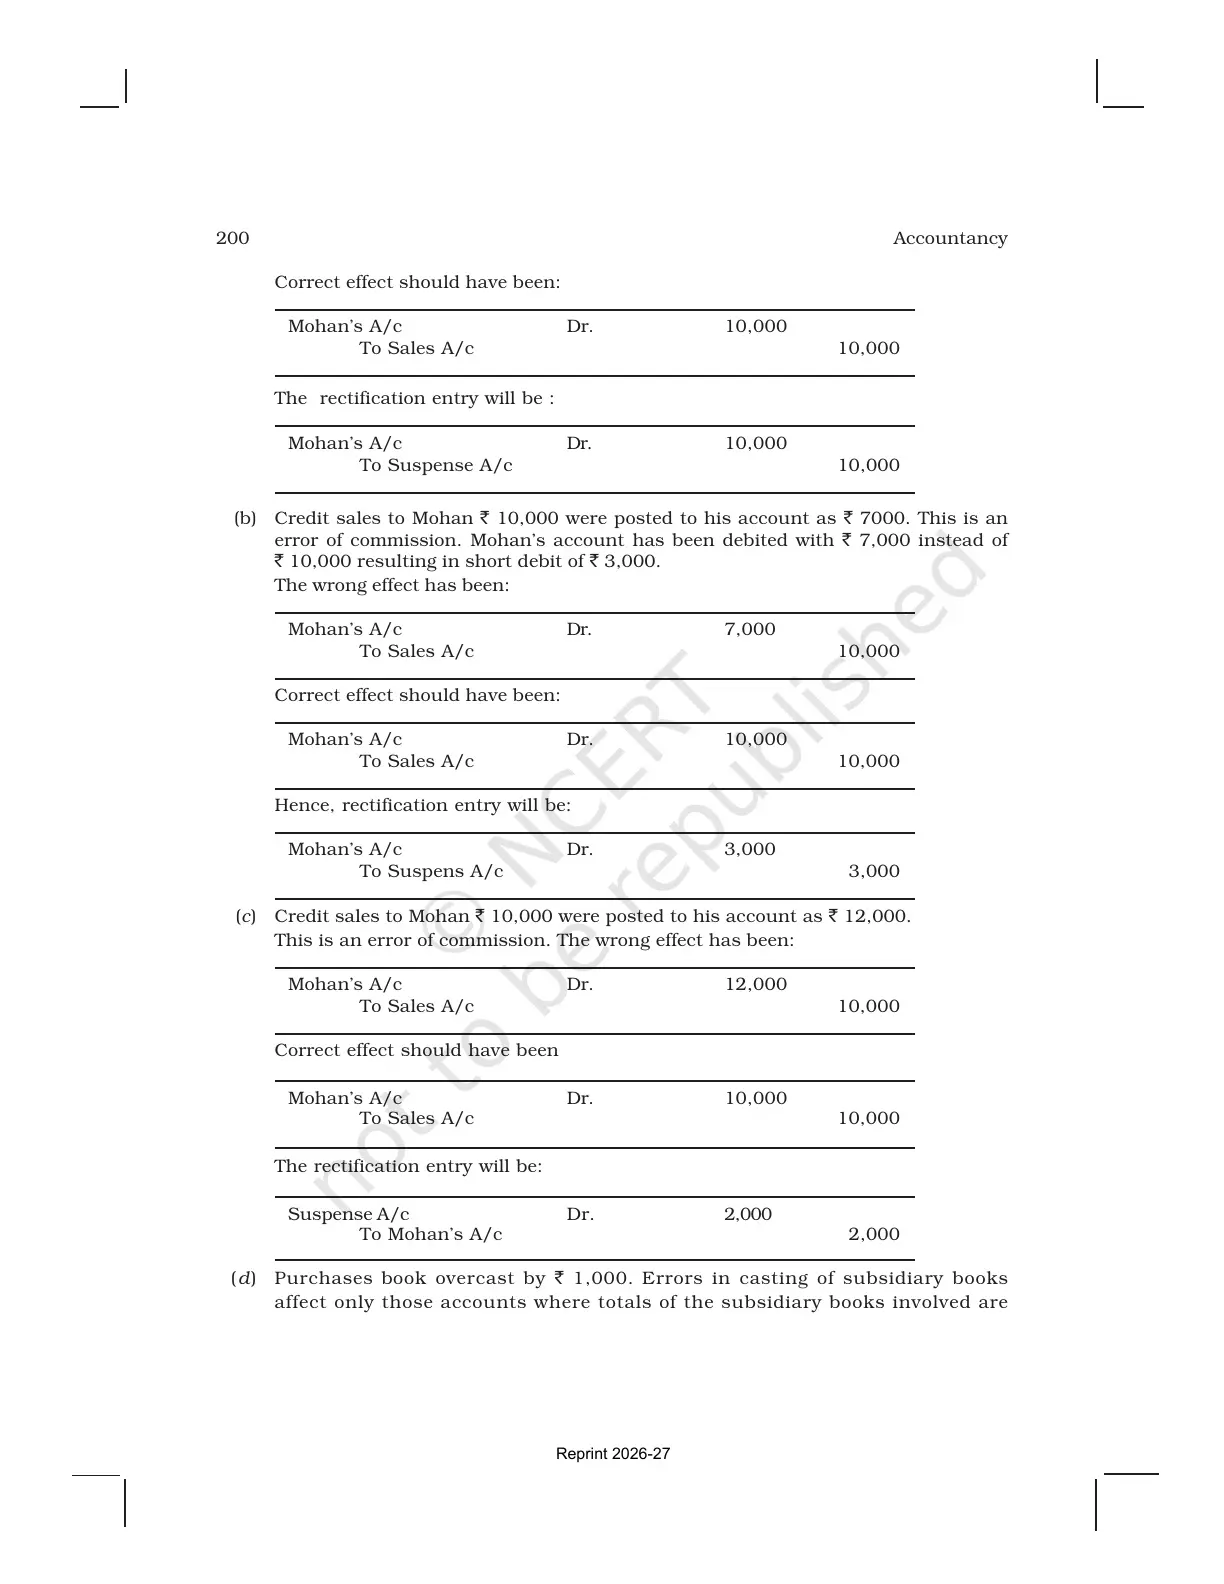
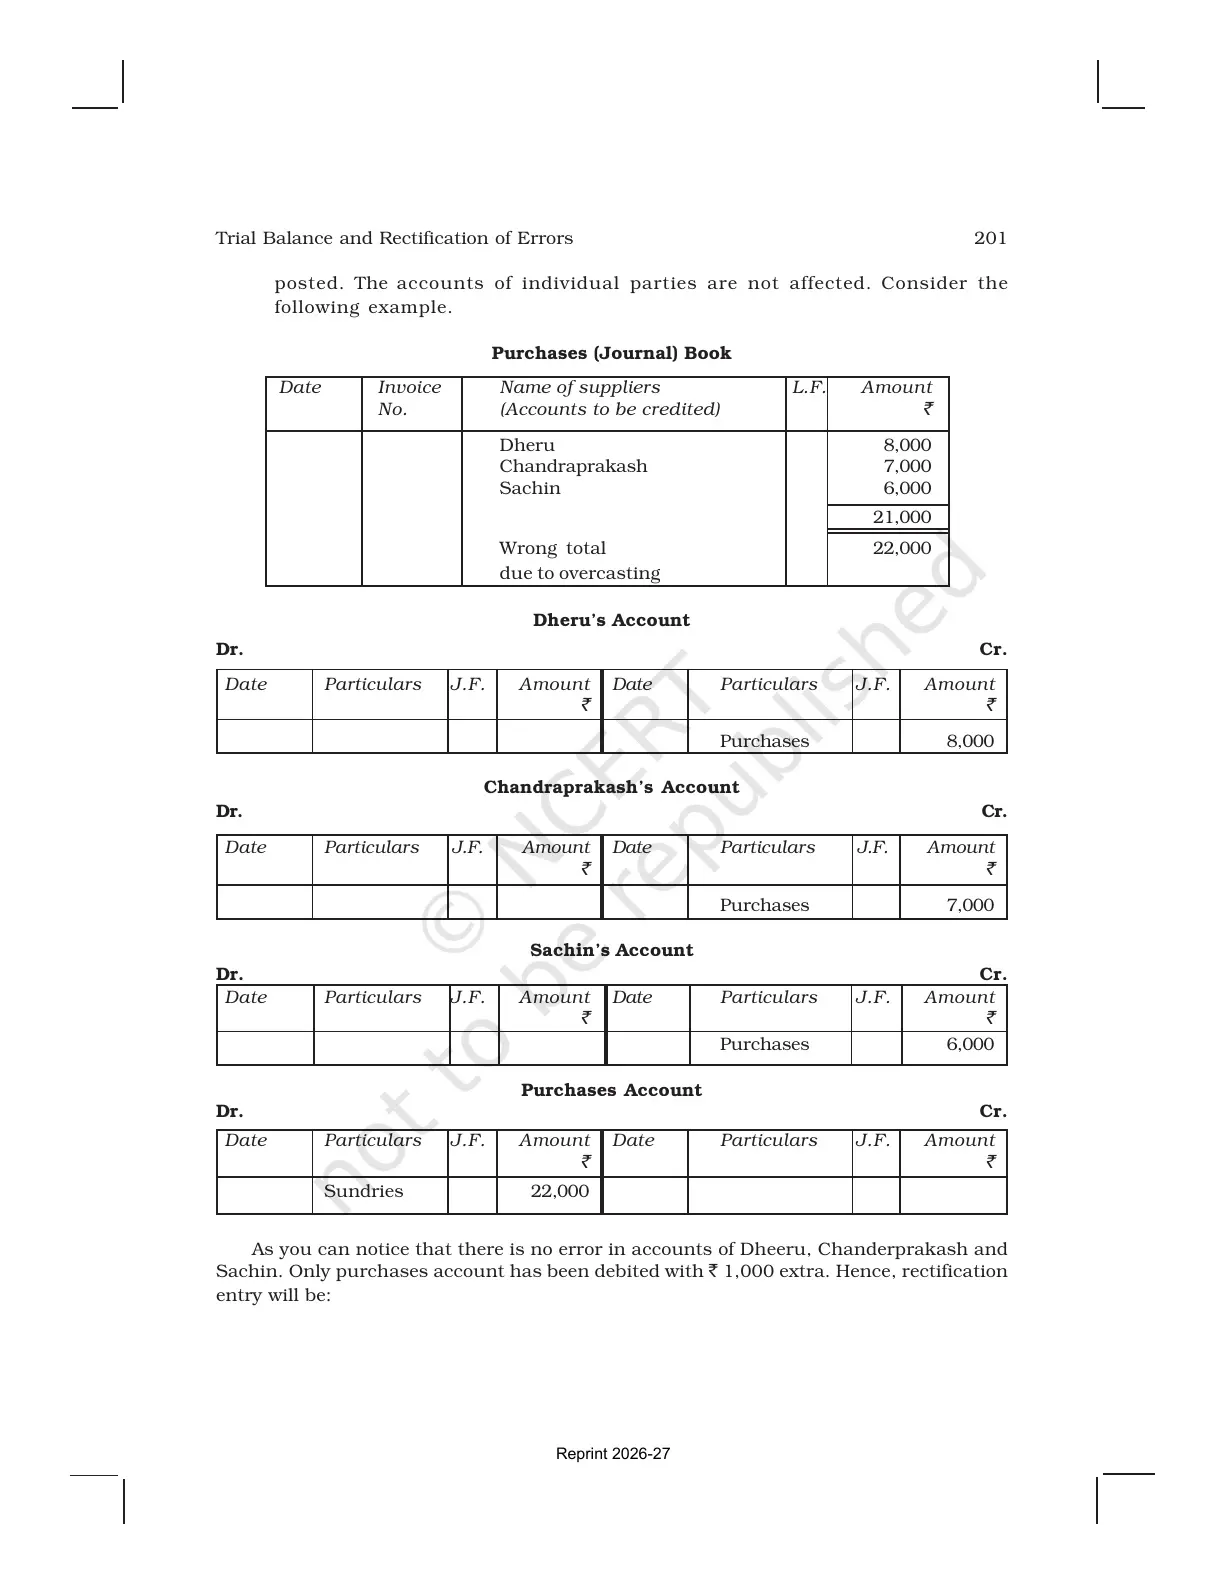
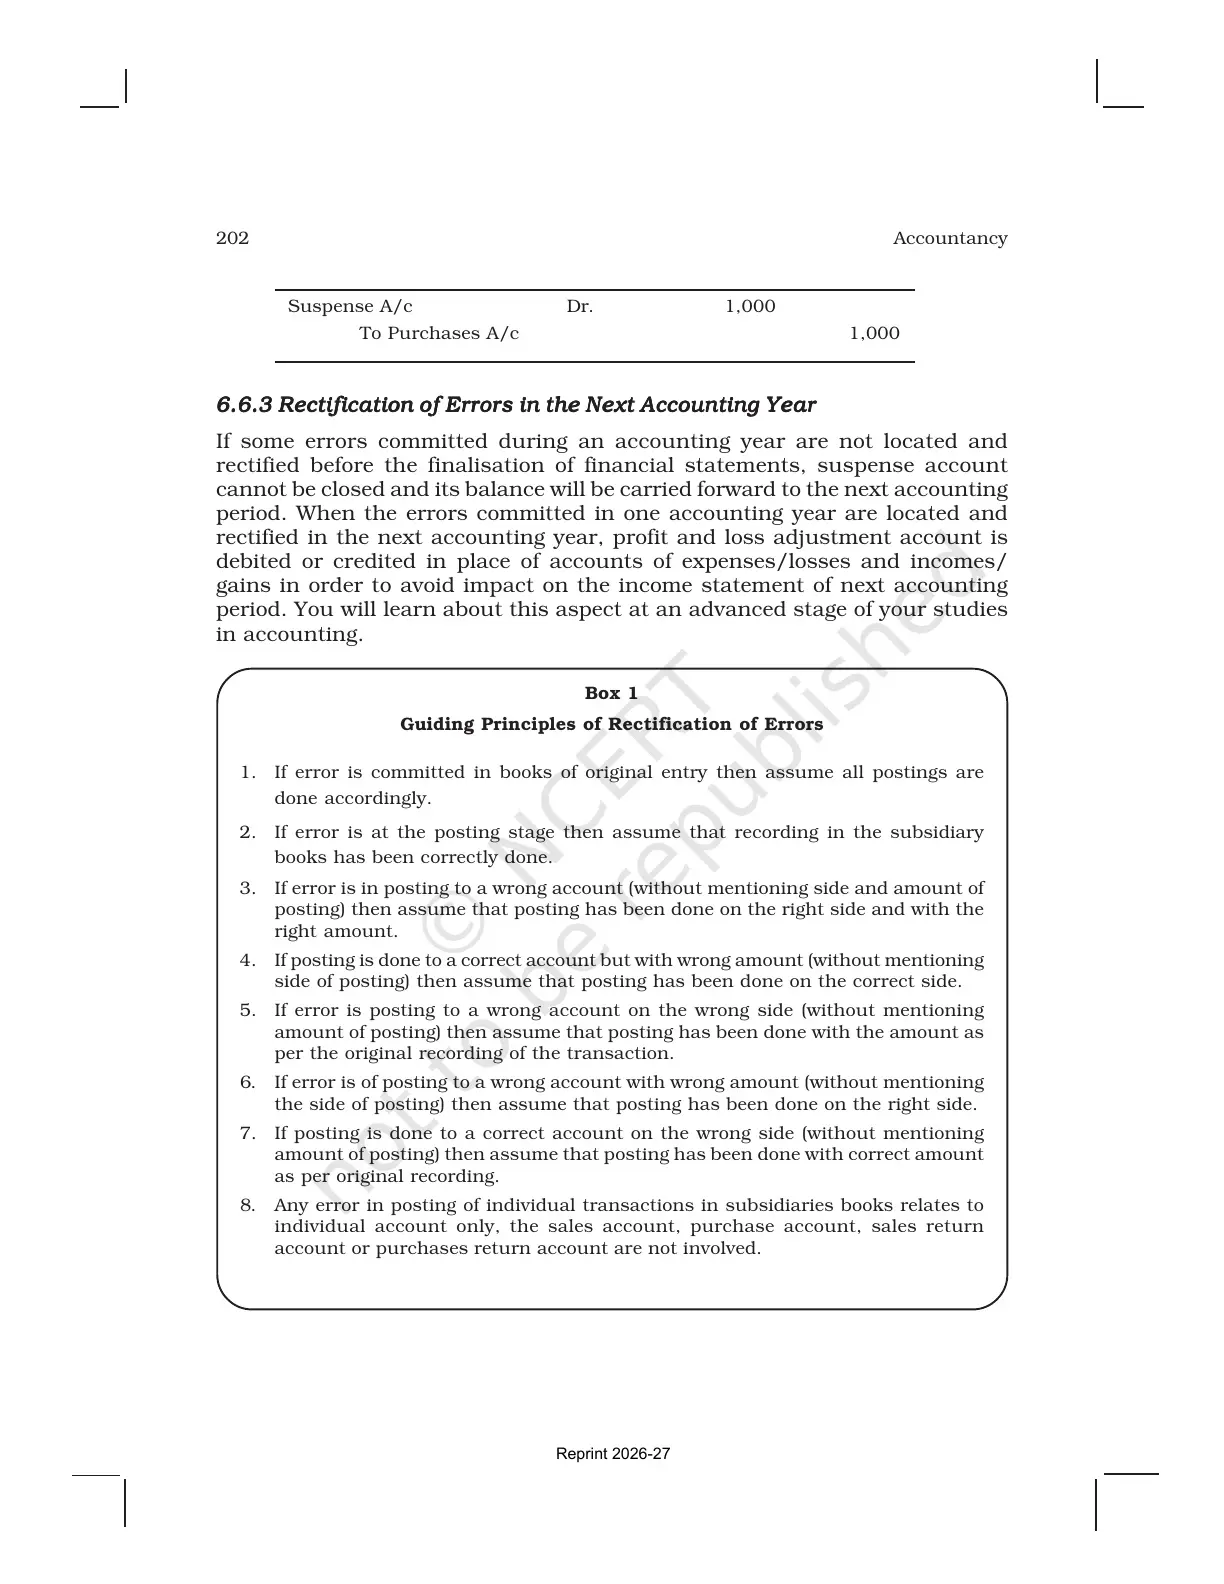
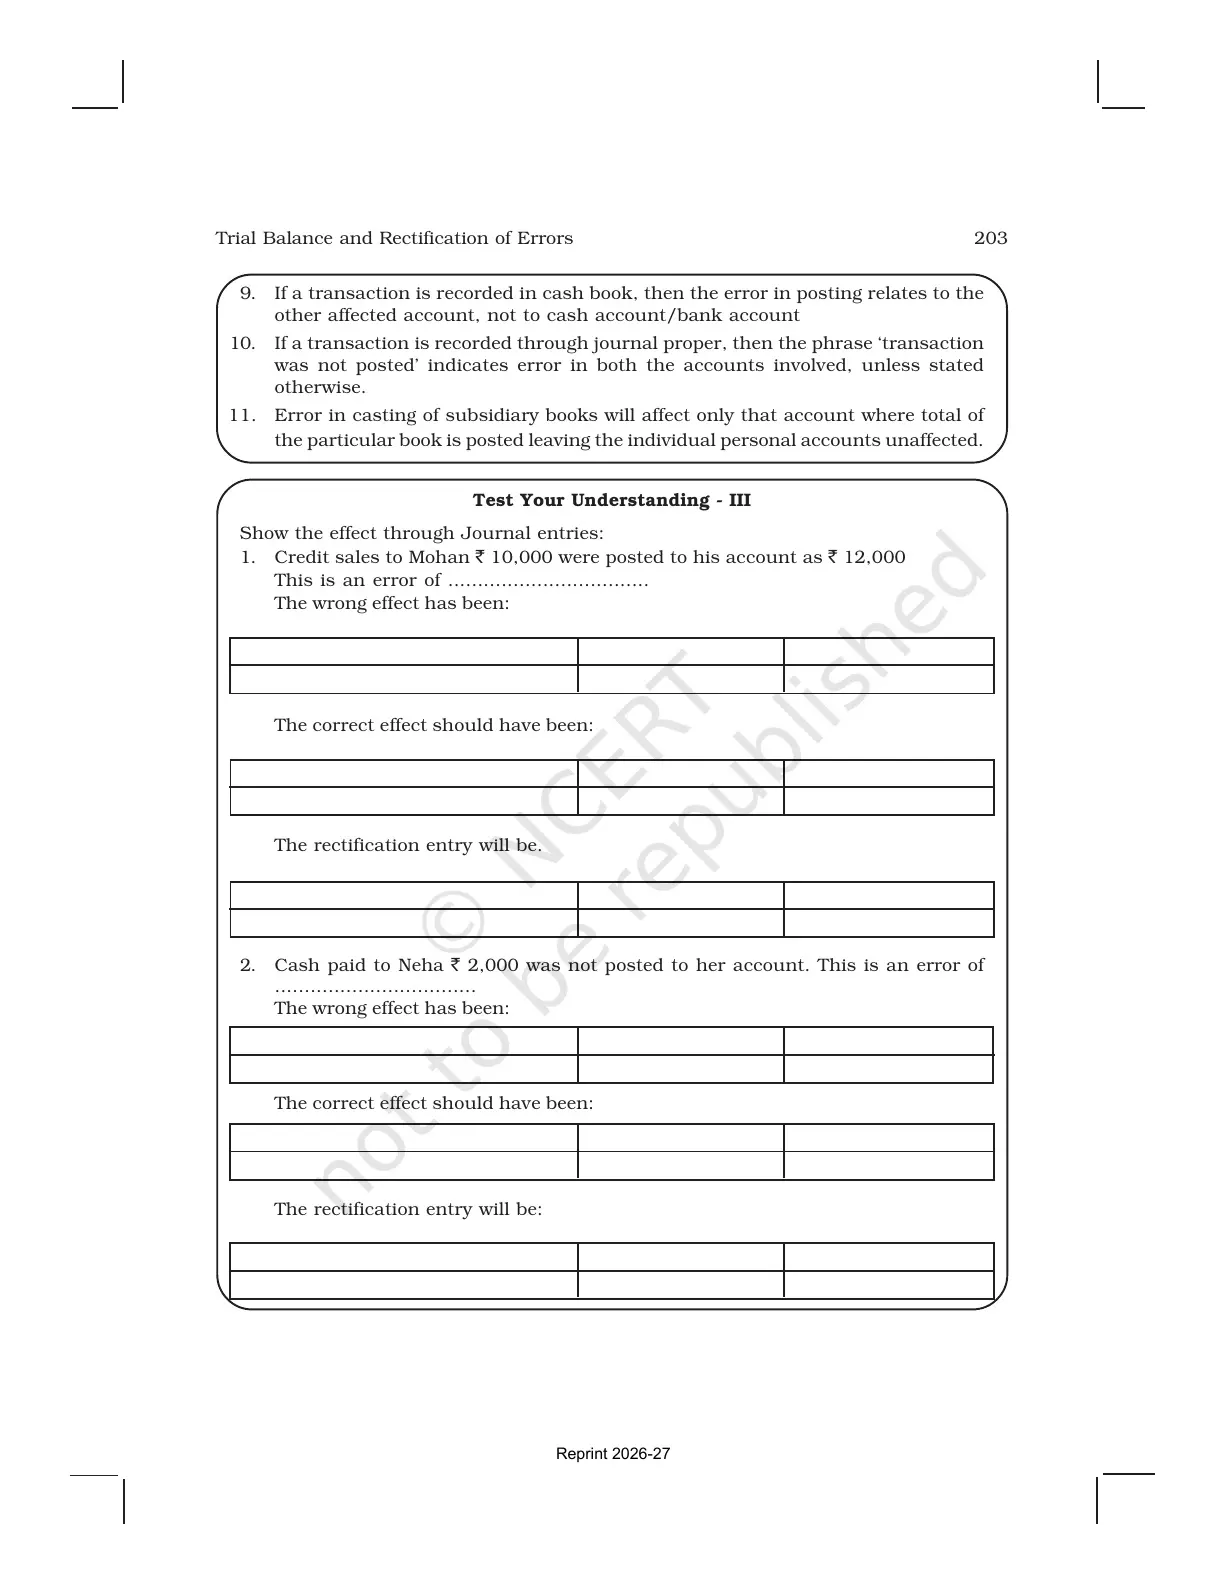
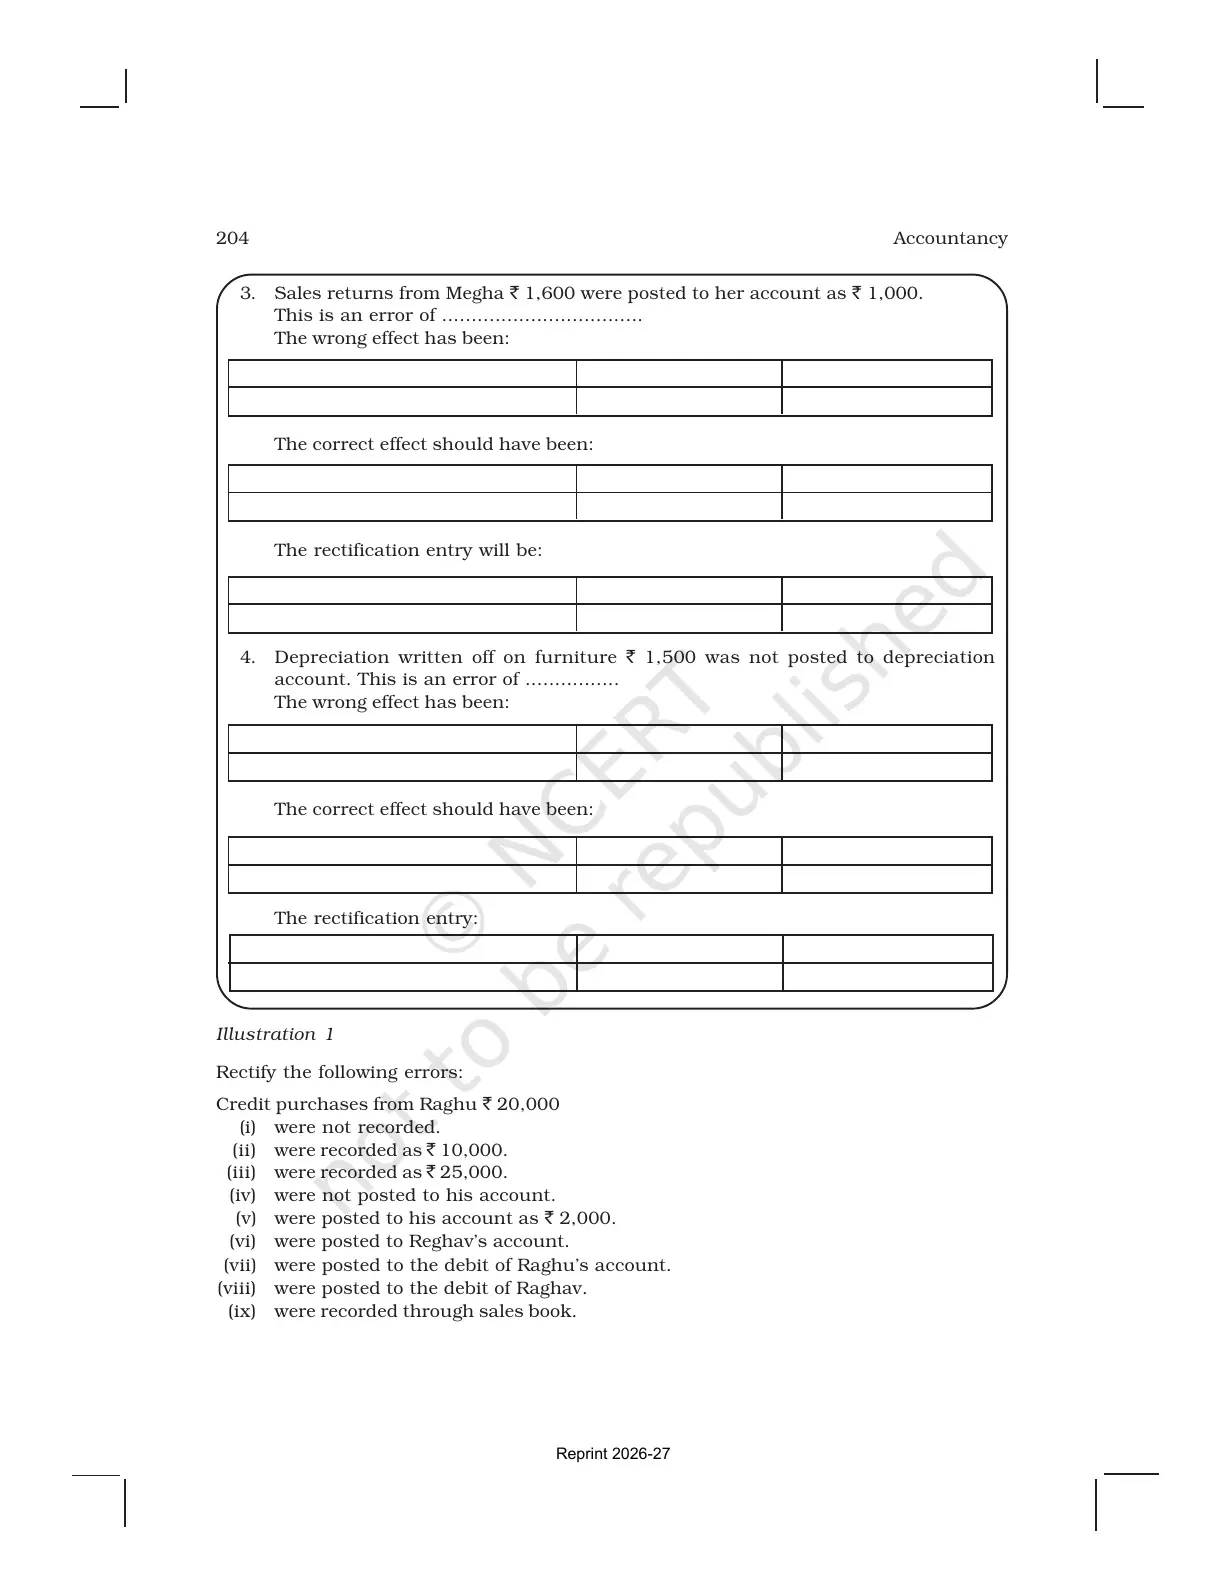
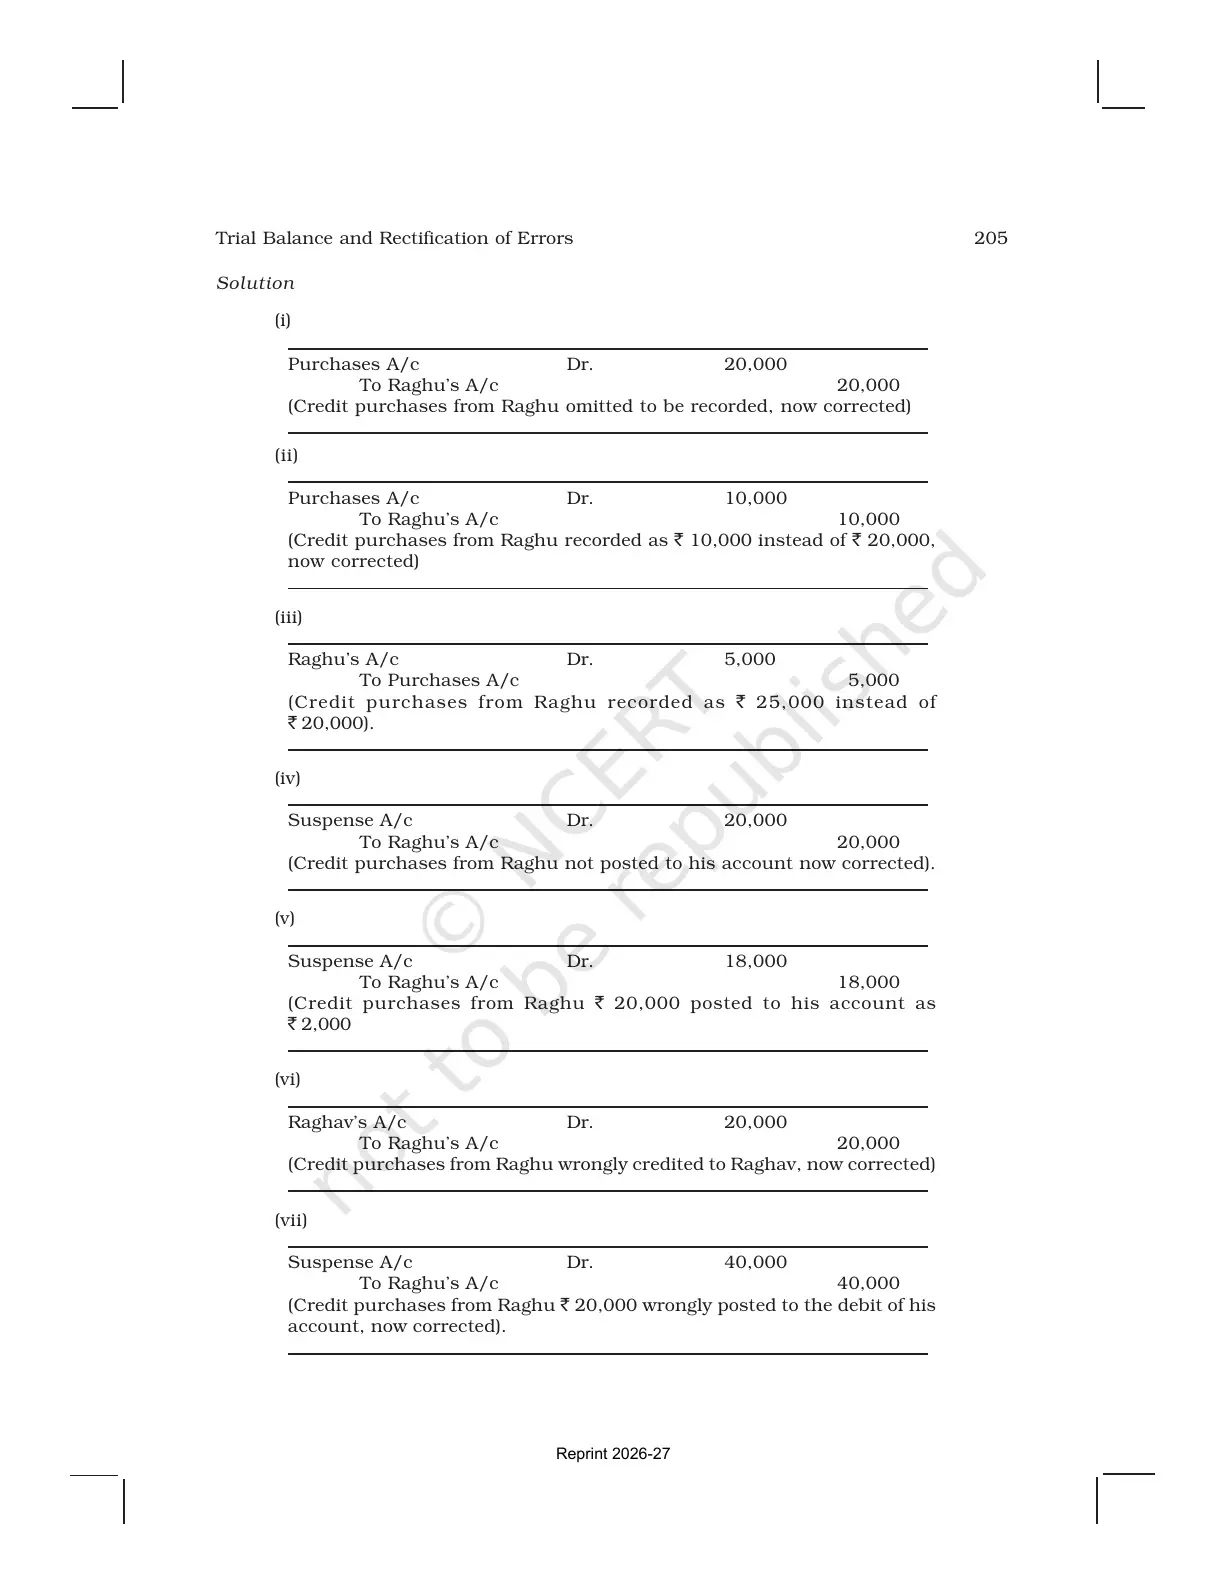
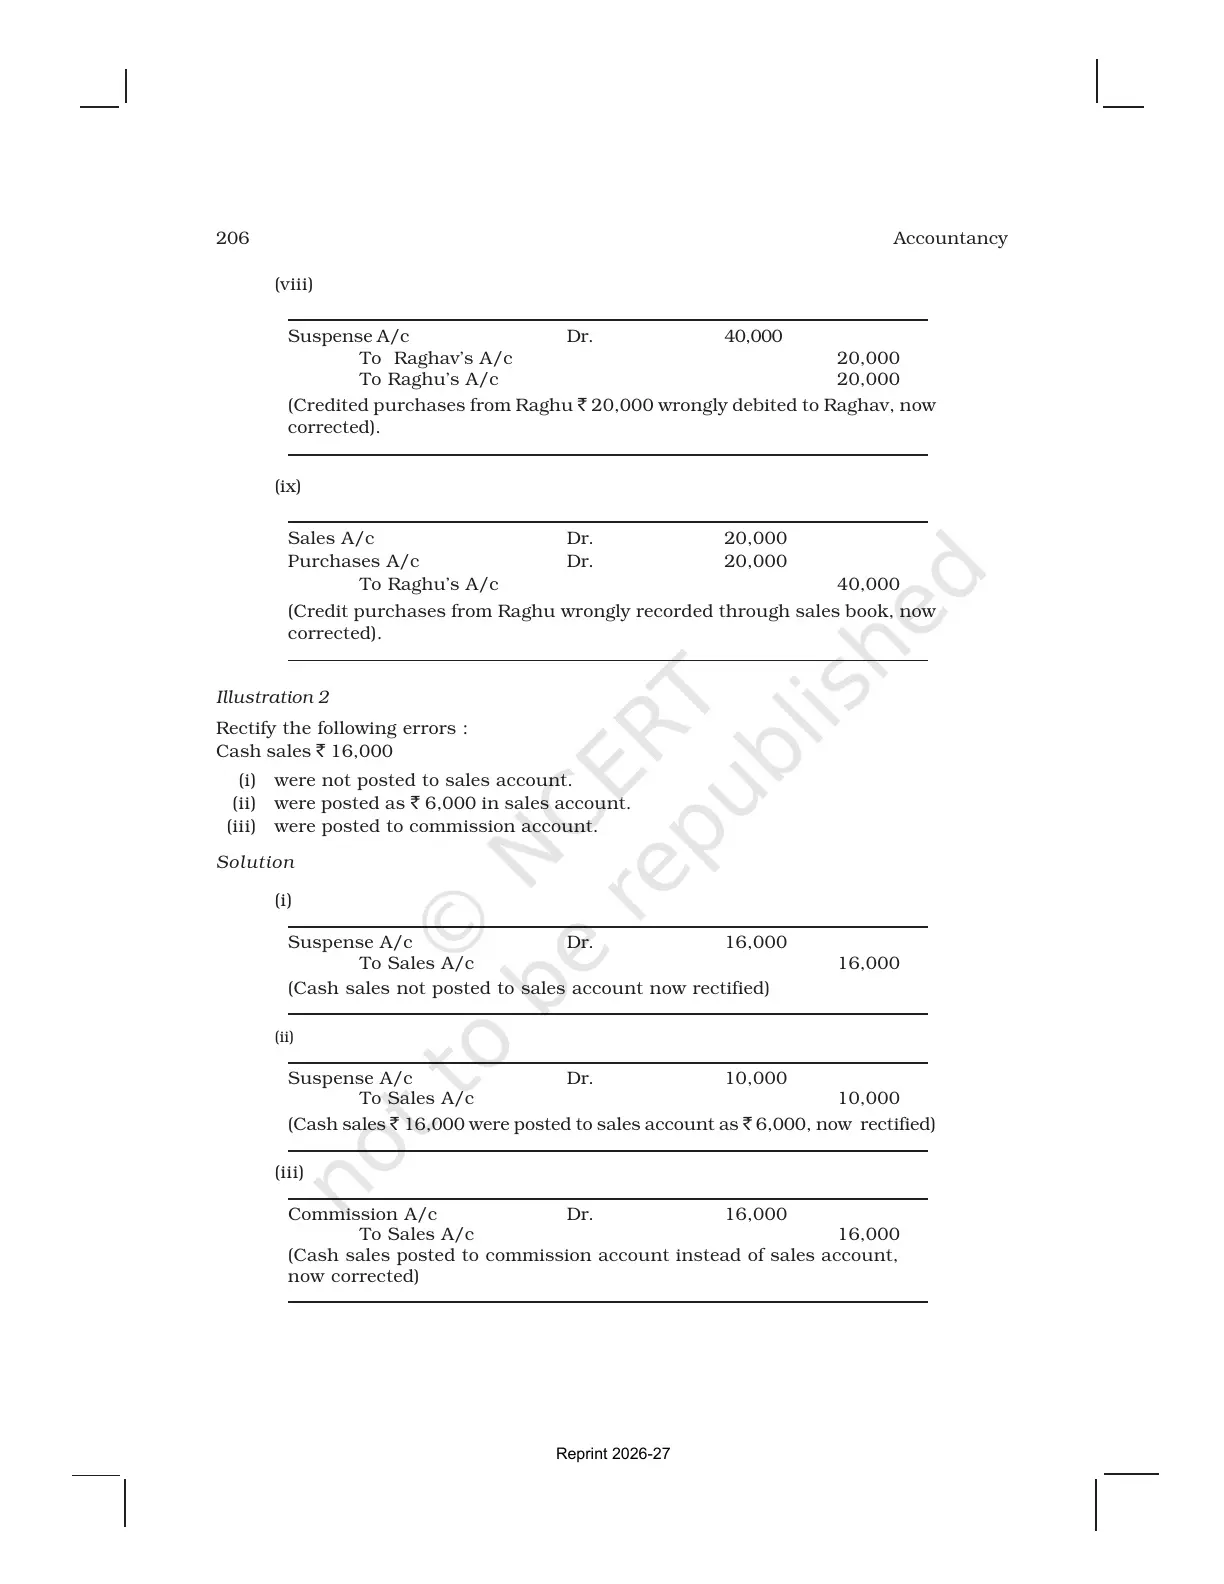
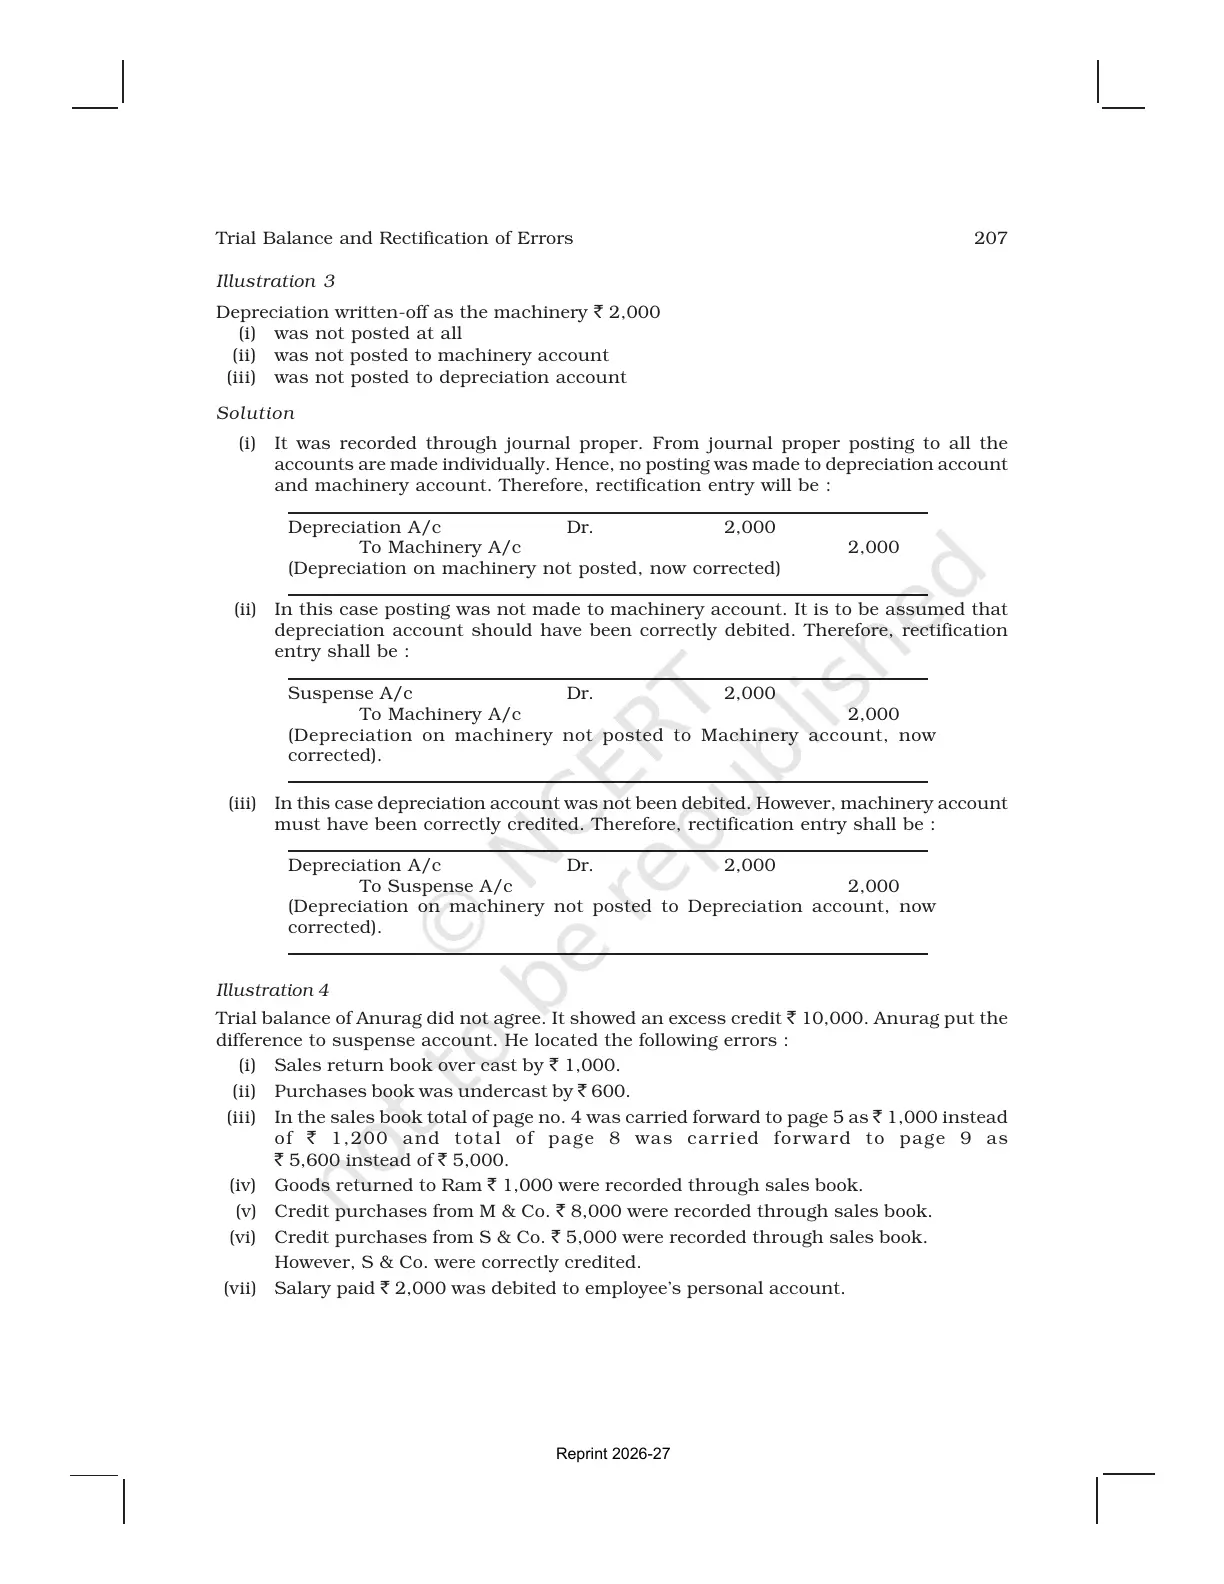
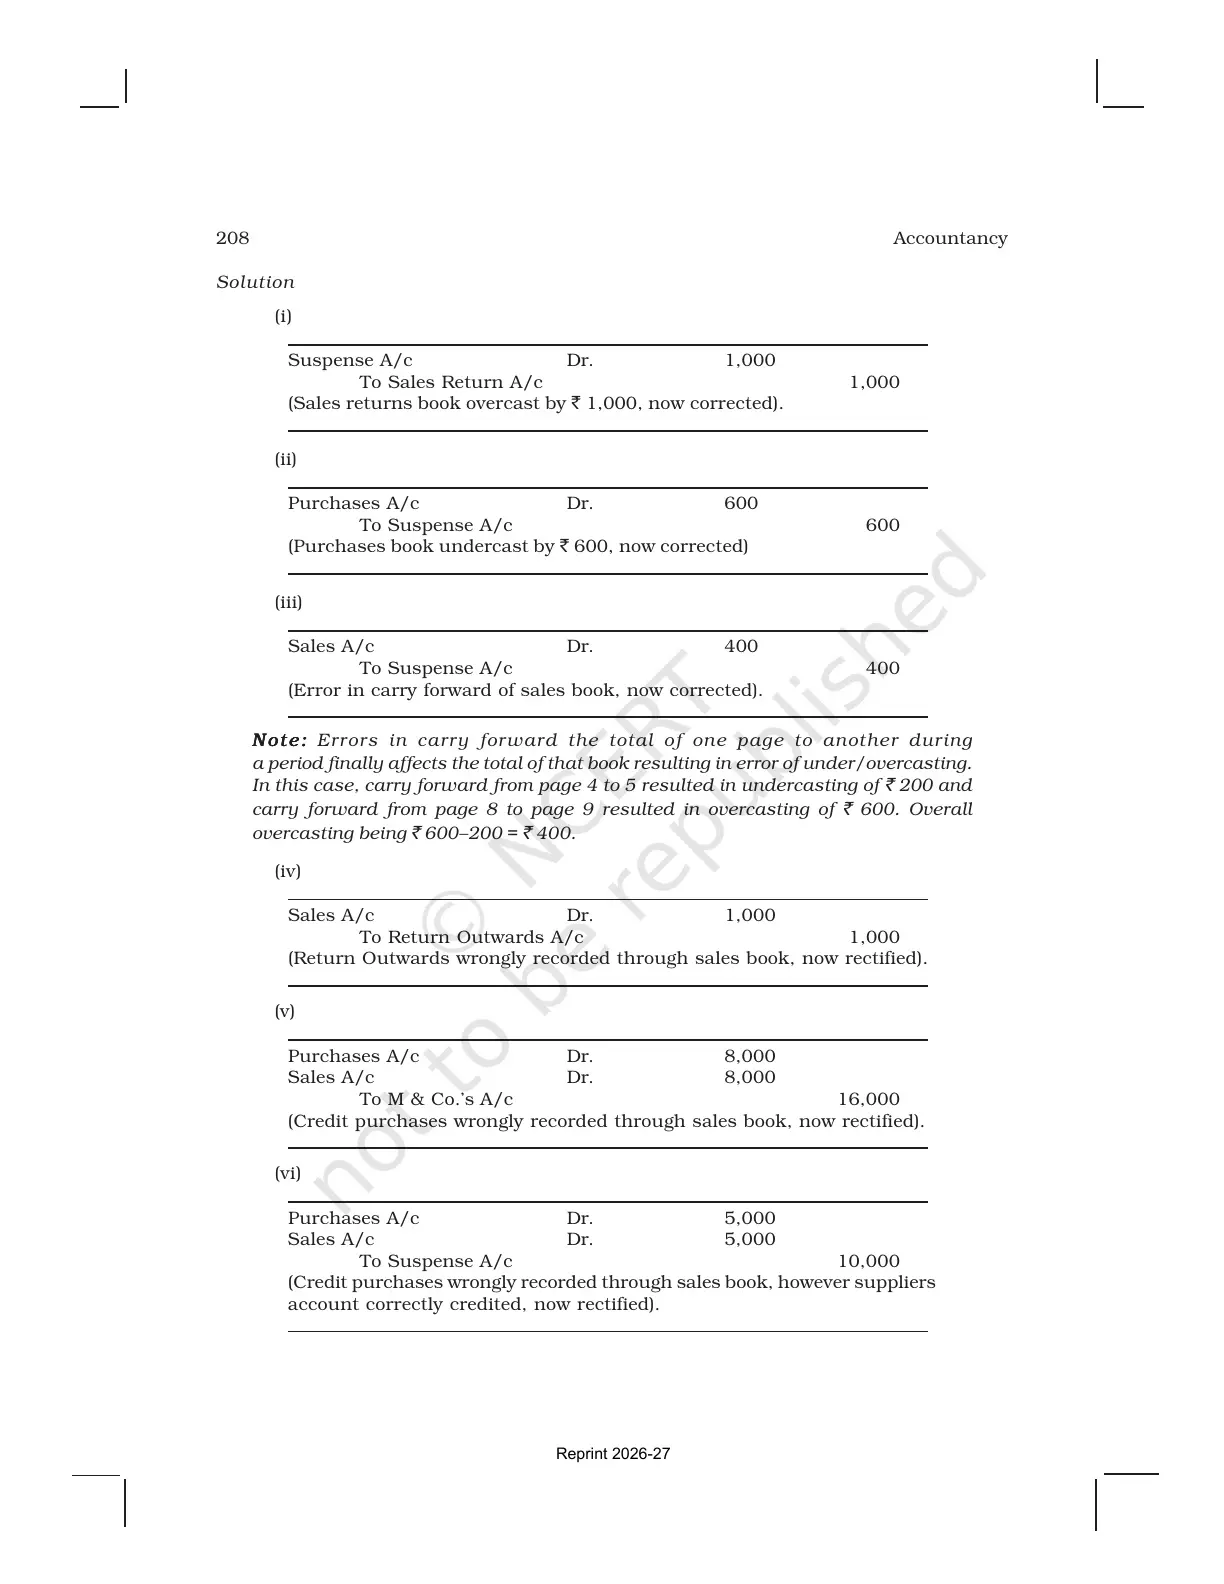
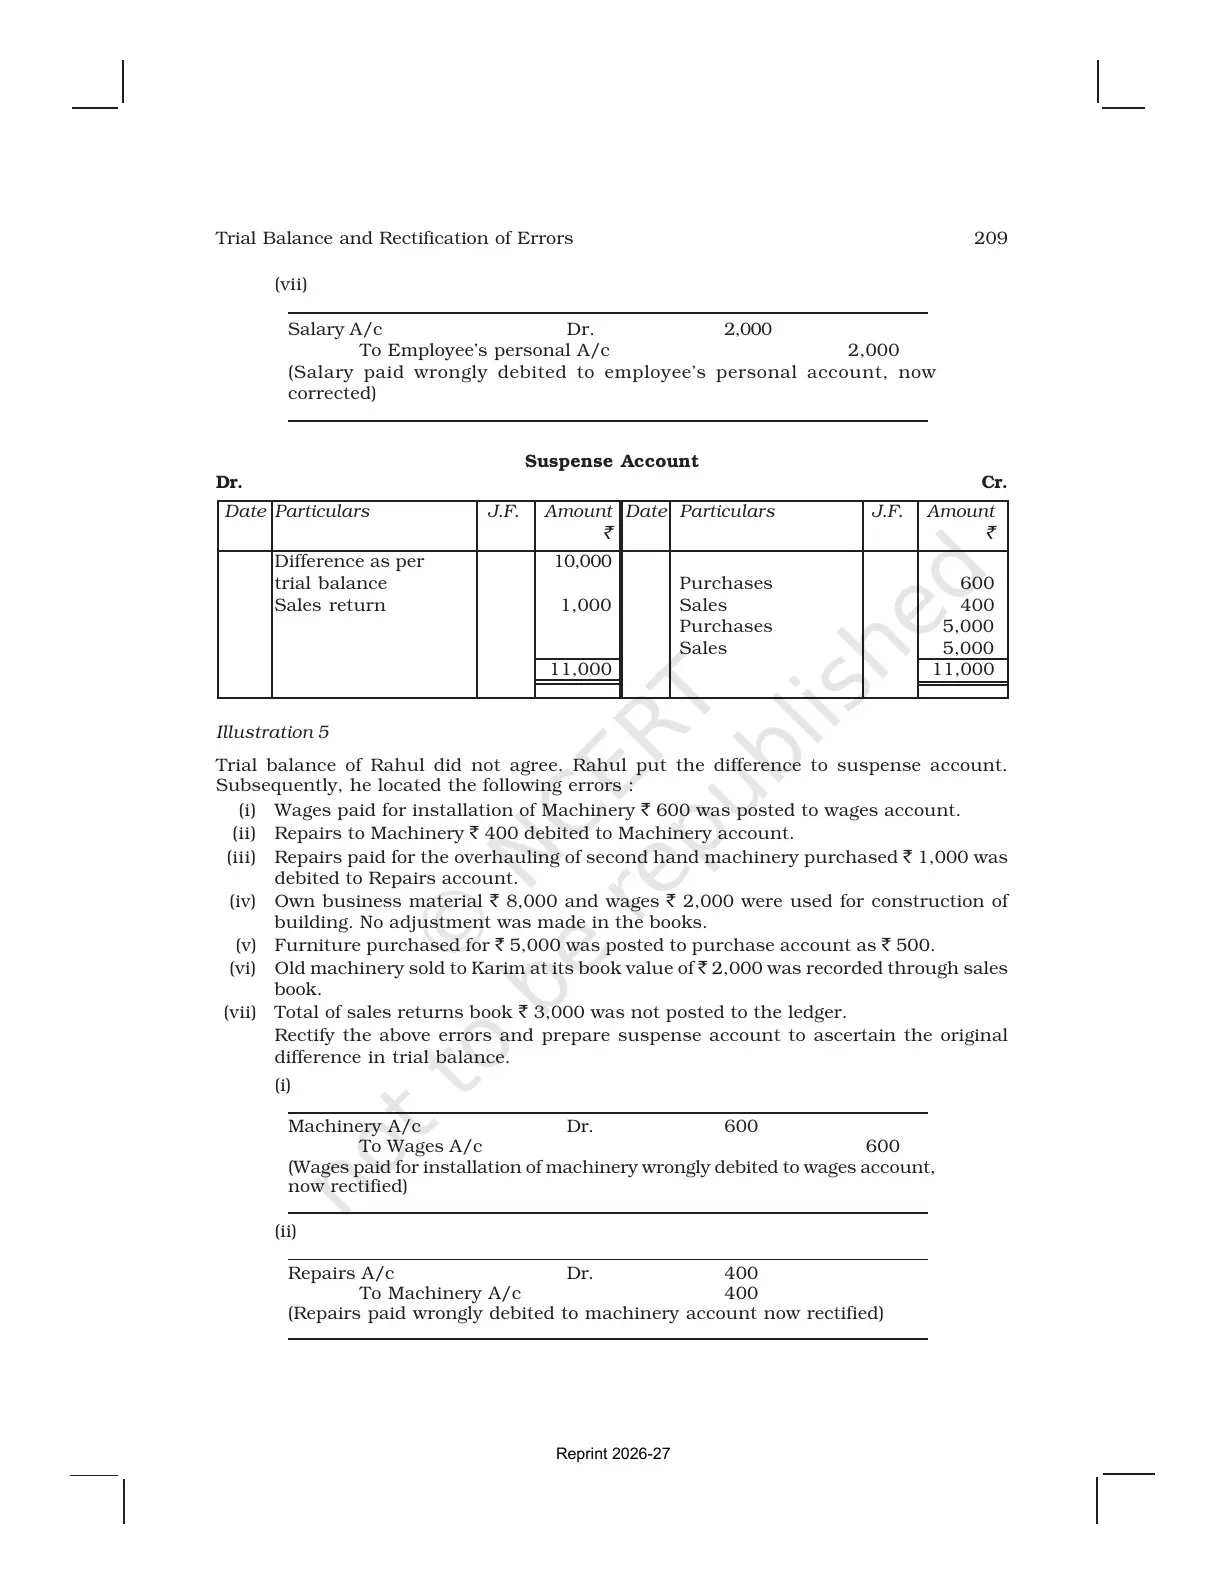
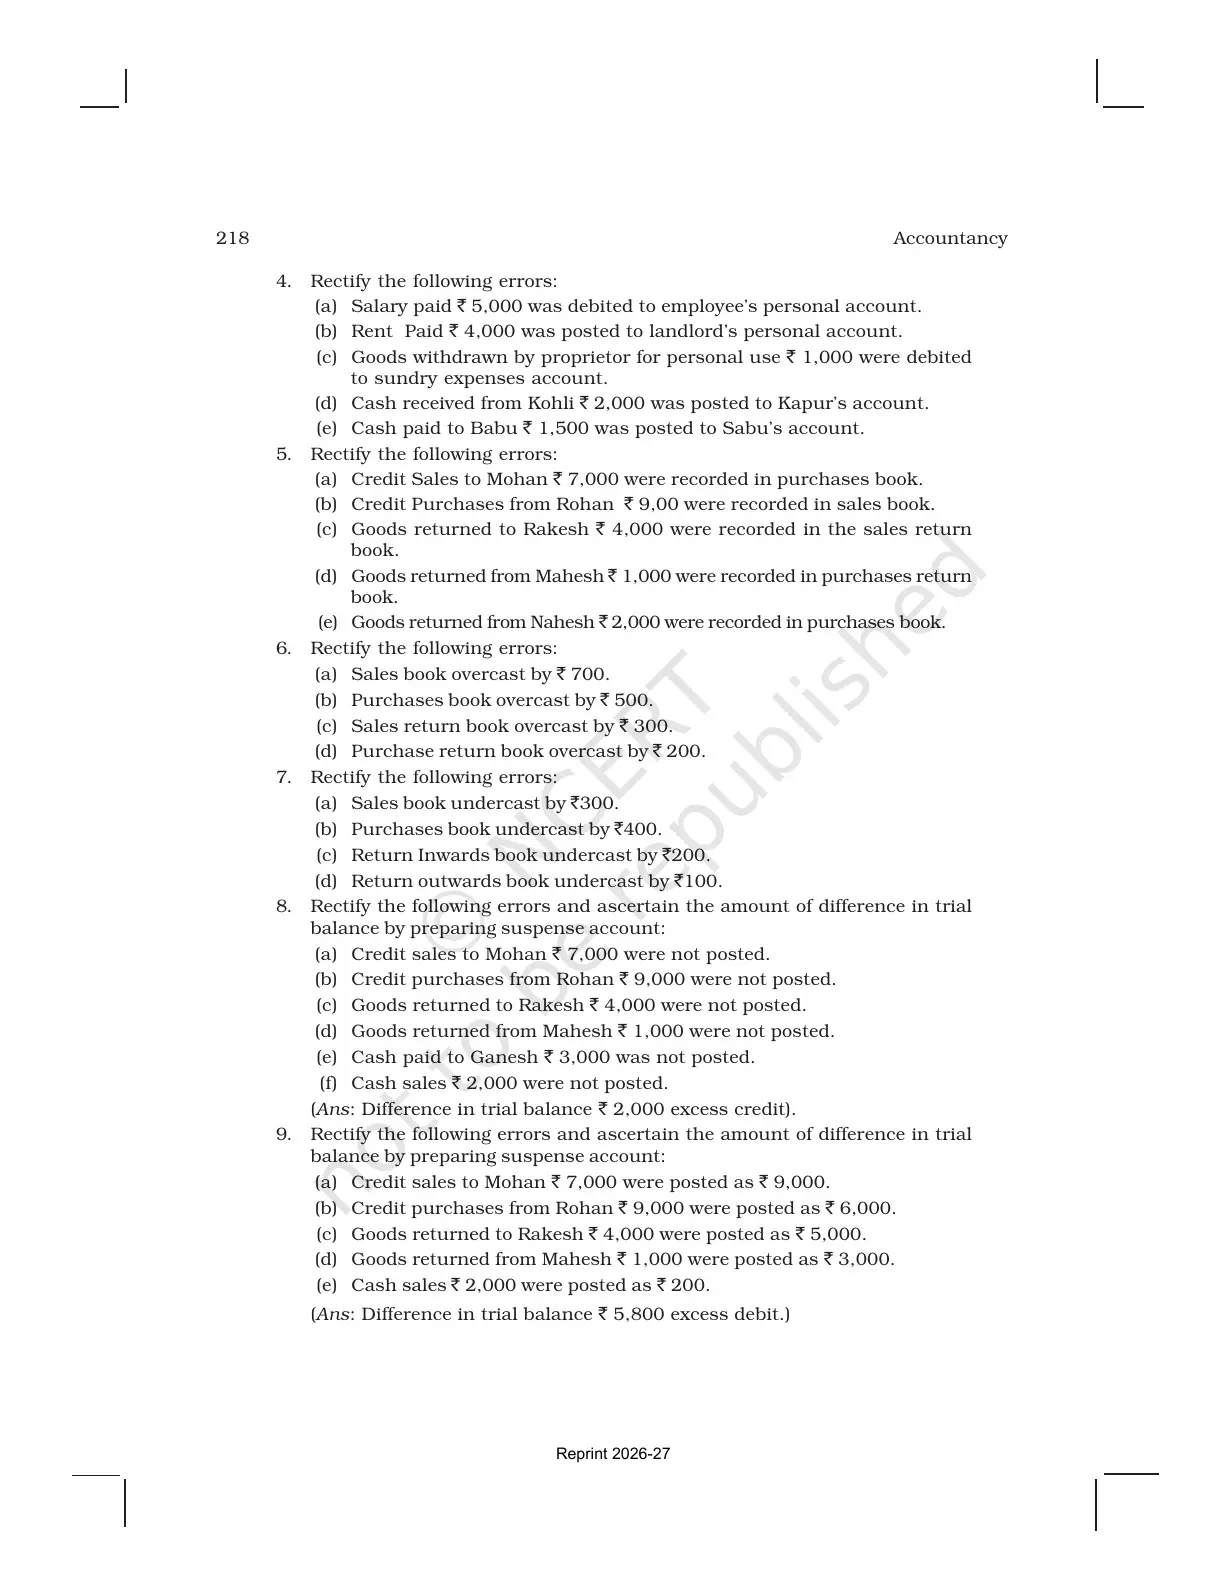
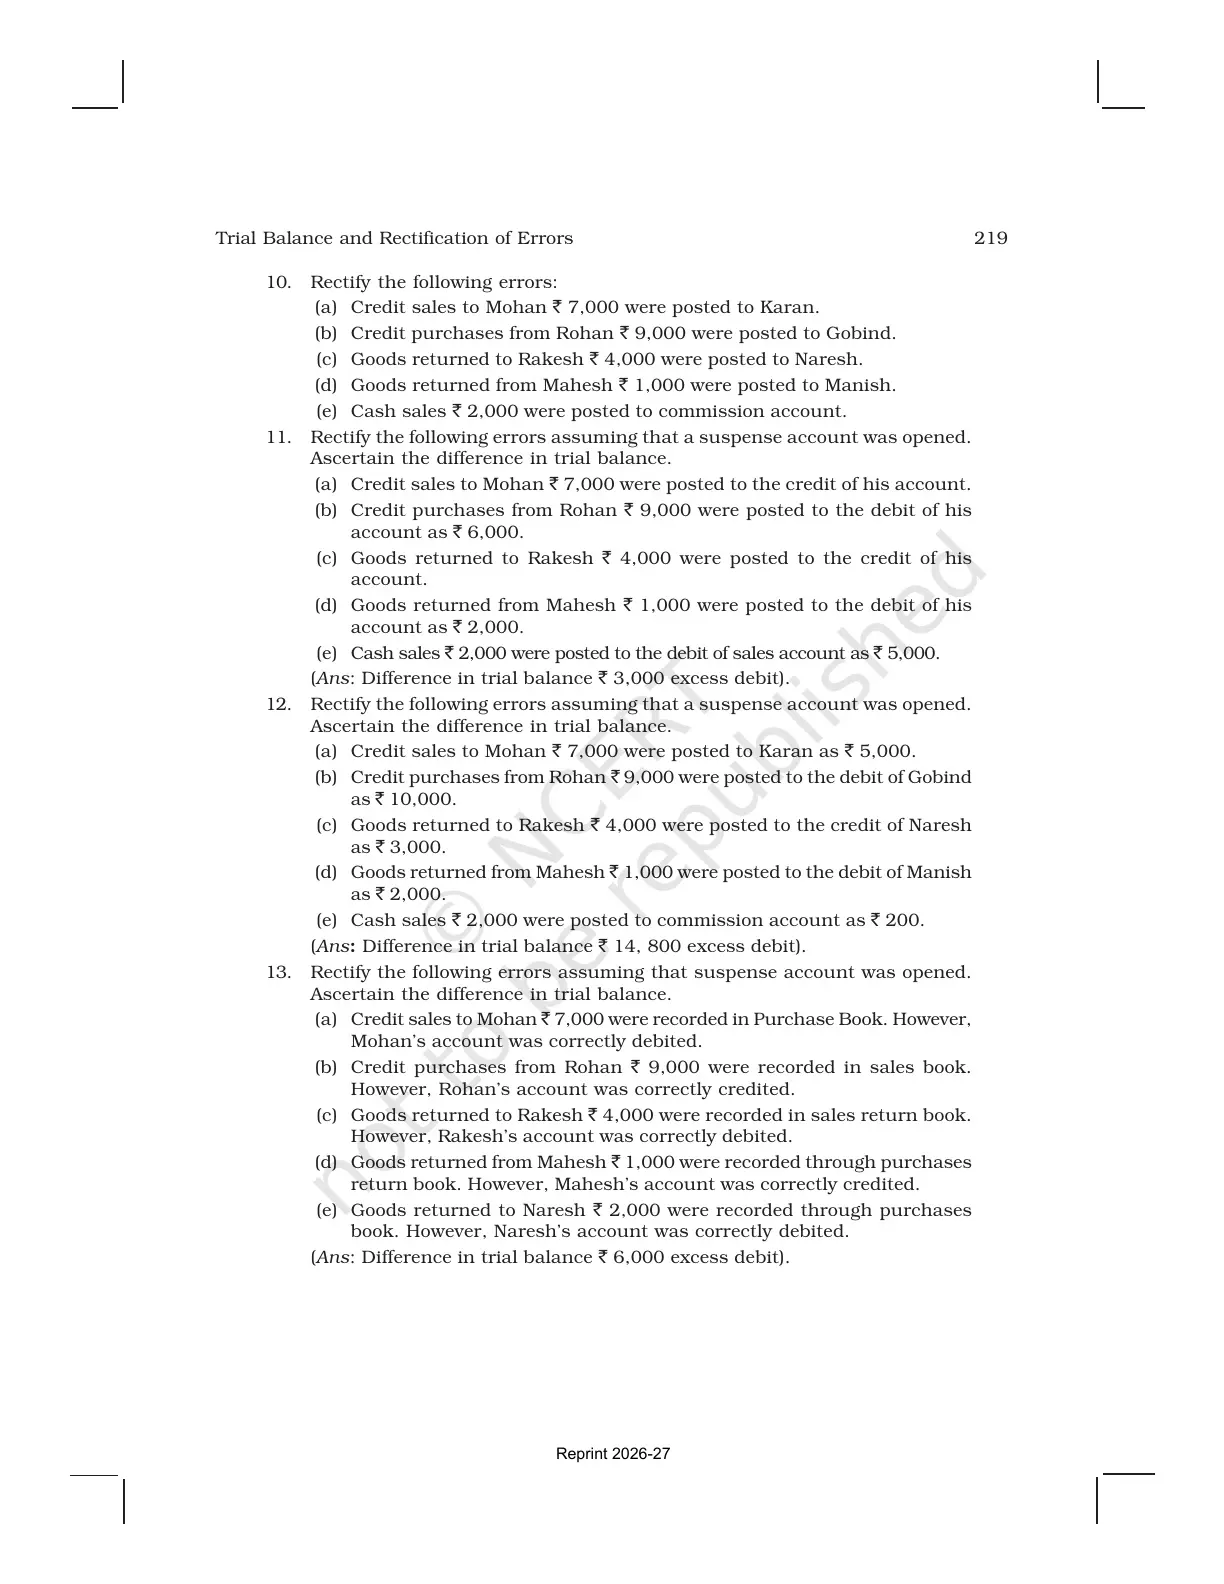
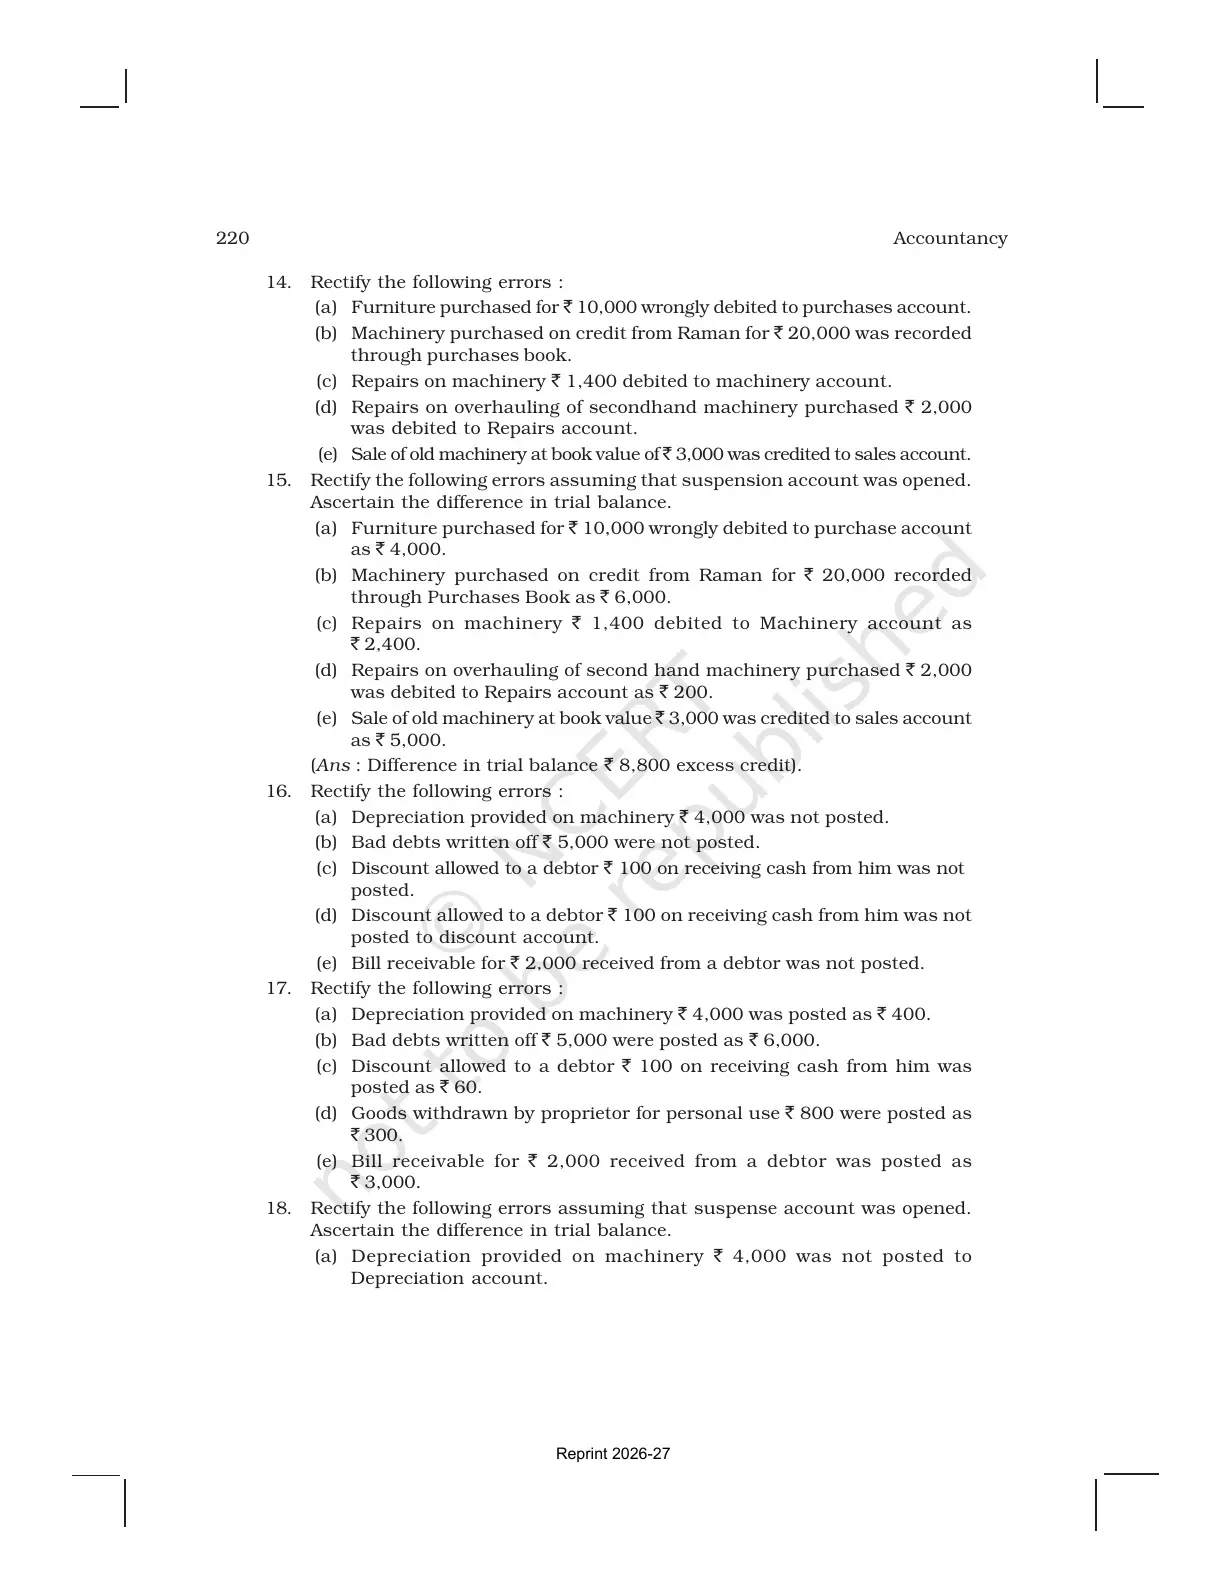
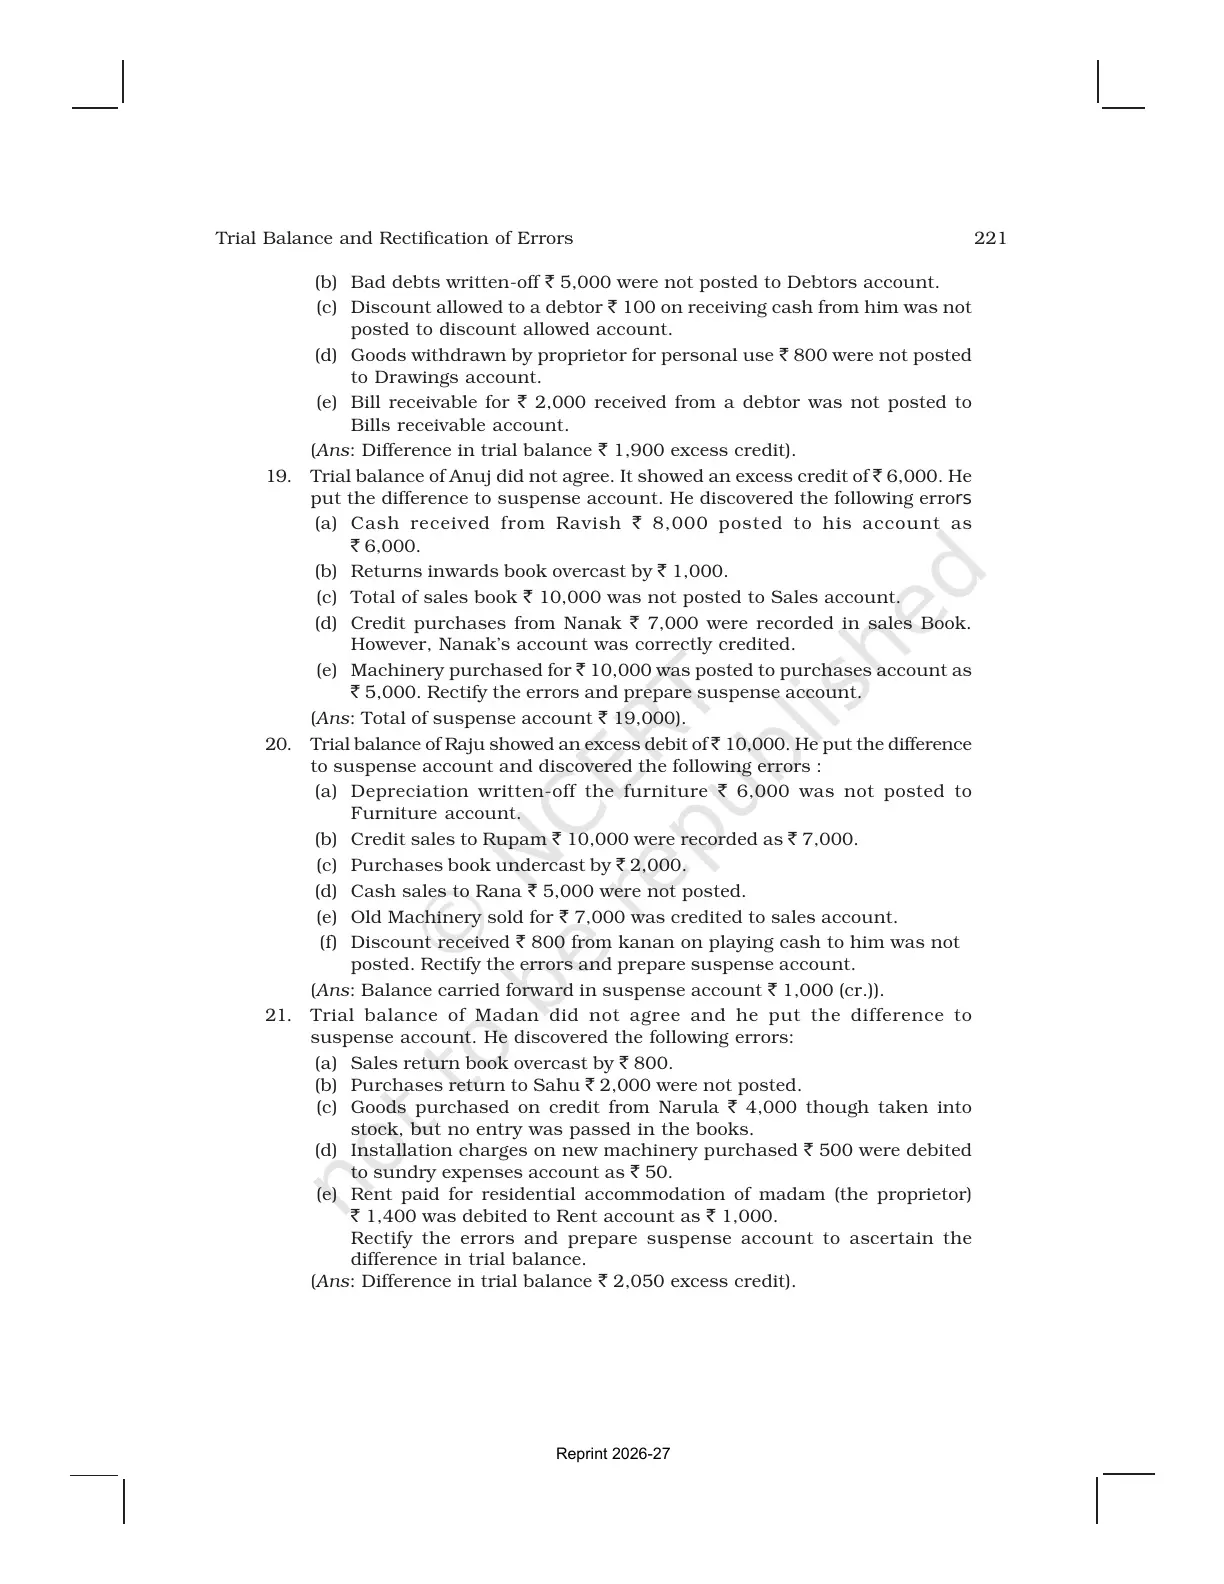
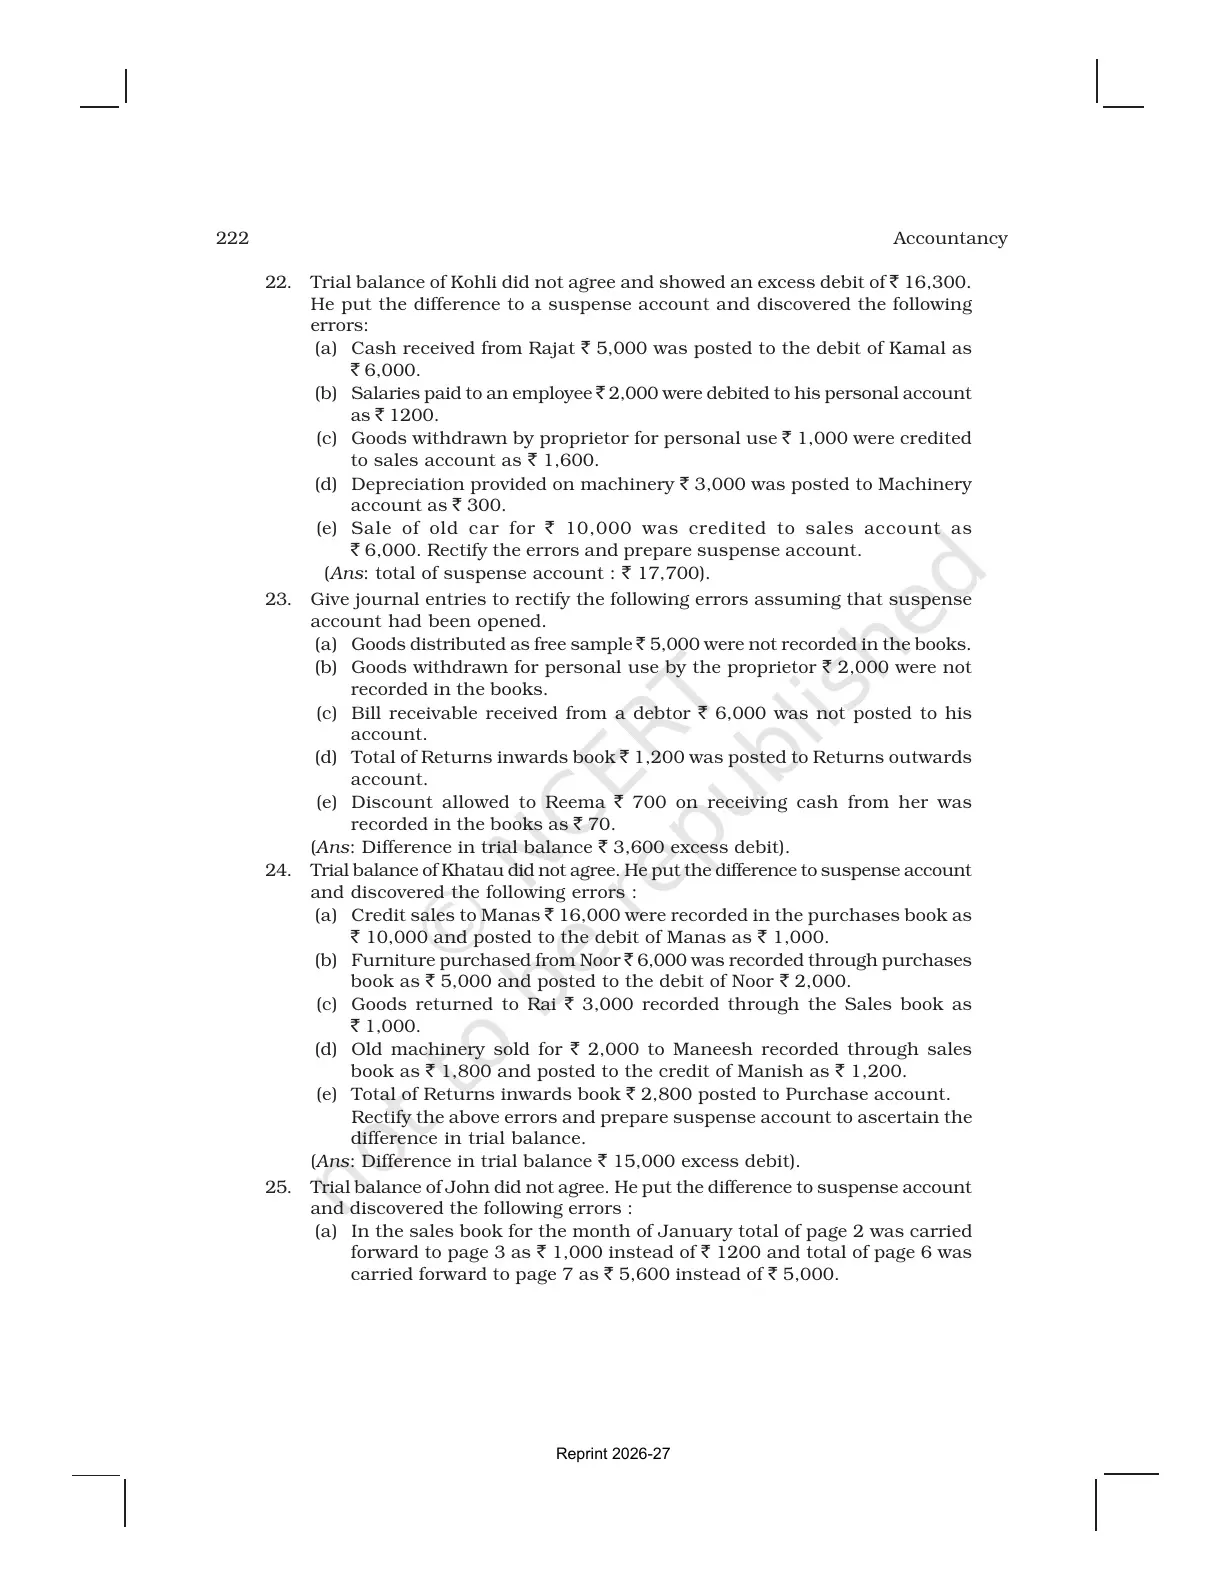
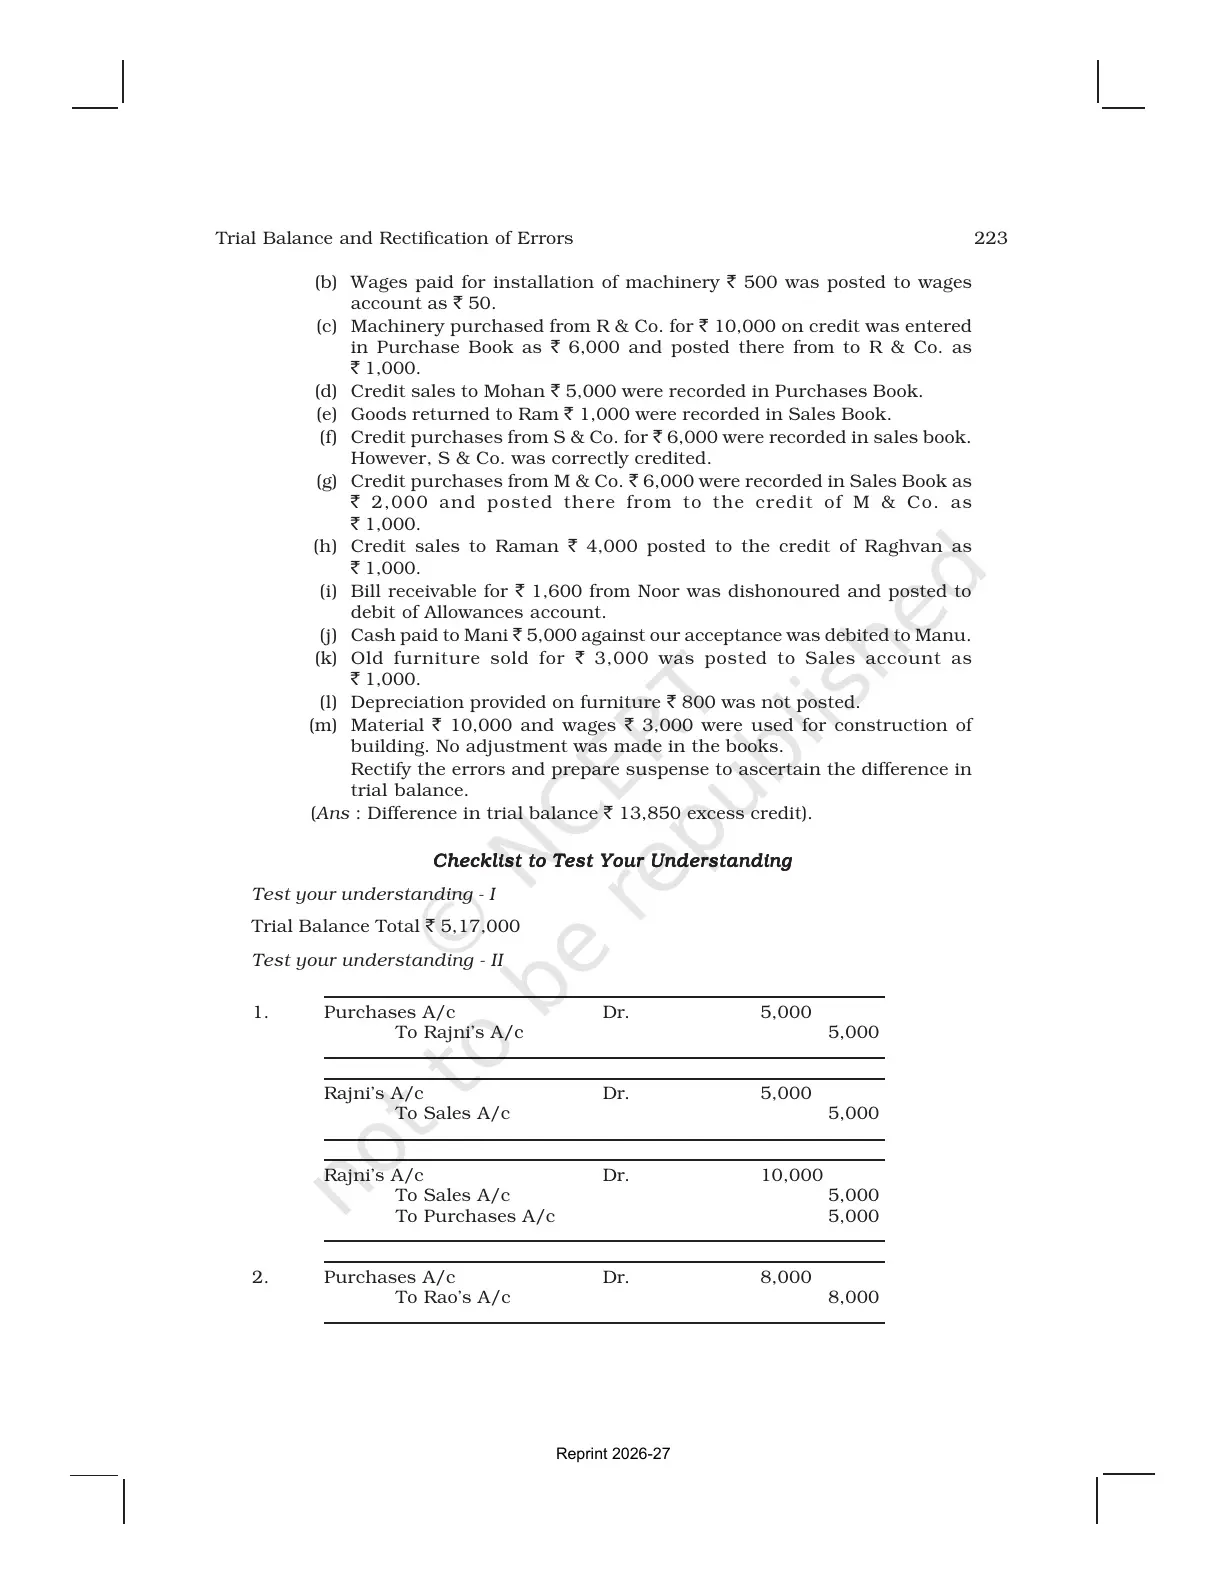
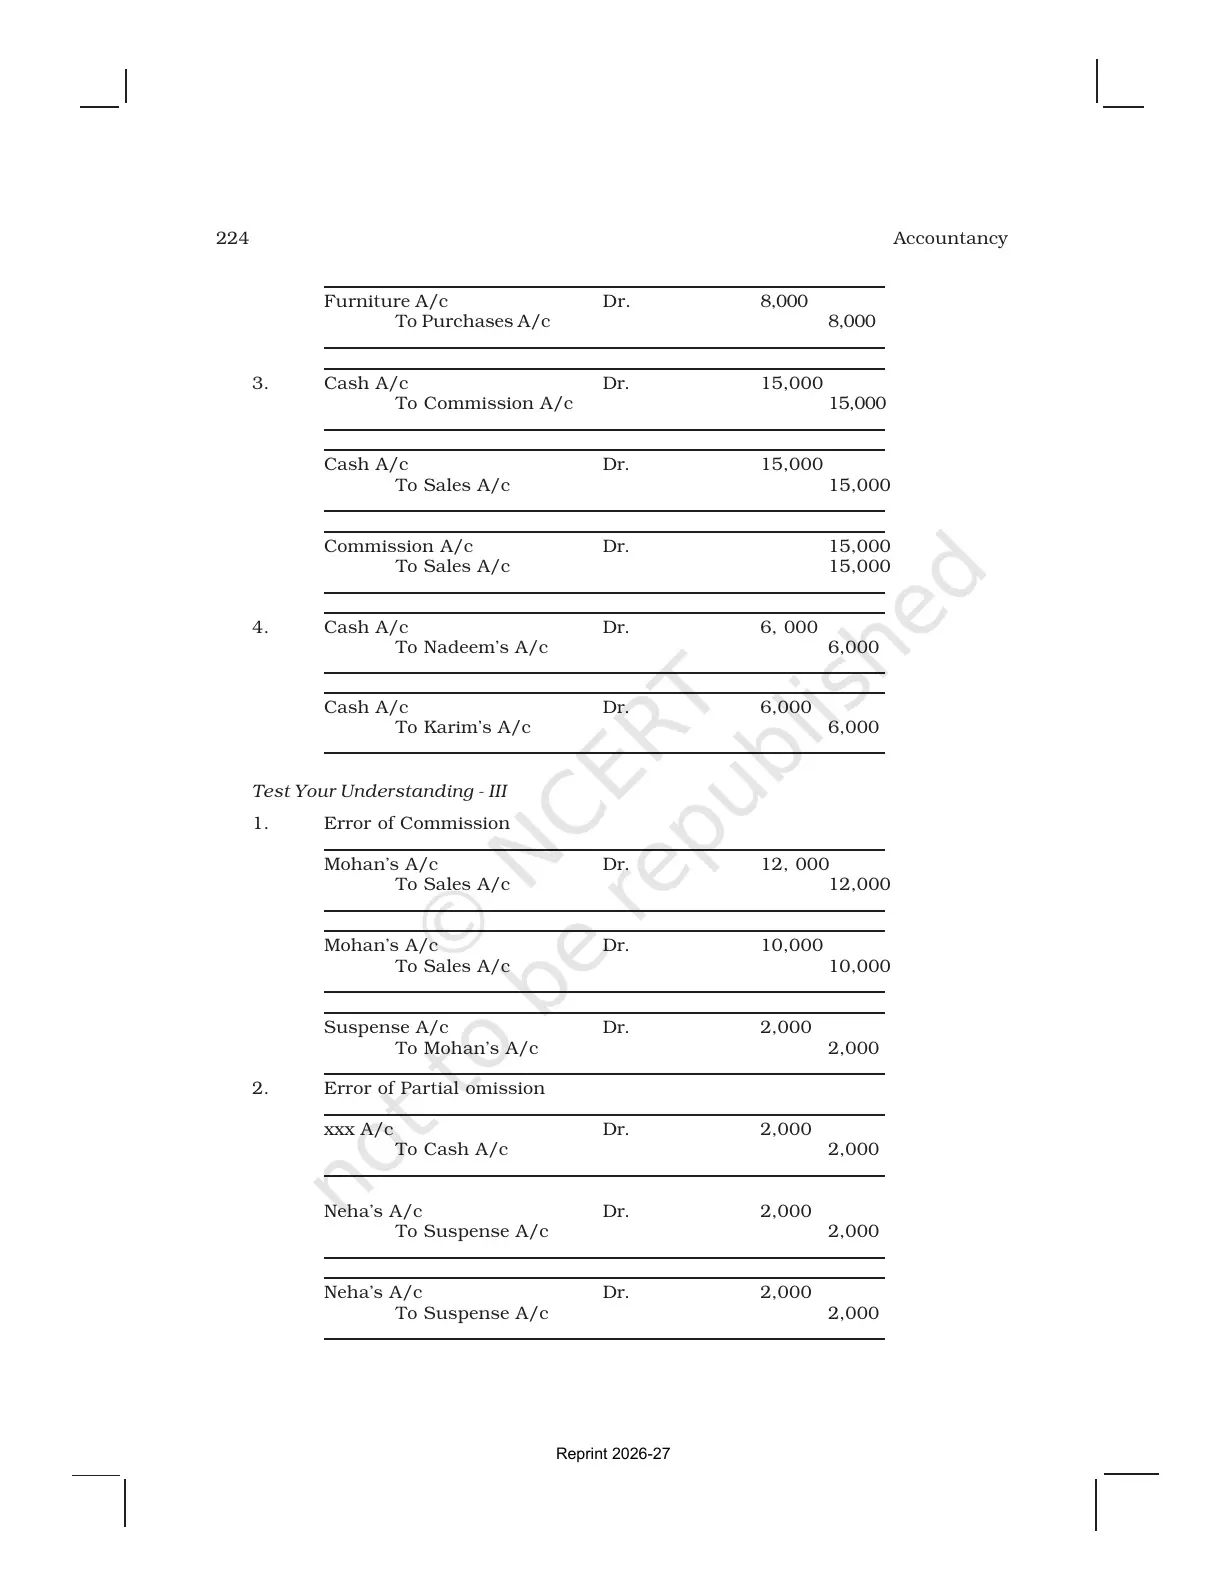
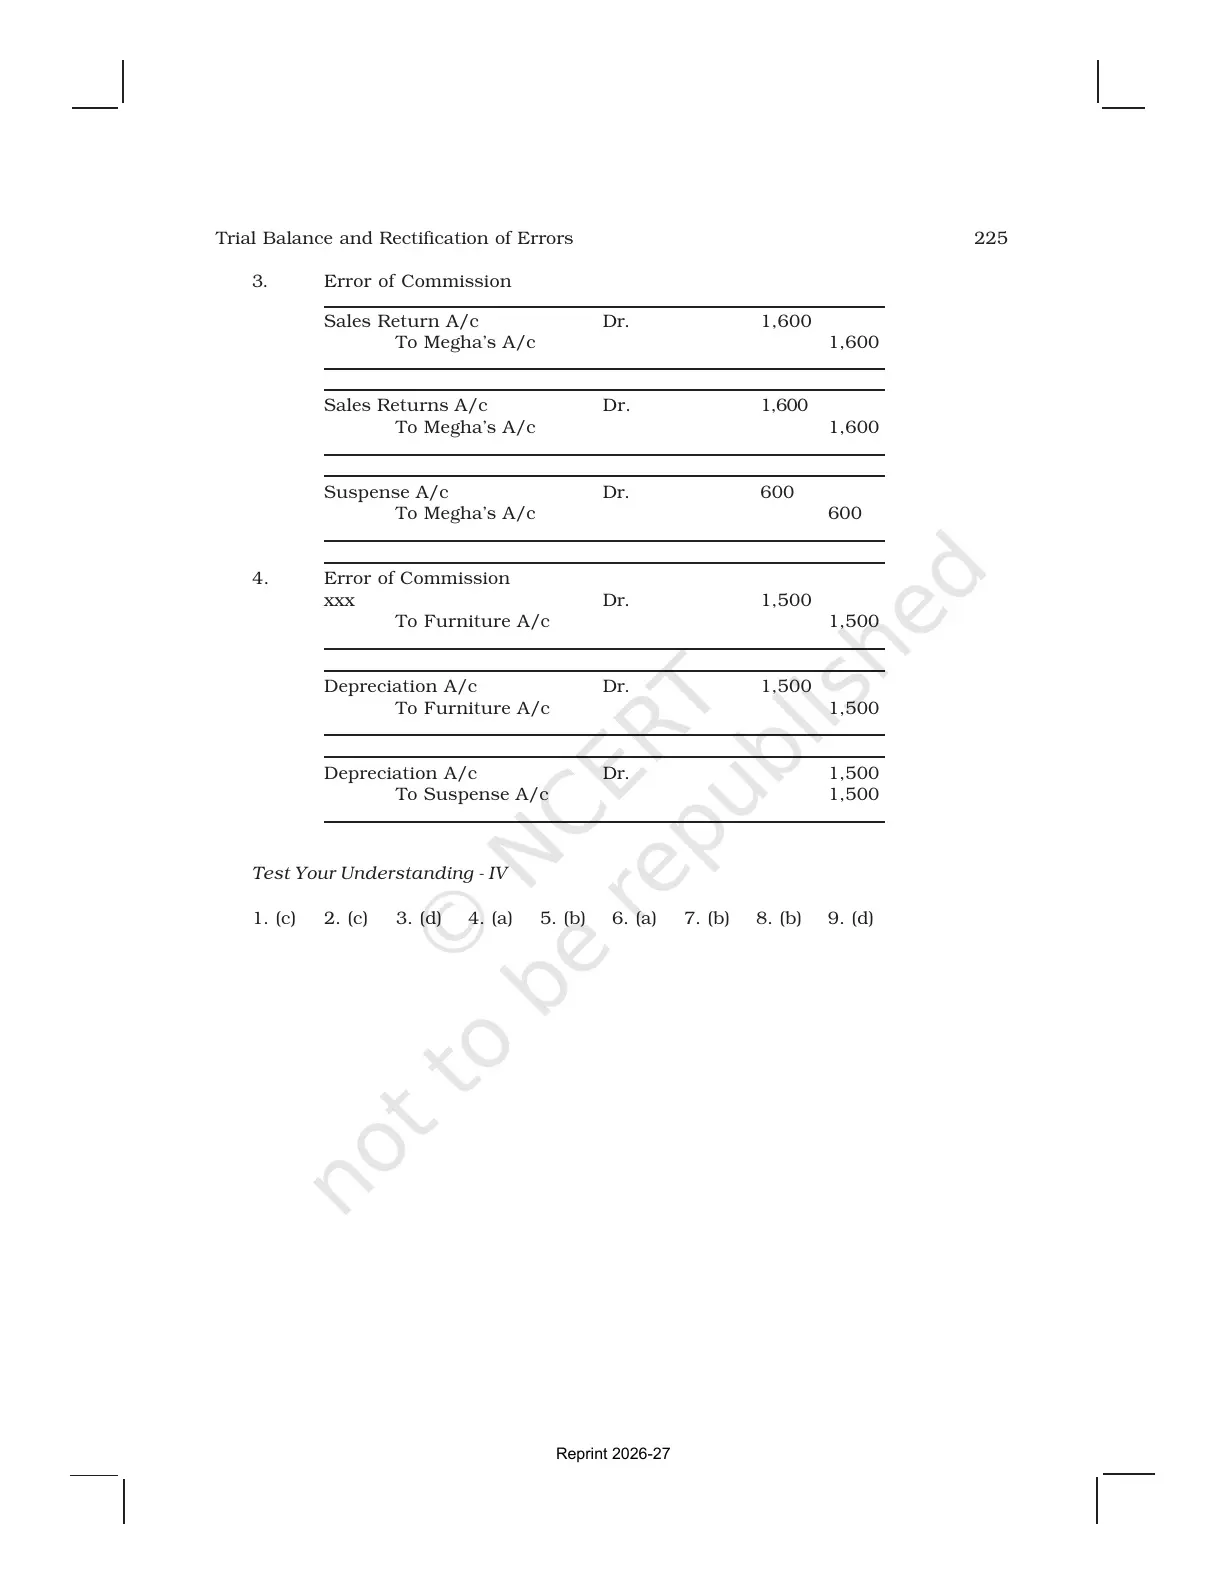
This Class 11 Accountancy NCERT Book PDF follows the 2026-27 NCERT reprint and helps students check ledger accuracy before final accounts.
Trial Balance and Rectification of Errors Concepts Covered in the NCERT PDF
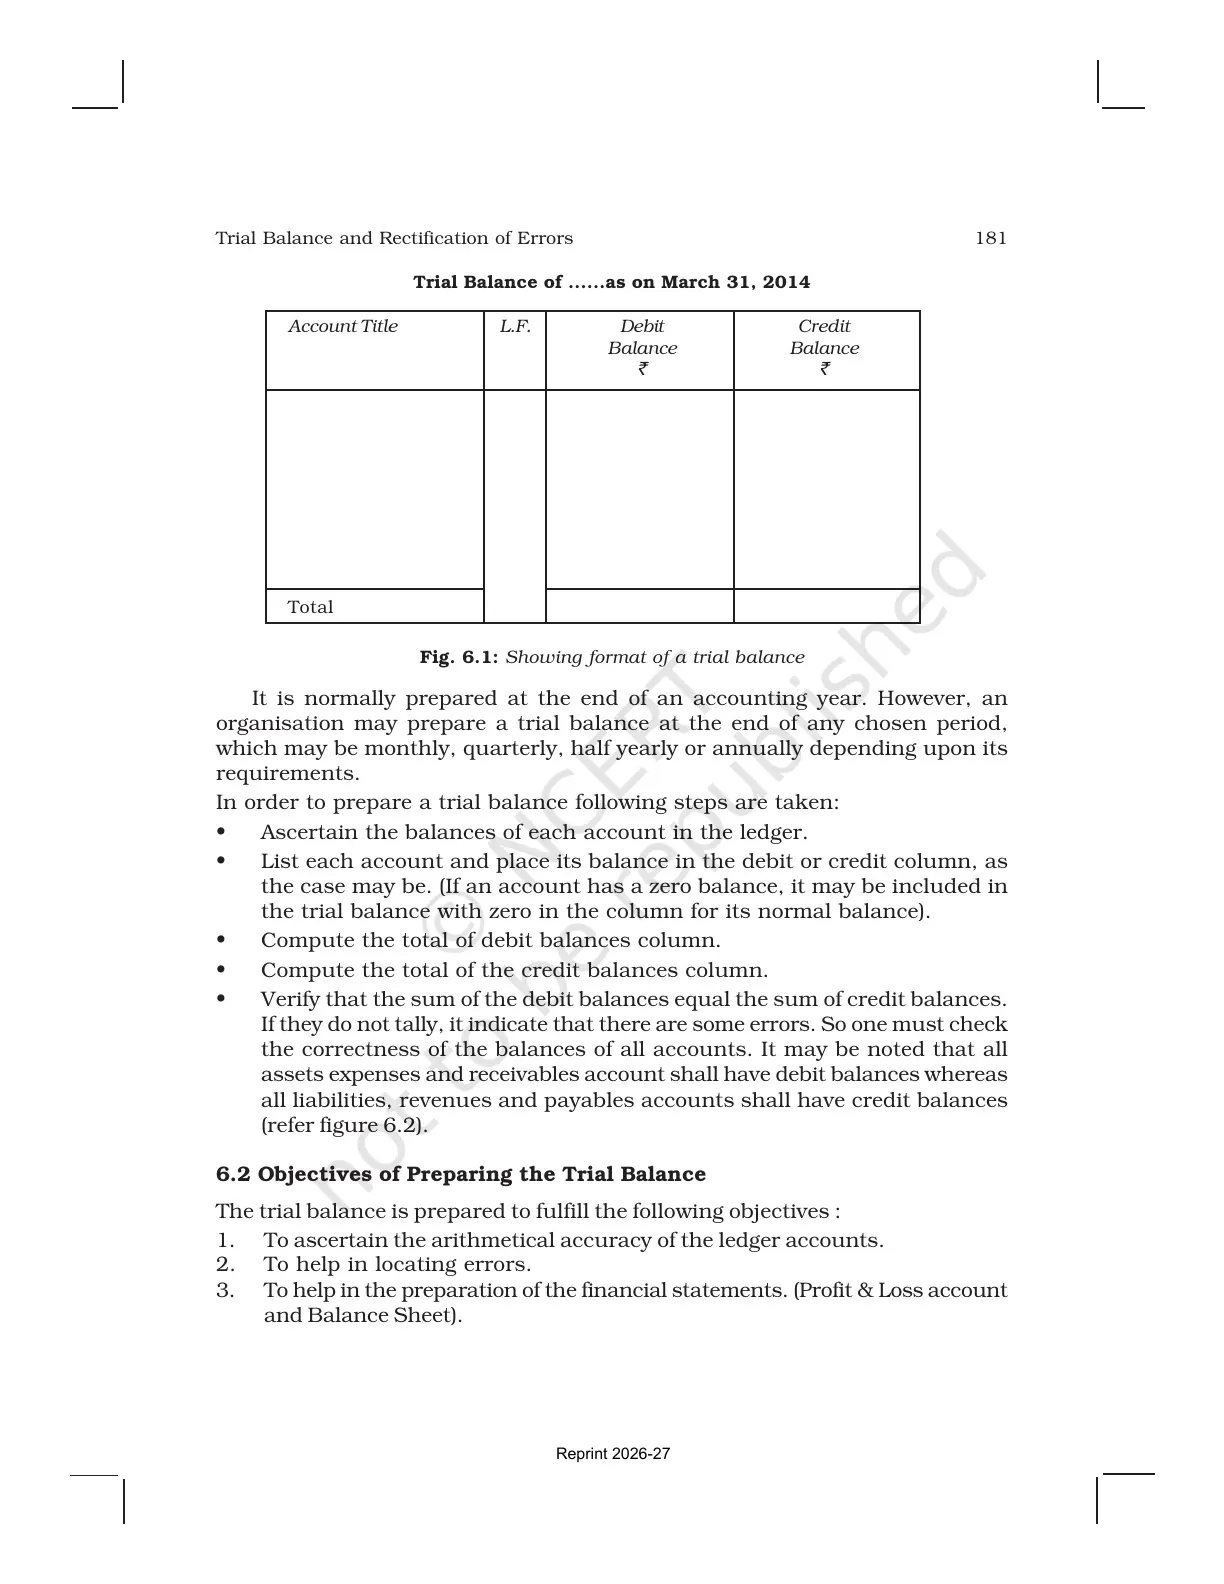
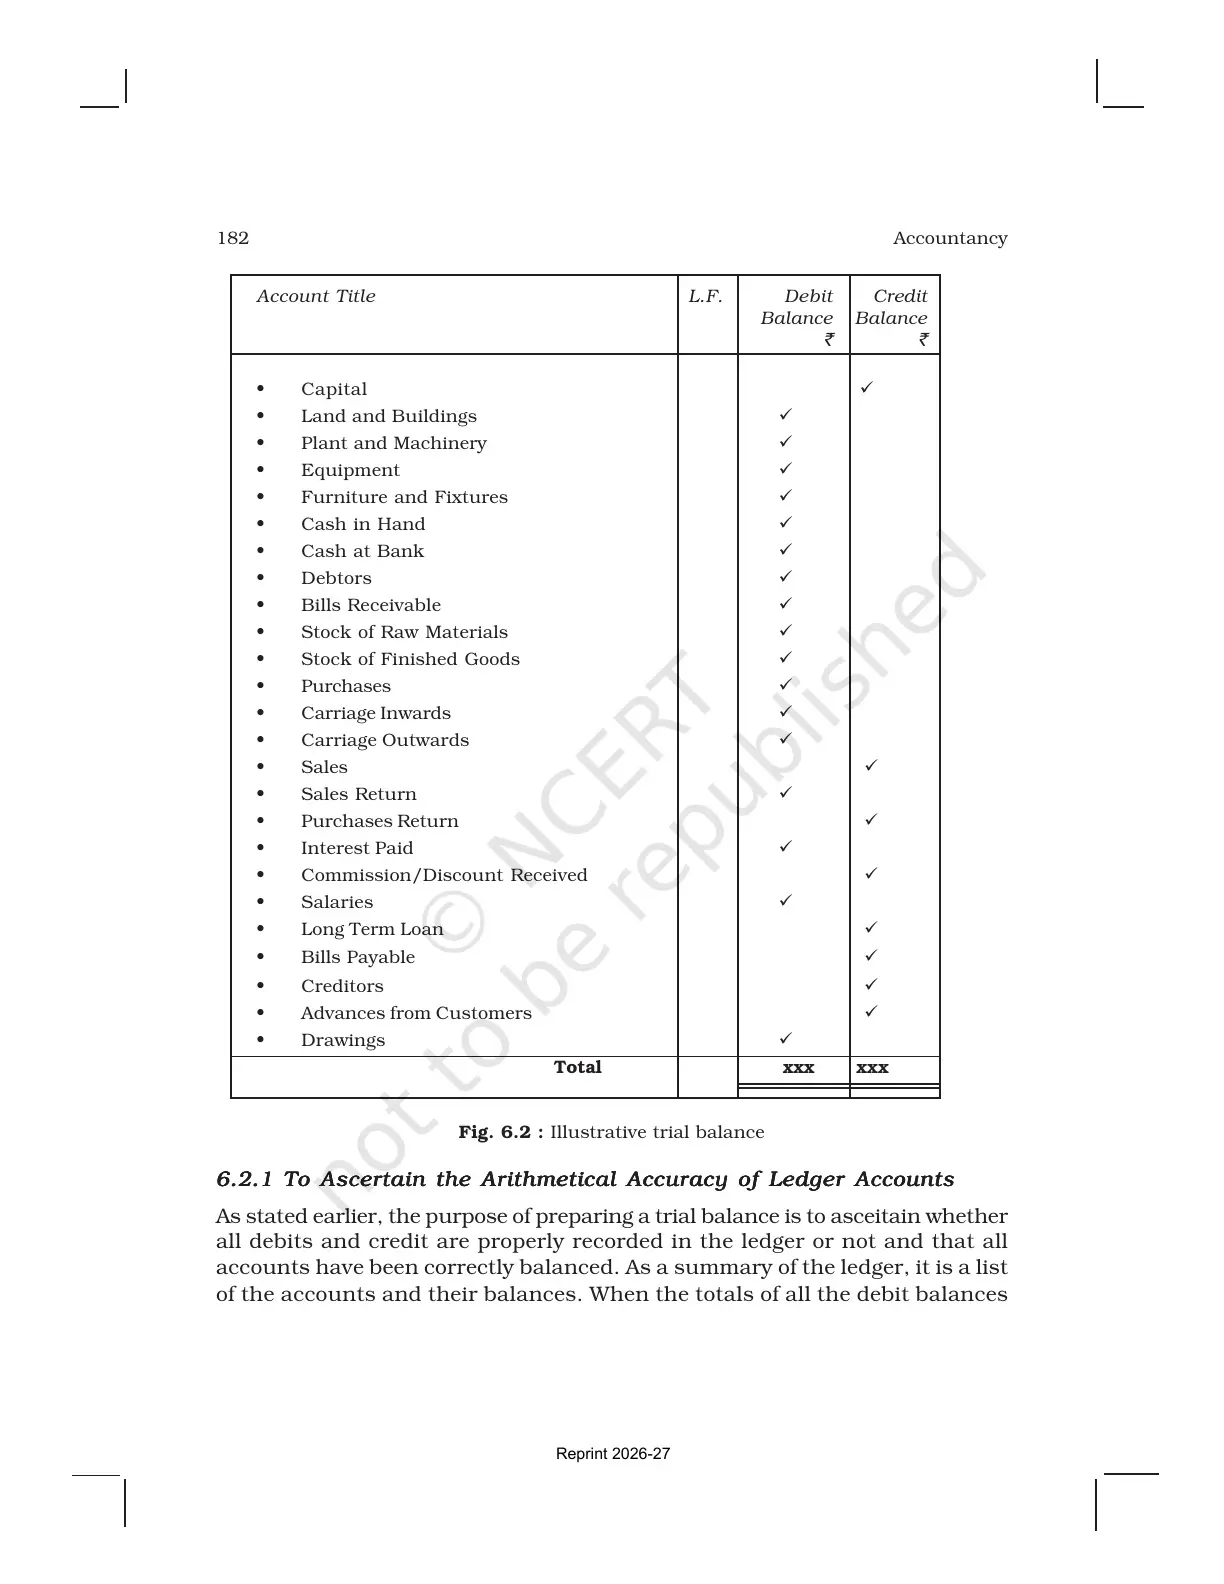
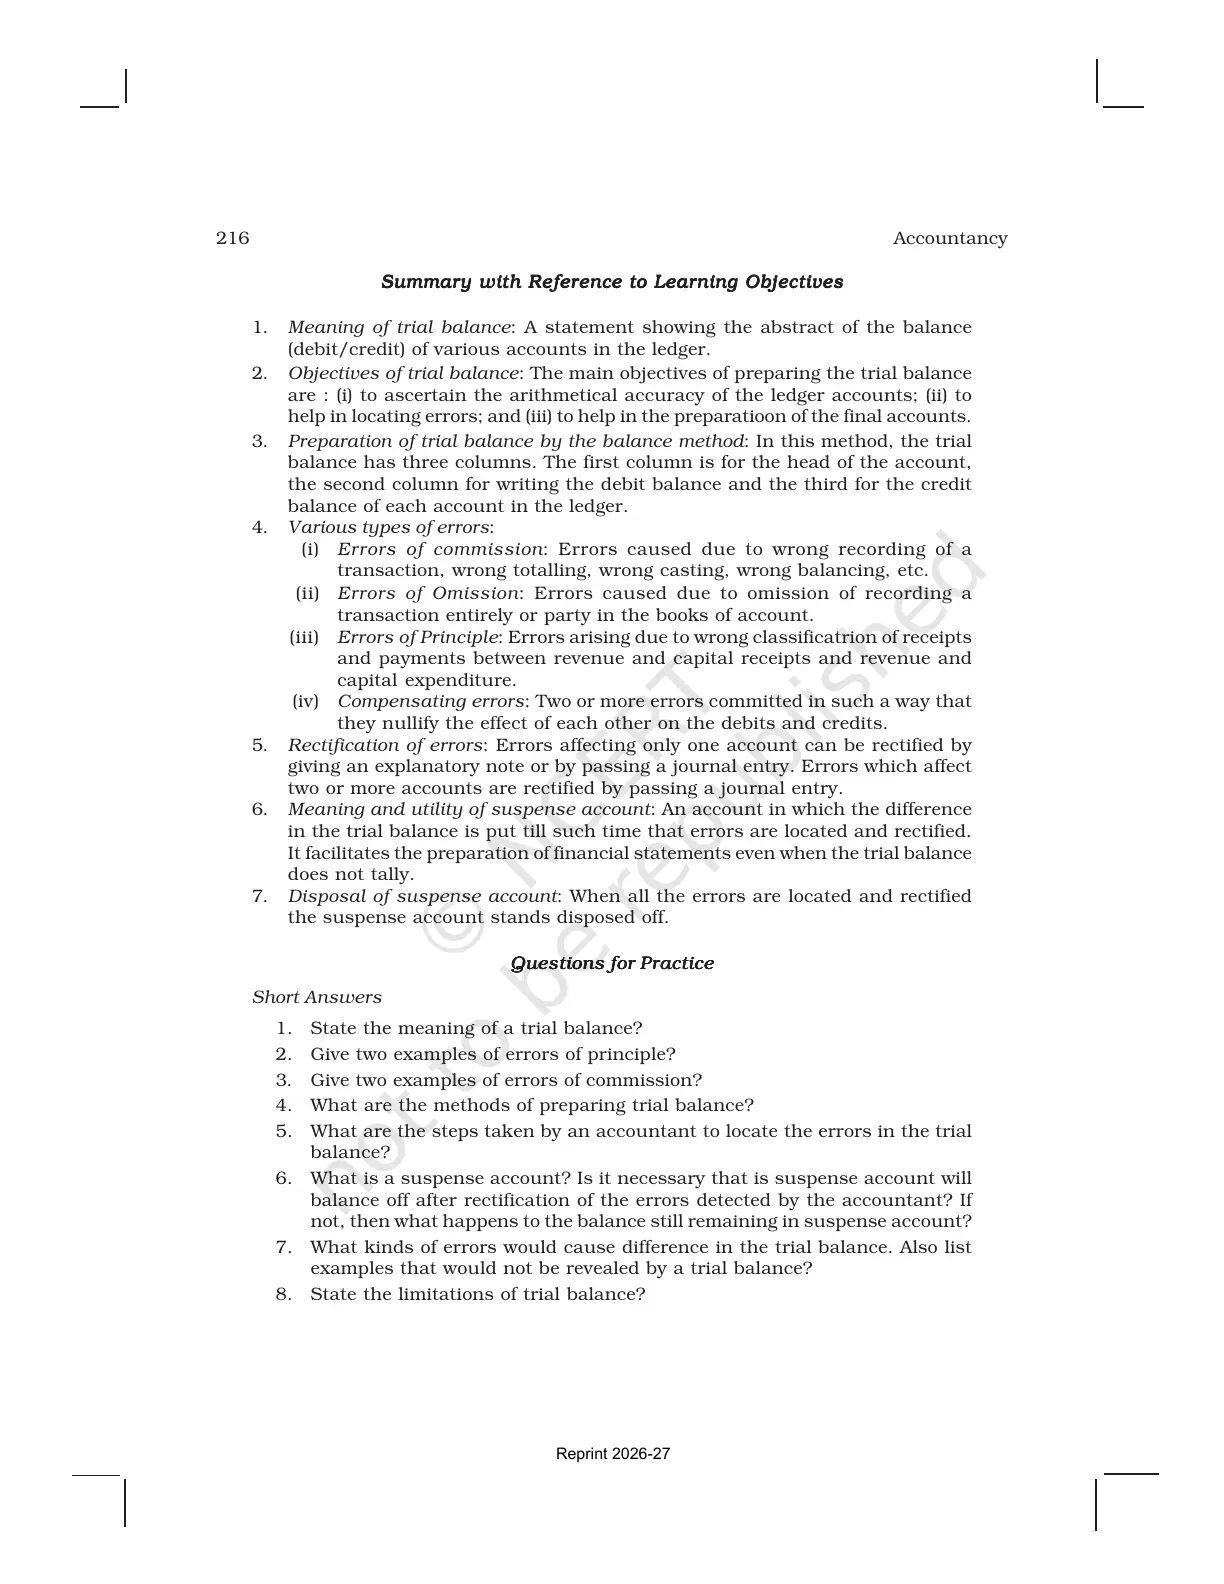
This chapter starts with the trial balance. It checks whether the total debit balances match the total credit balances.
A trial balance checks arithmetical accuracy, but it does not prove that every entry is correct.
| Concept | What it means | Why it matters |
|---|---|---|
| Trial Balance | List of ledger balances | Checks debit and credit total agreement |
| Suspense Account | Temporary account for disagreement | Used until the error is found |
| One-sided Error | Error affecting one account side | Usually changes the trial balance total |
| Two-sided Error | Error affecting both debit and credit | May not change the trial balance total |
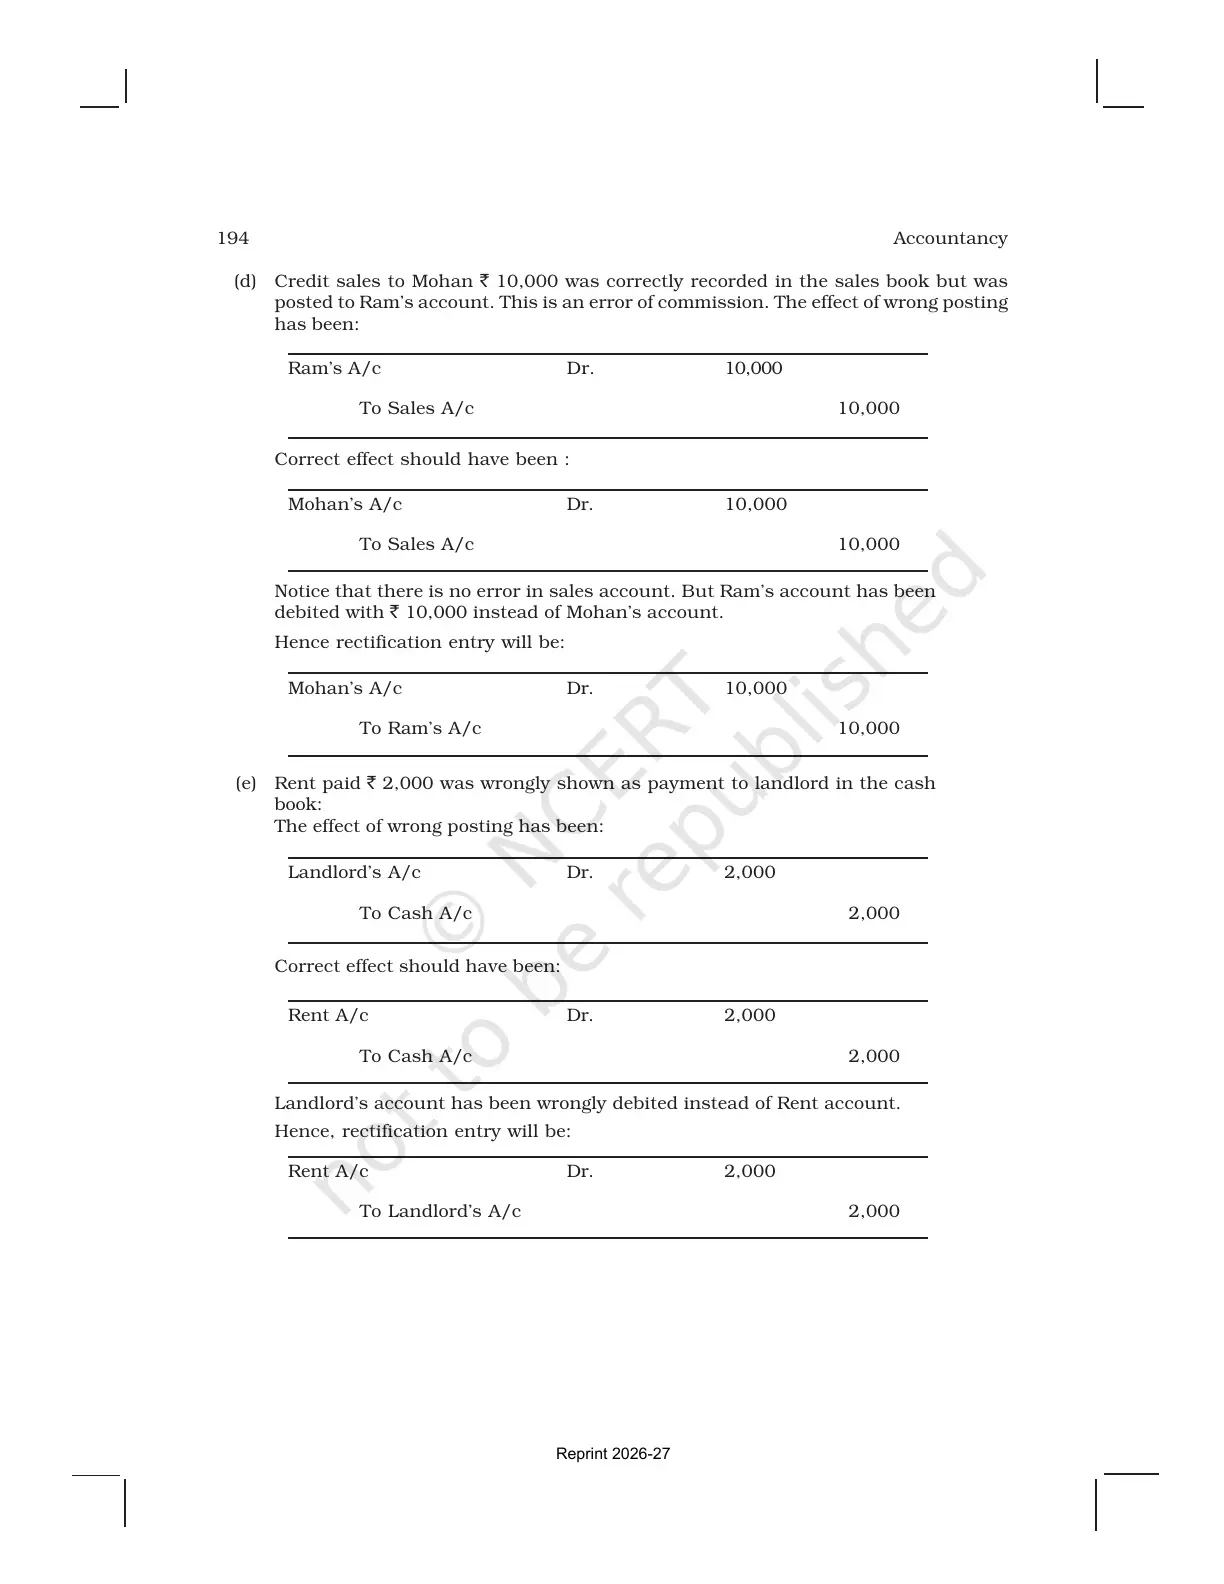
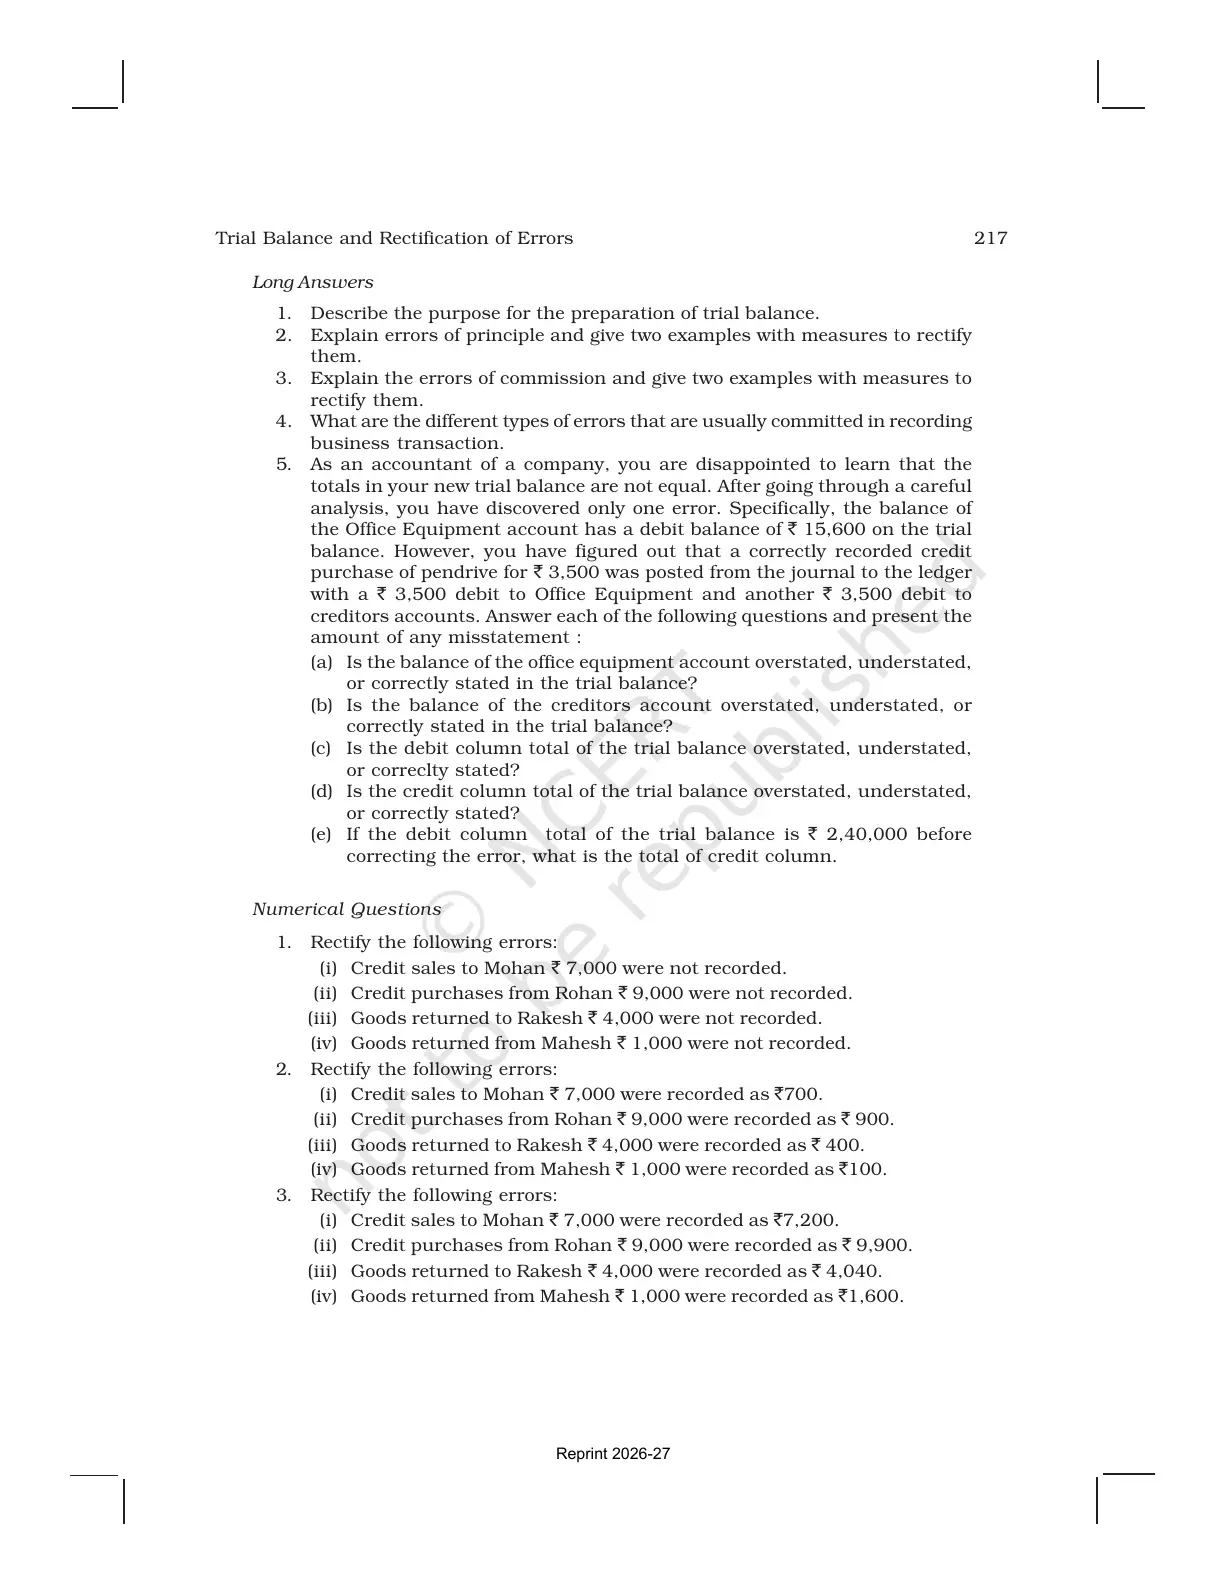
| Rectification Entry | Journal entry used to fix error | Corrects the books before final accounts |
Rectification of Errors Class 11 Video Lesson
Source: Magnet Brains on YouTube
Trial Balance Error Checking Flow for Class 11 Accountancy
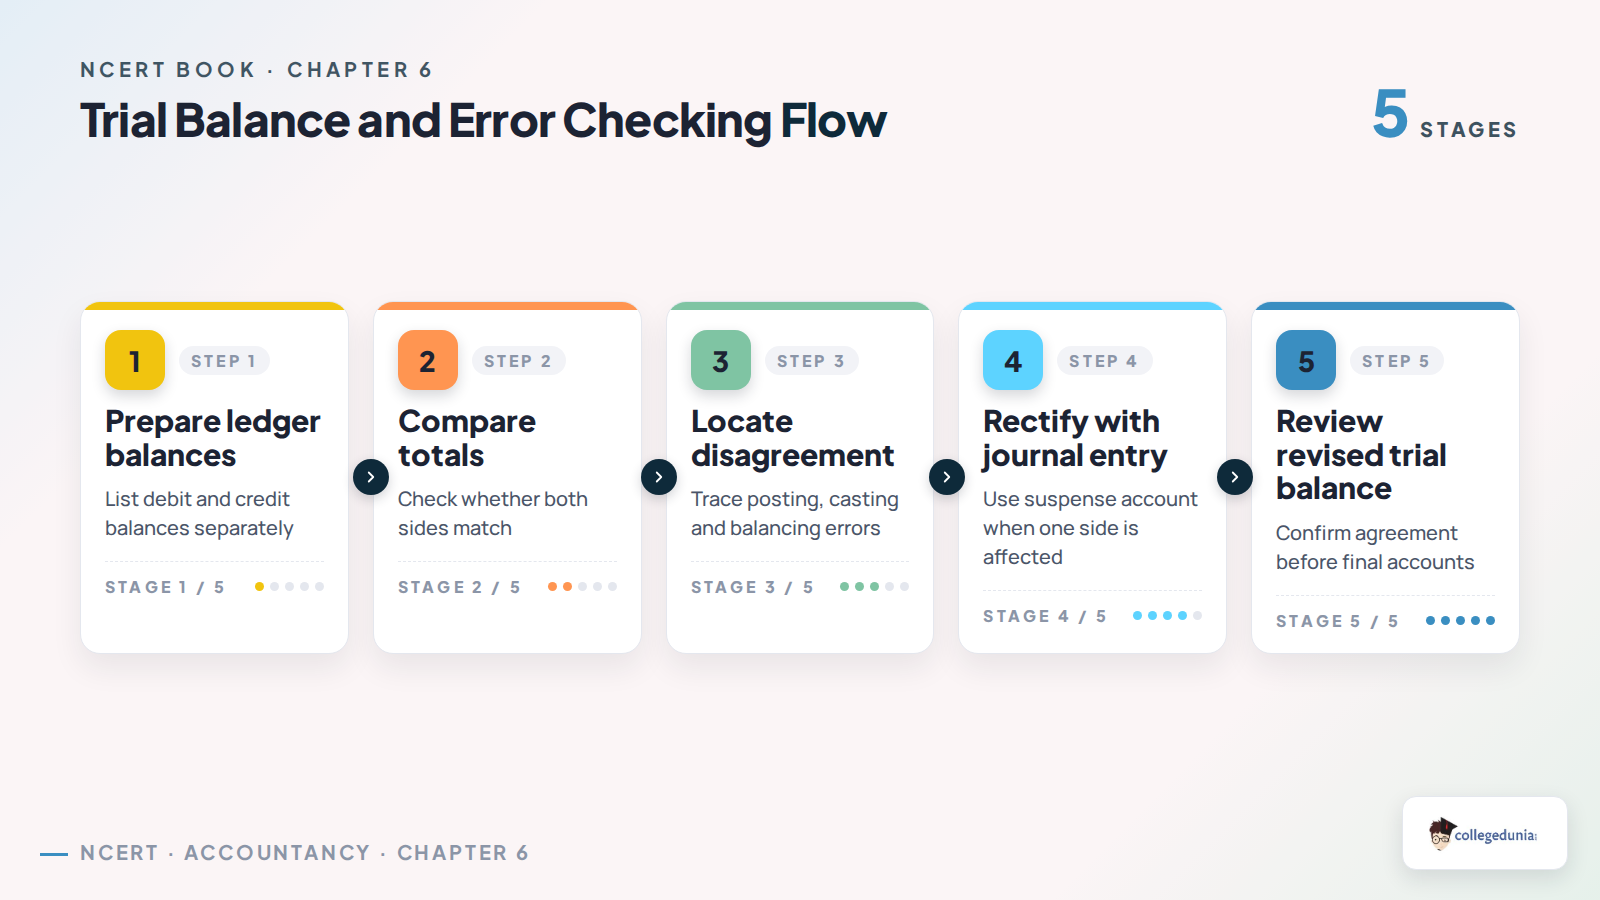
The safest method is to work in order. Prepare the trial balance, compare the totals, locate the error and then pass the rectification entry.
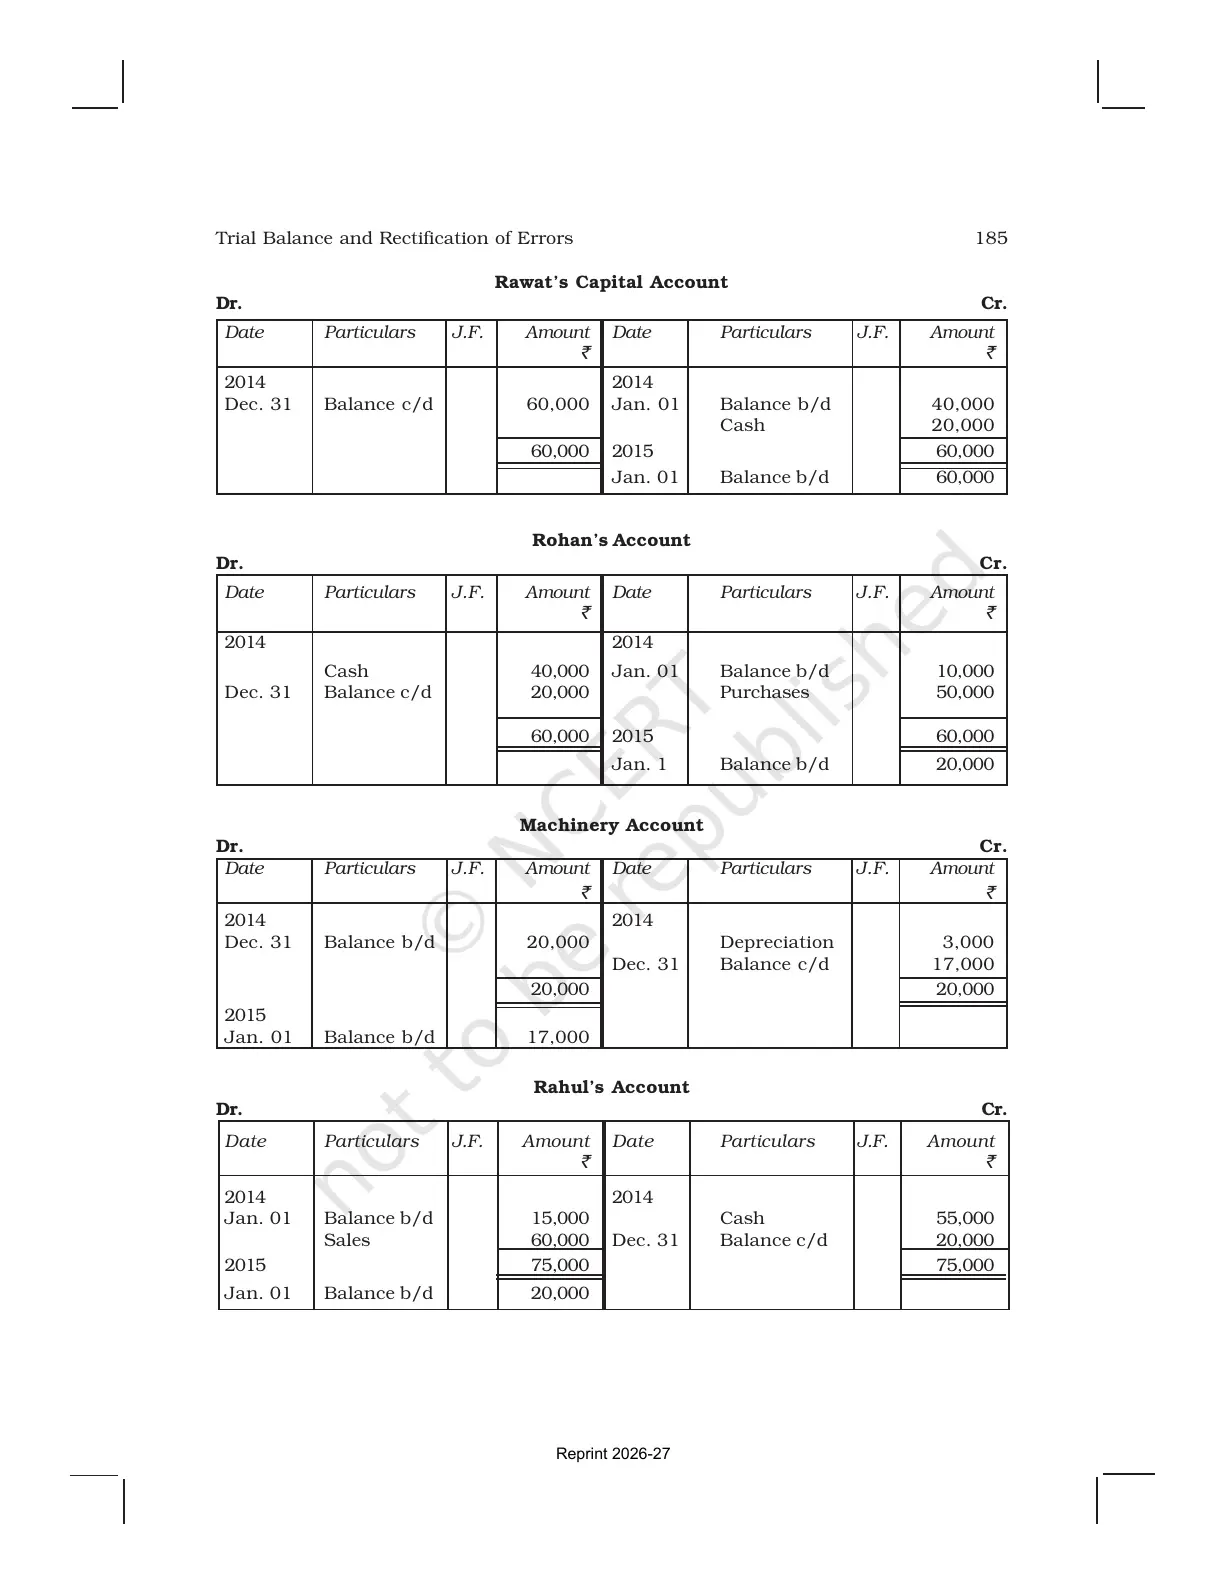
- Prepare ledger balances and place debit and credit amounts separately.
- Compare both totals before moving to final accounts.
- Trace posting, casting, carry-forward and balancing errors.
- Use suspense account only when one side is affected.
- Prepare the revised trial balance after correction.
Errors Disclosed and Not Disclosed by Trial Balance
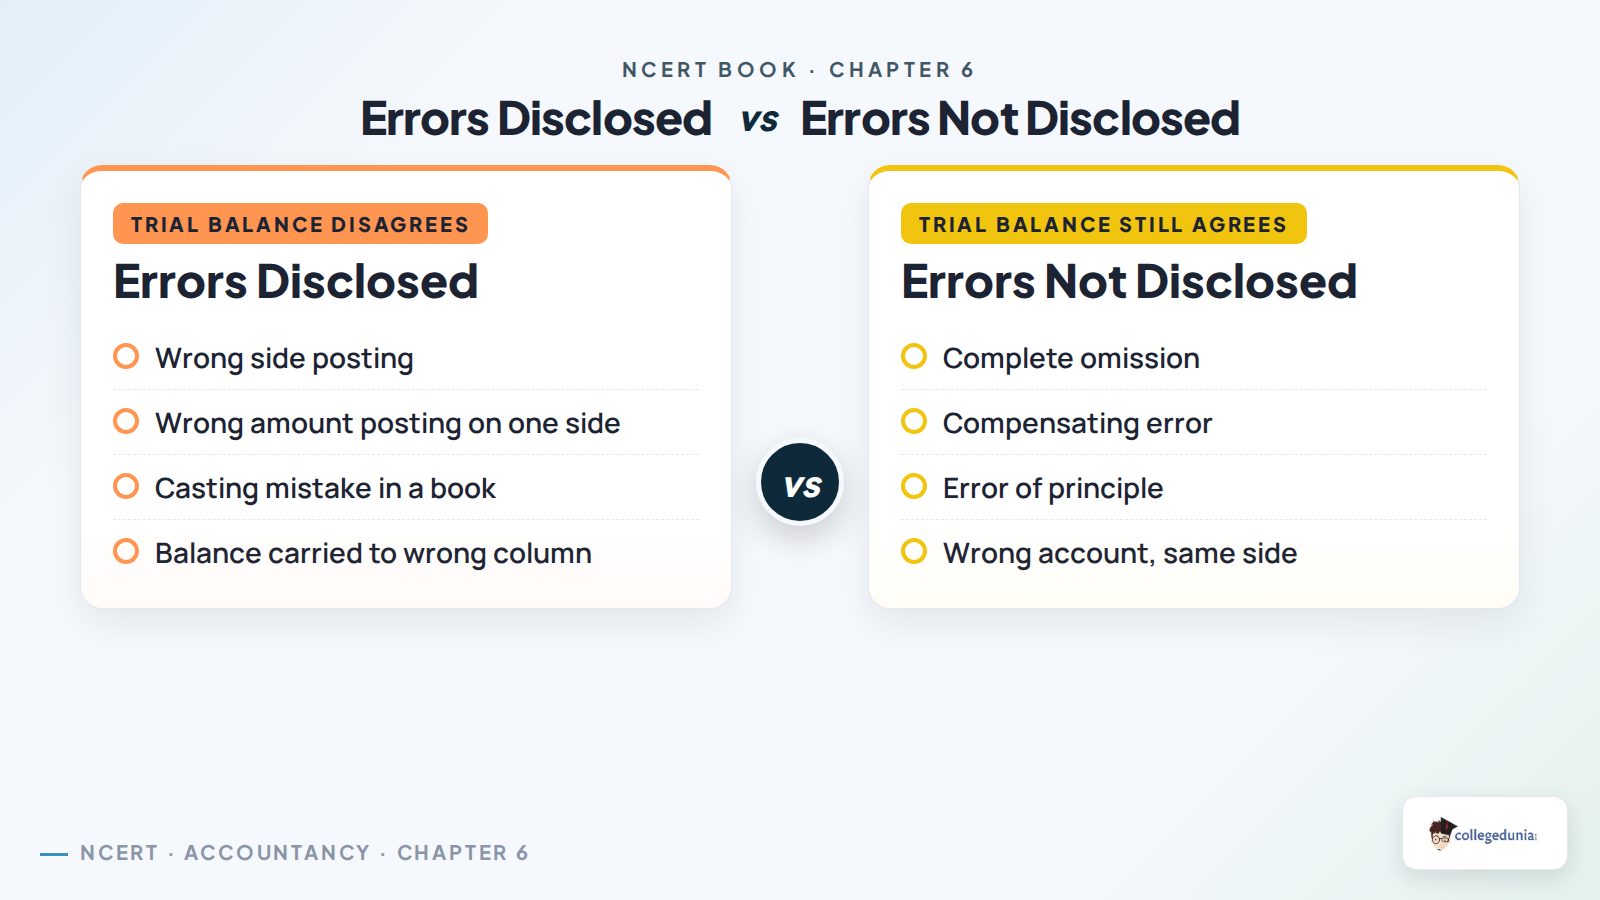
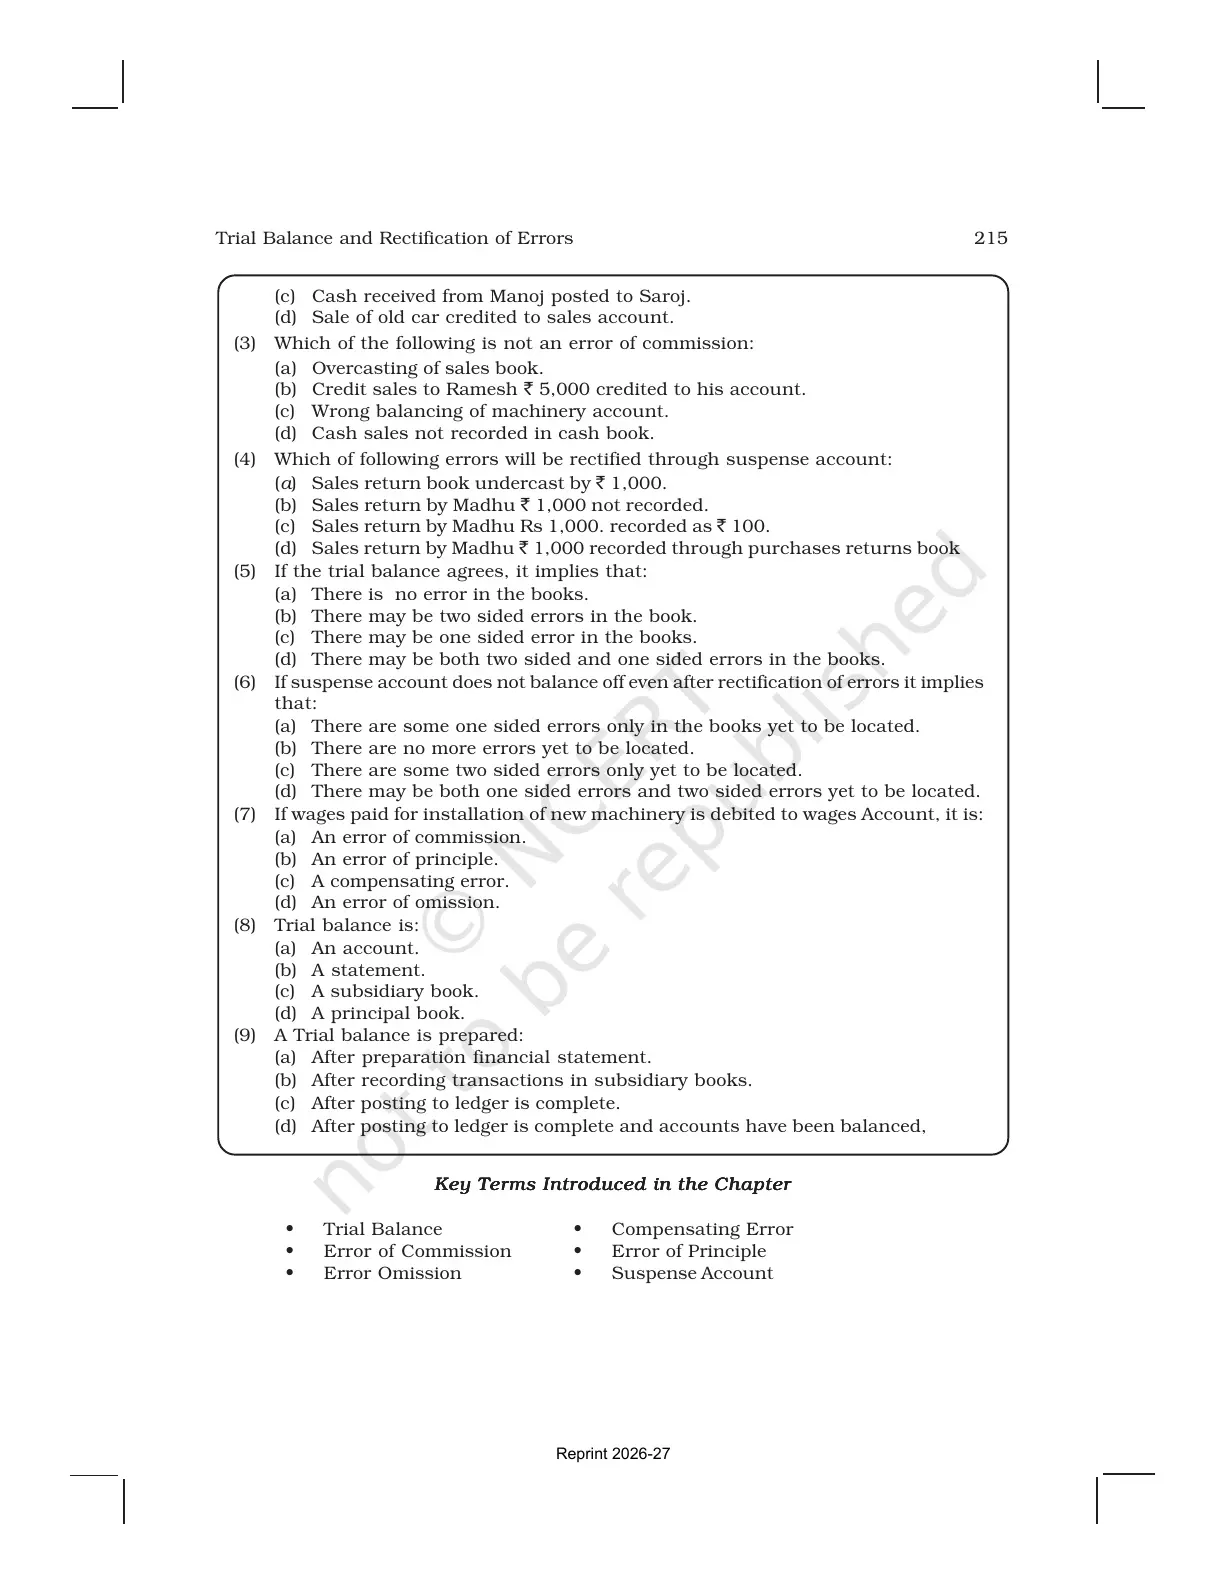
Some errors disturb debit-credit equality. Some errors do not disturb it at all, so students must not depend only on matching totals.
- Disclosed errors: wrong-side posting, wrong amount on one side and casting mistakes.
- Not disclosed errors: complete omission, compensating error and error of principle.
- Exam cue: first decide whether suspense account is needed.
Compensating errors are risky because the trial balance can still agree. The books may look balanced even when two wrong entries cancel each other.
Suspense Account and Rectification Entries in Chapter 6
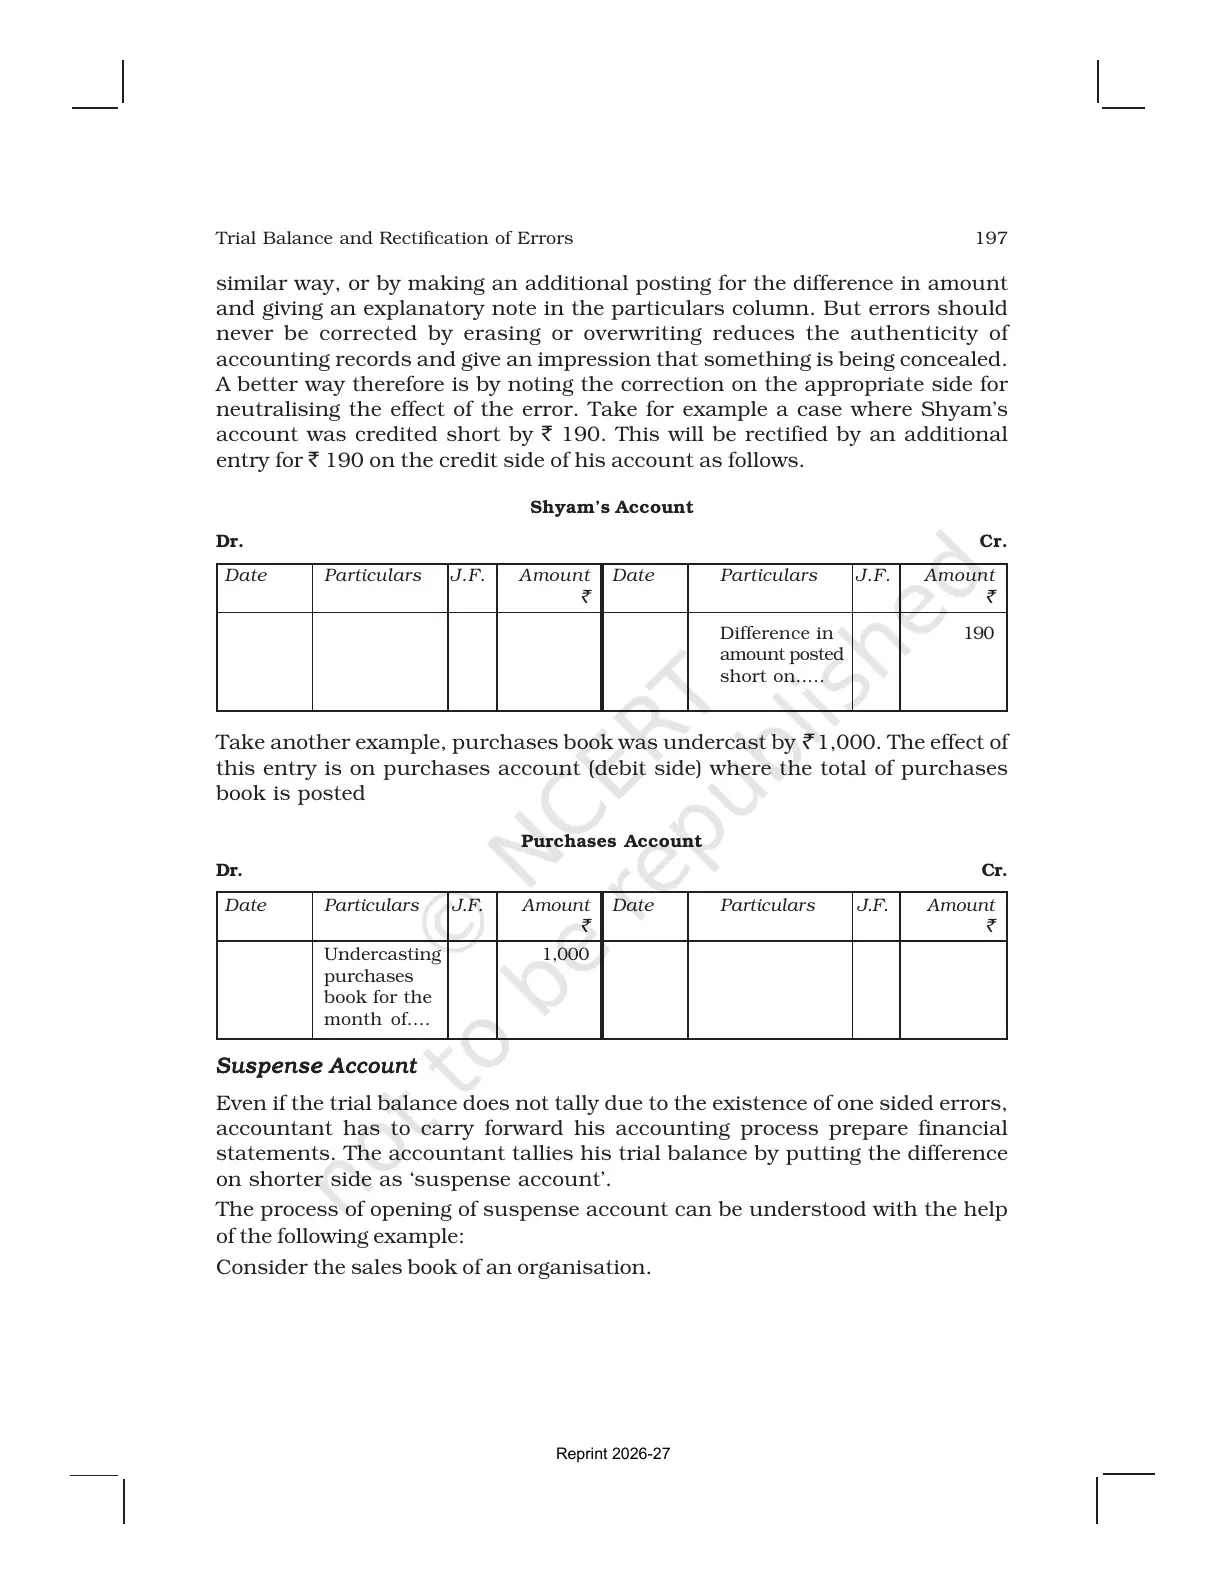
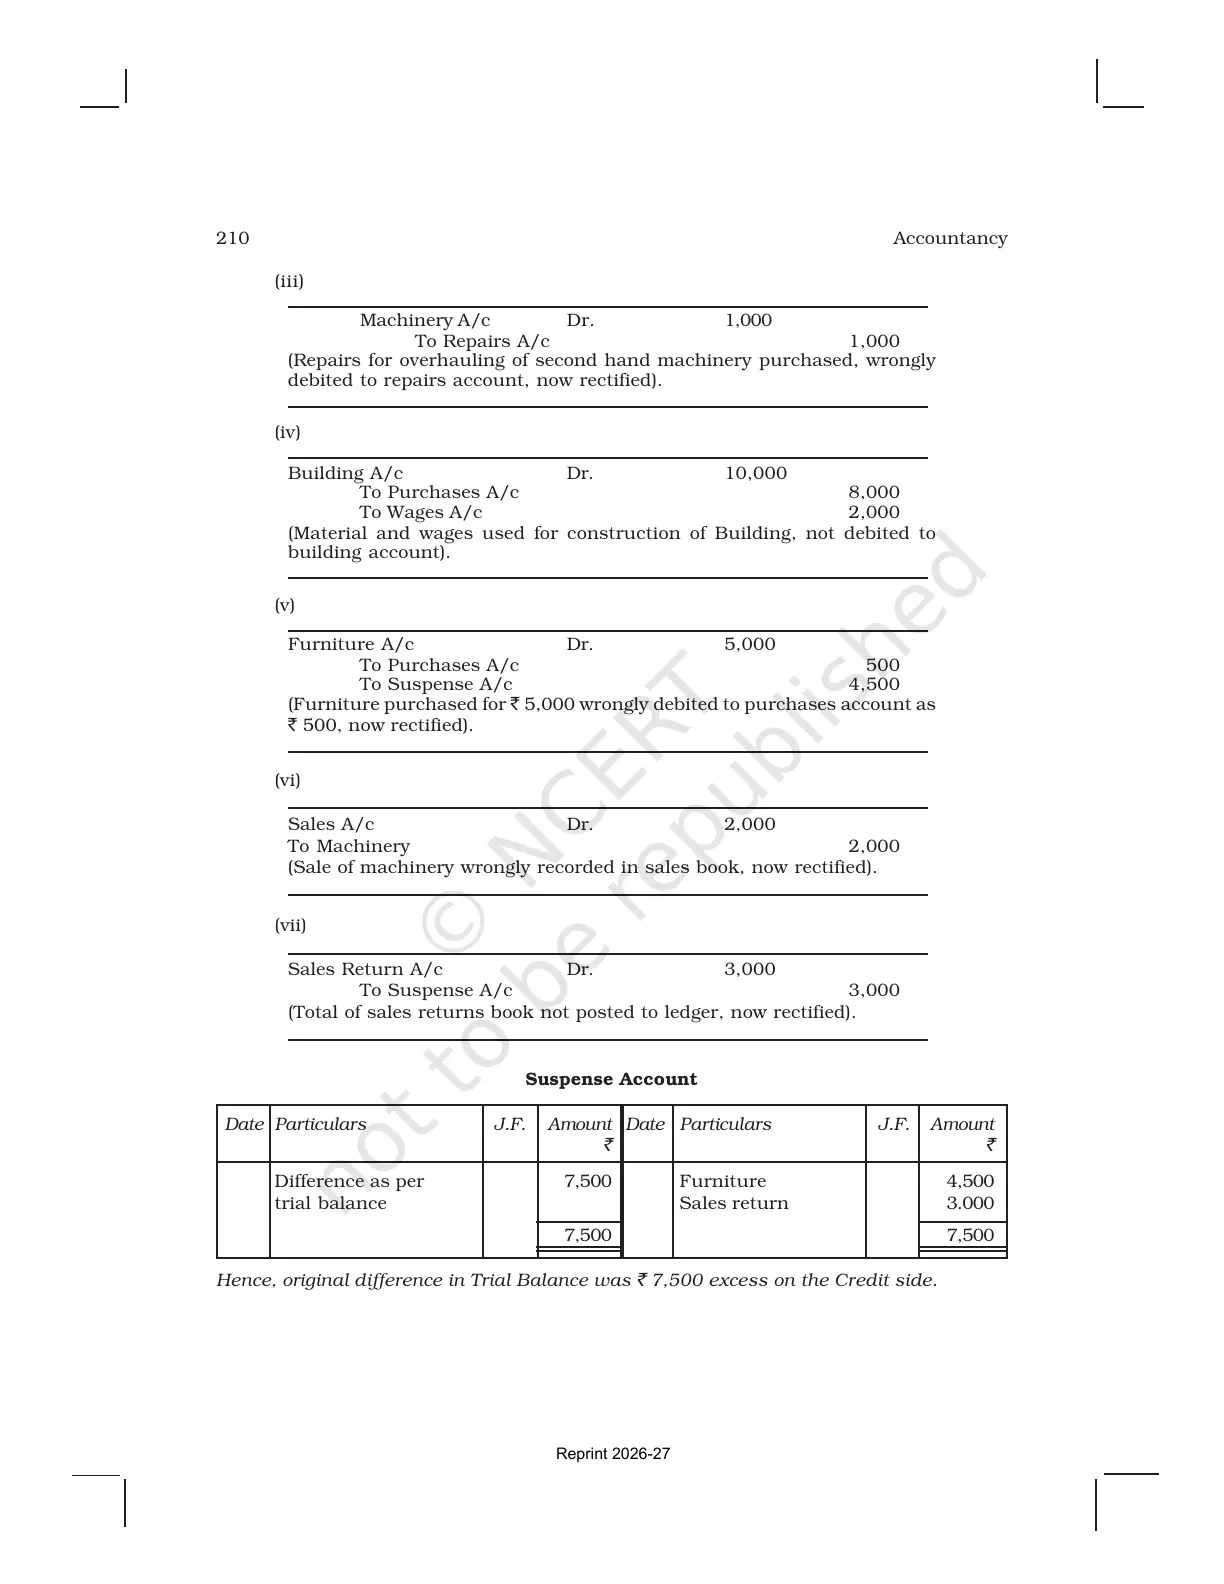
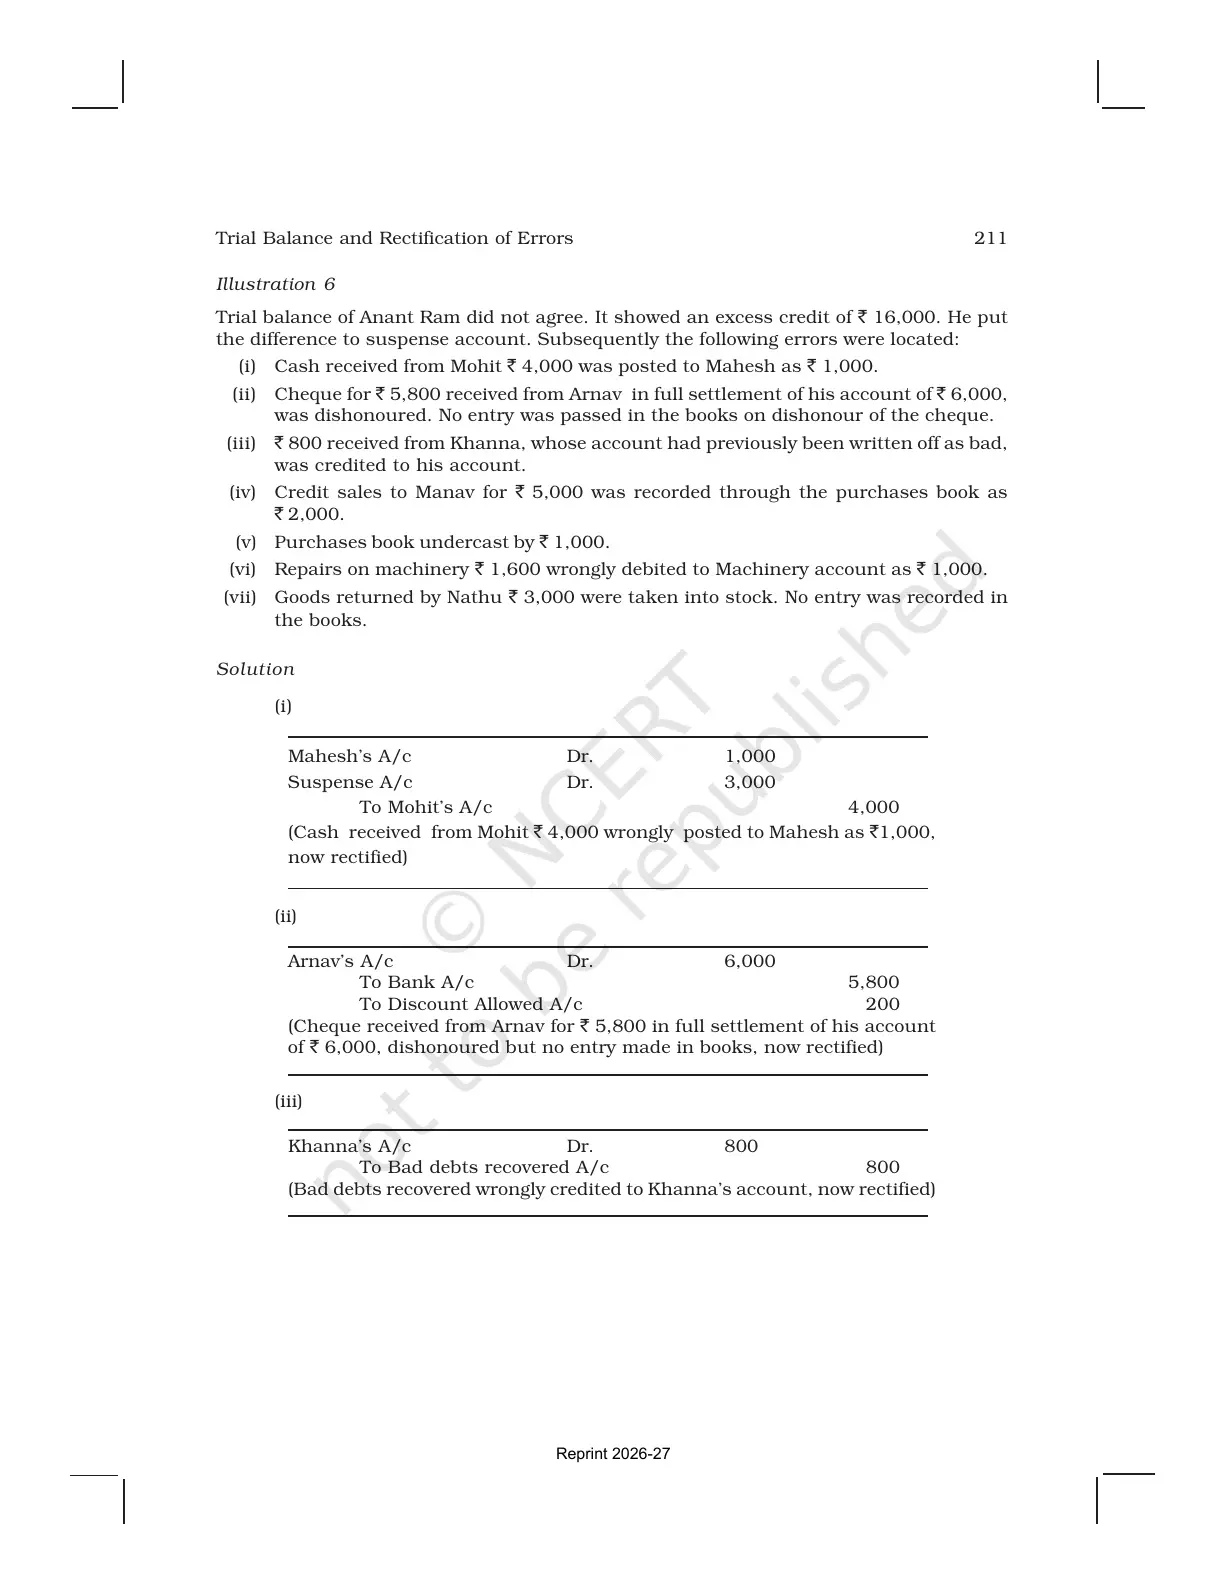
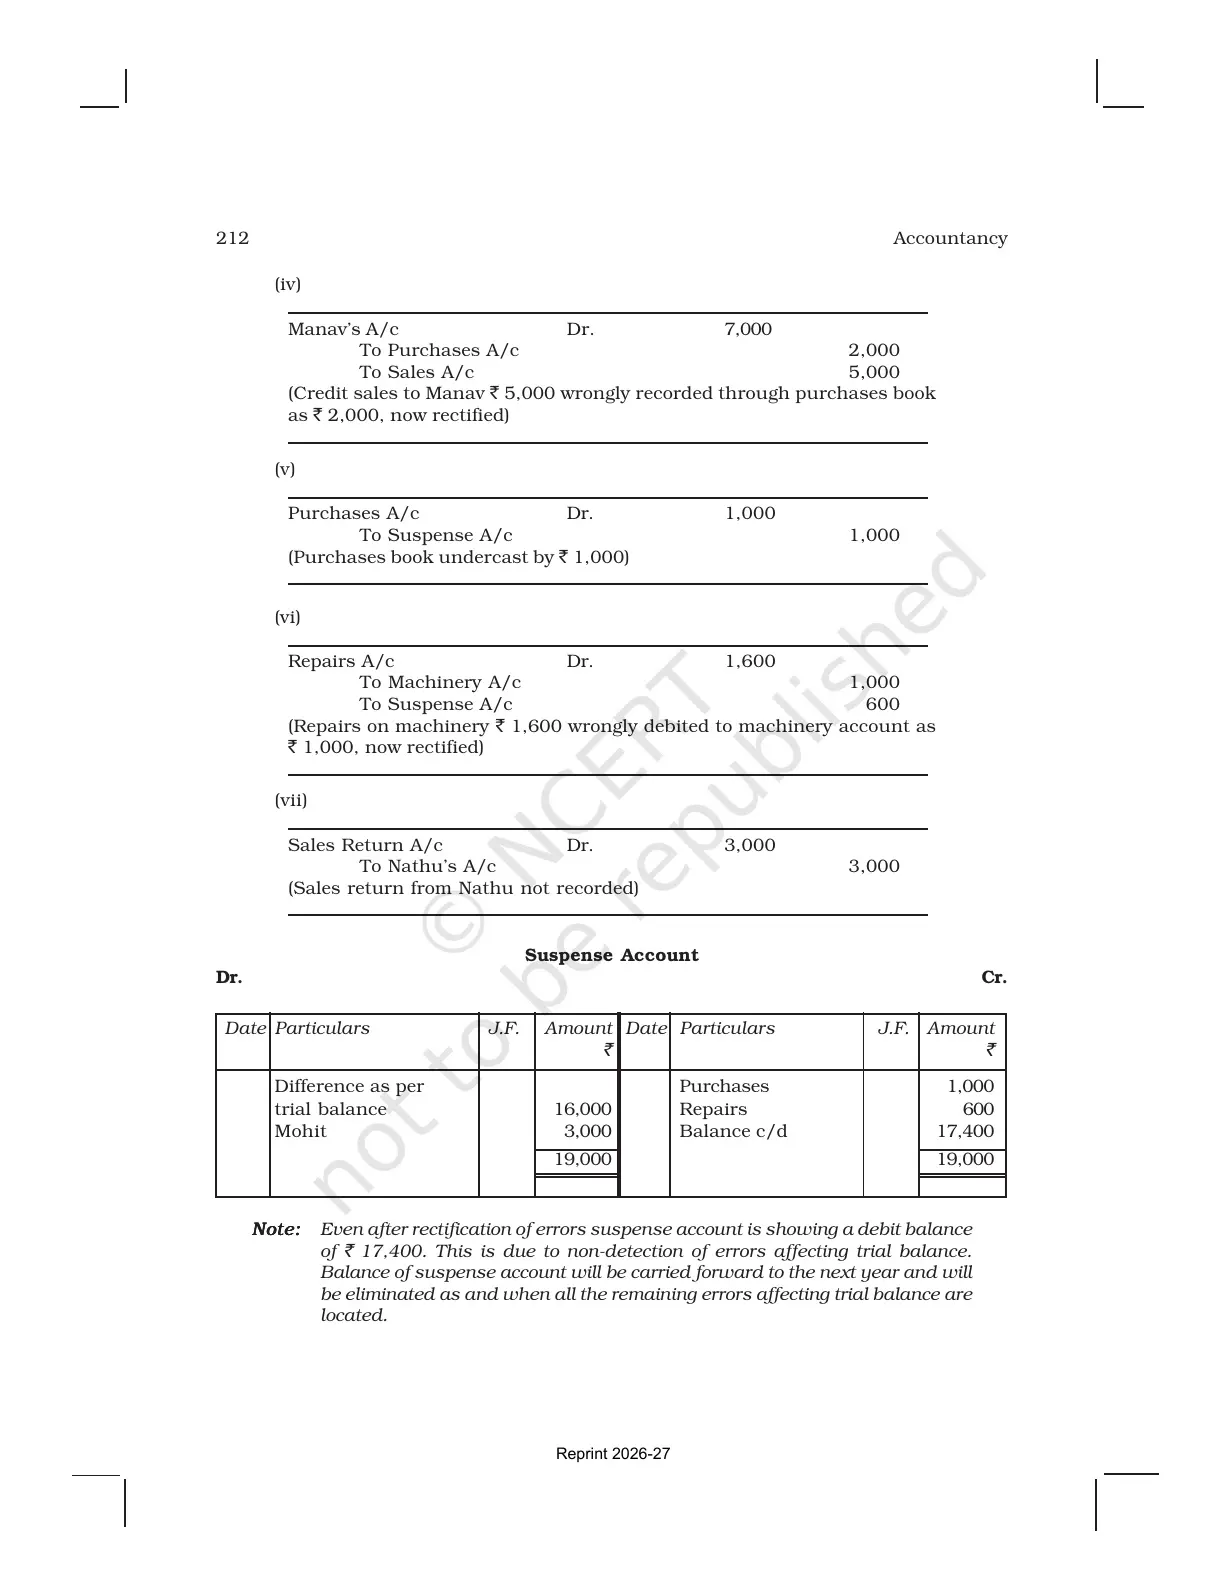
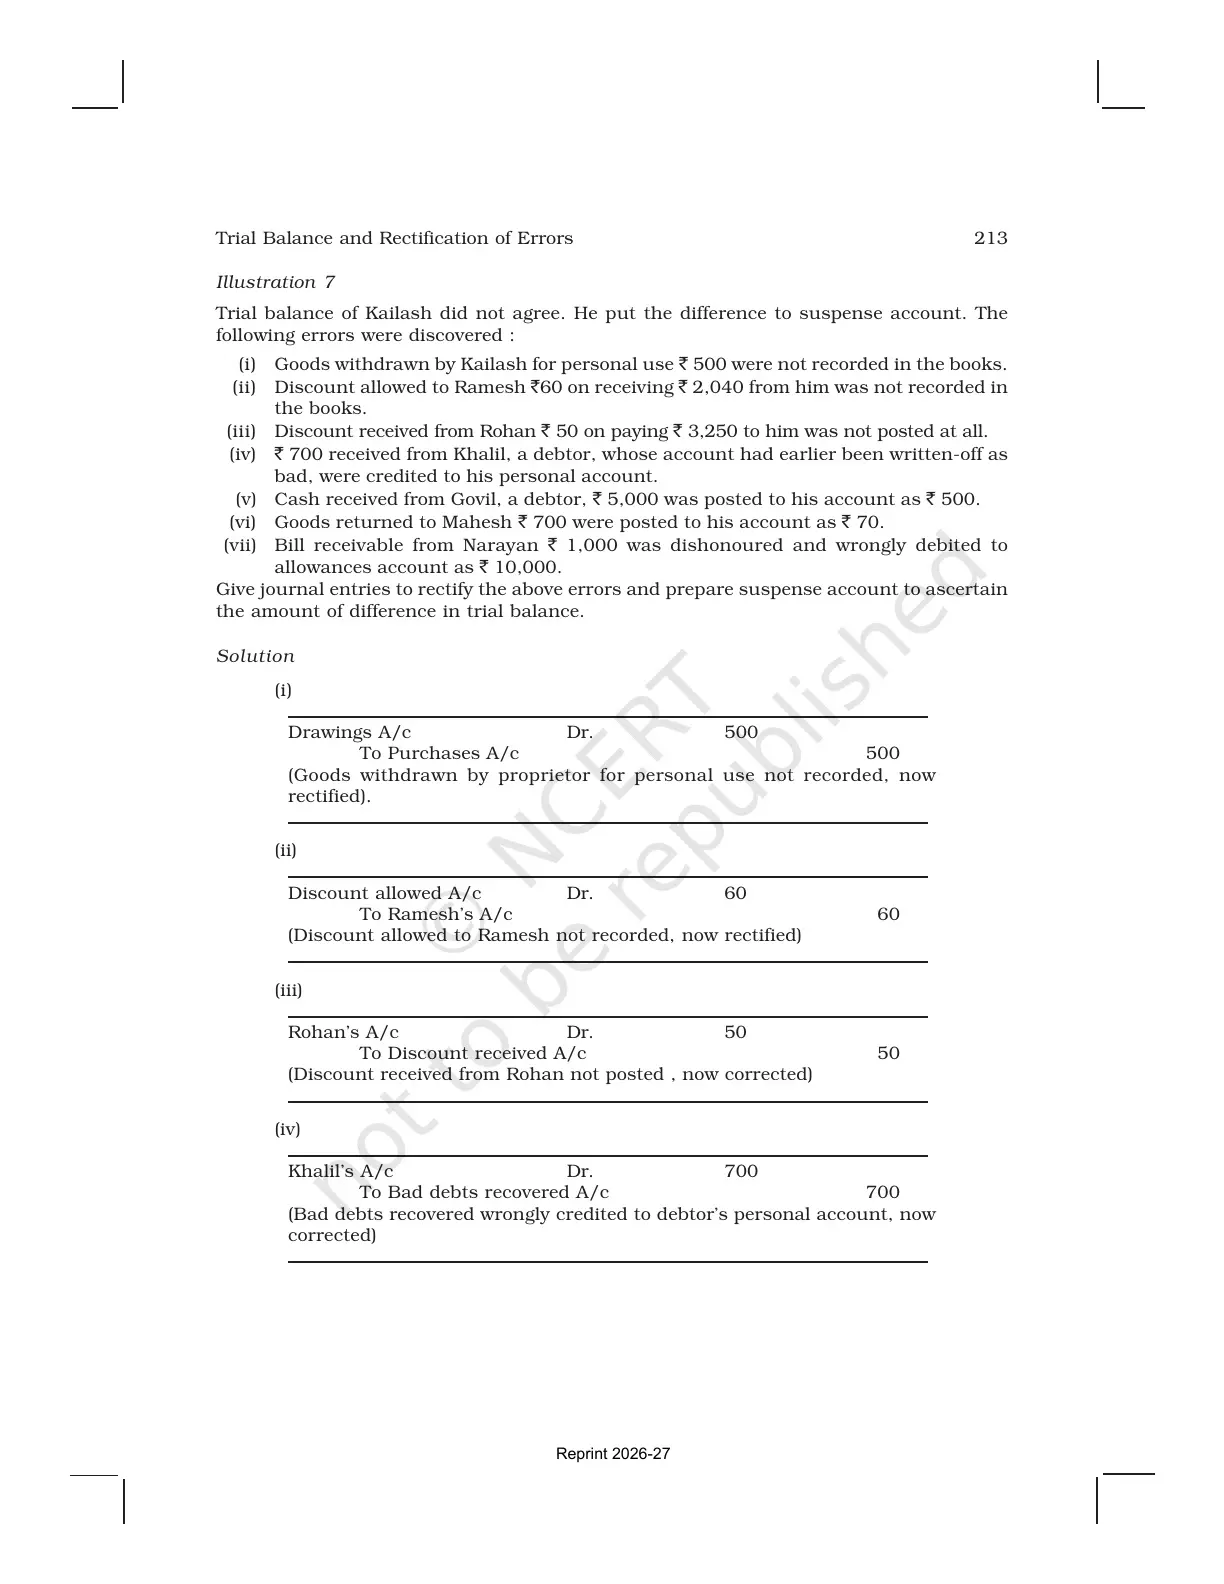
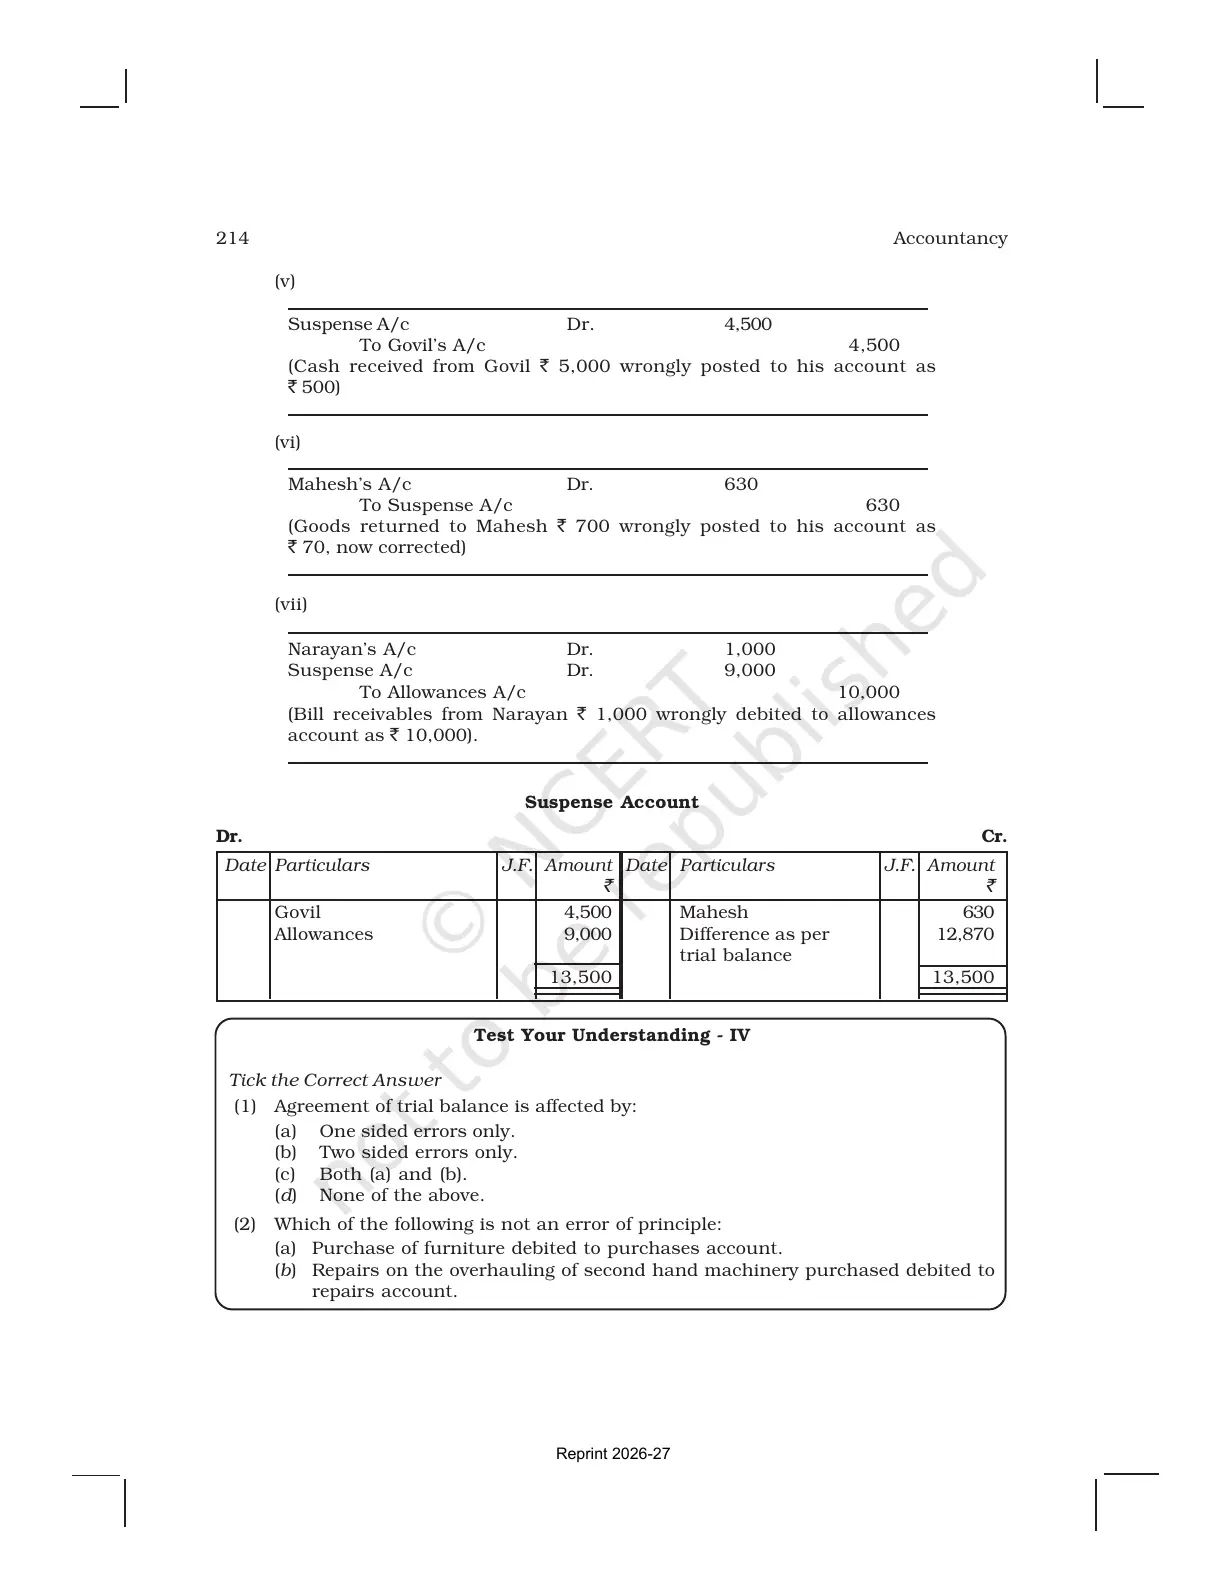
The suspense account is a temporary account. It is used when the trial balance does not agree and the error has not been found yet.
Once the error is found, pass the rectification entry. If the error affected only one side, suspense account appears in the correction.
- Before trial balance: correct the wrong account directly.
- After trial balance: use suspense account when the mismatch has been parked there.
- After final accounts: correction may affect profit and loss adjustment.
How to Study the Trial Balance and Rectification NCERT PDF
Read the theory once, then solve the illustrations slowly. The chapter becomes easier when each mistake is classified before the journal entry is written.
- Mark whether the error affects one side or two sides.
- Check whether trial balance agreement is affected.
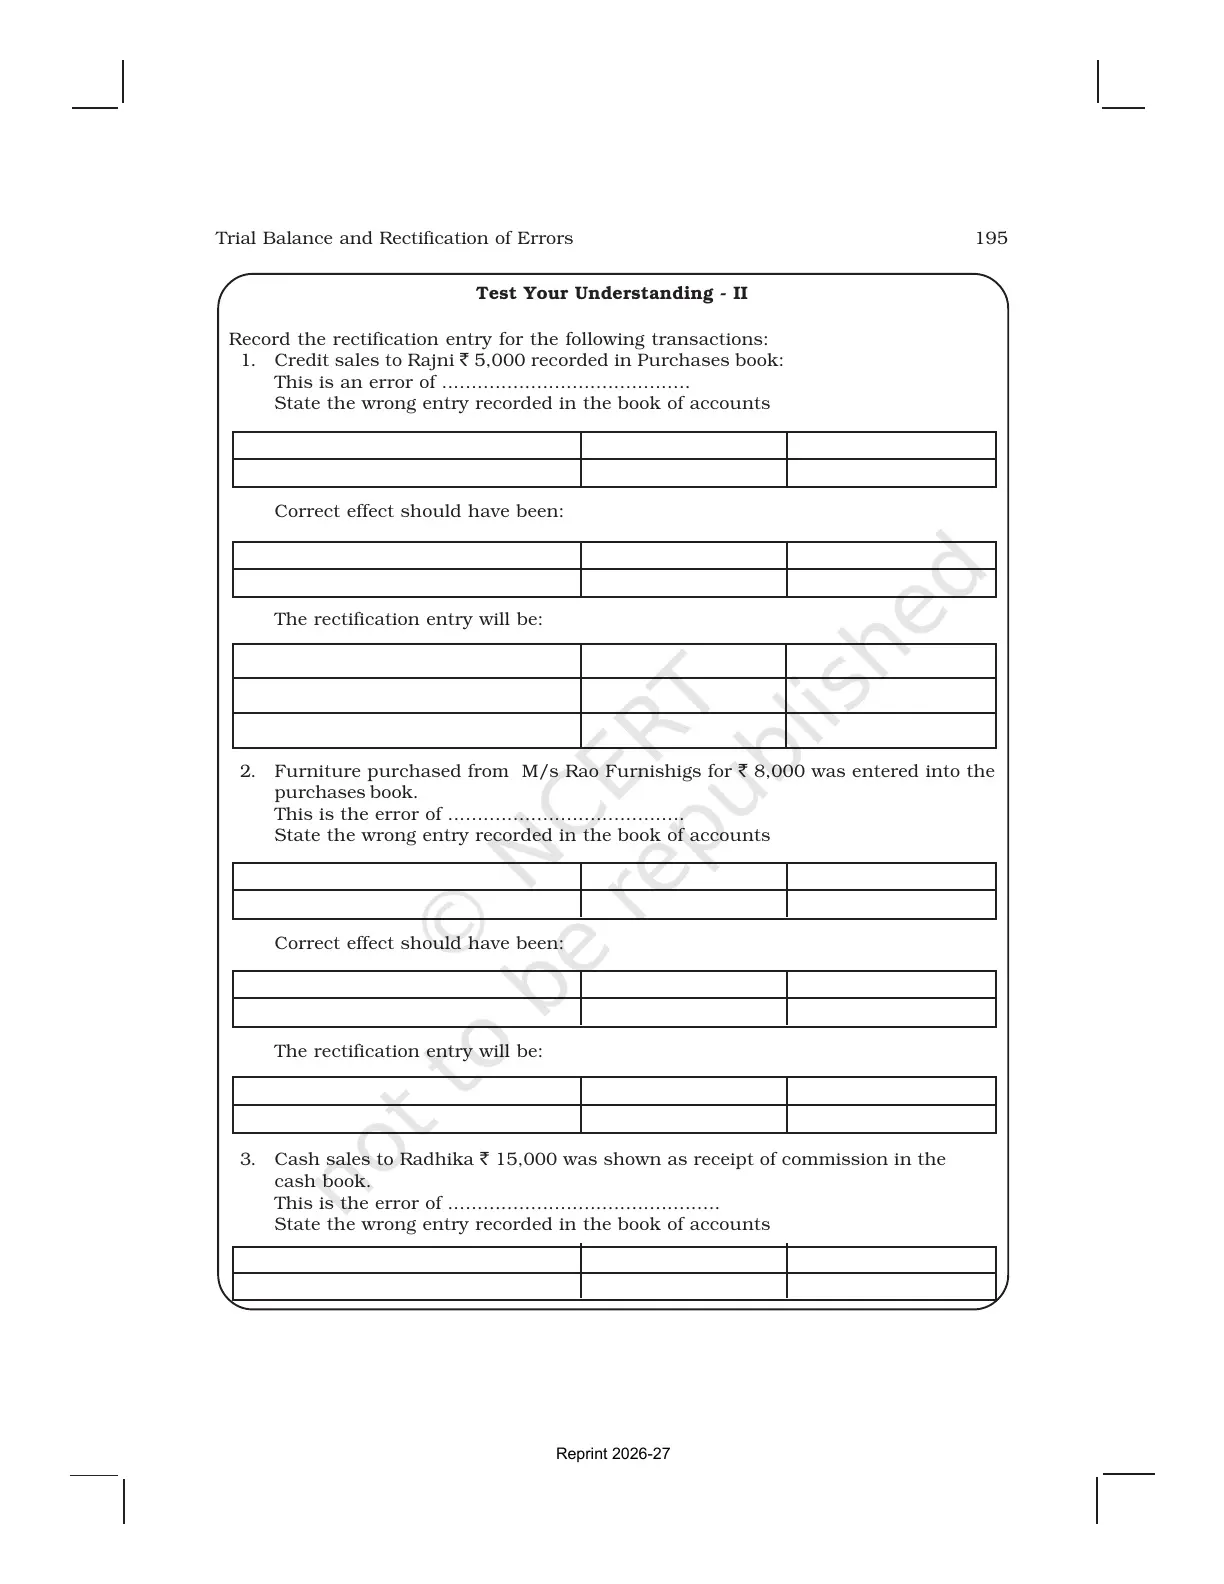
- Write the correct entry first, then compare it with the wrong entry.
- Use suspense account only where the chapter asks for it.
- Recheck the revised trial balance total after rectification.
Trial Balance and Rectification of Errors Class 11 Related Resources
| Resource | Best use |
|---|---|
| Trial Balance and Rectification of Errors Class 11 NCERT Solutions | Check solved rectification questions and journal entries |
| Trial Balance and Rectification of Errors Class 11 Notes | Revise error types, suspense account and correction rules |
| Trial Balance and Rectification of Errors Class 11 Handwritten Notes | Use handwritten revision notes before accountancy tests |
All Class 11 Accountancy NCERT Book Chapters
| Chapter | NCERT Book PDF |
|---|---|
| 1 | Introduction to Accounting |
| 2 | Theory Base of Accounting |
| 3 | Recording of Transactions - I |
| 4 | Recording of Transactions - II |
| 5 | Bank Reconciliation Statement |
| 6 | Trial Balance and Rectification of Errors |
| 7 | Depreciation, Provisions and Reserves |
| 8 | Financial Statements - I |
| 9 | Financial Statements - II |
Trial Balance and Rectification of Errors Class 11 NCERT Book FAQs
Ques. What does Trial Balance and Rectification of Errors cover in Class 11 Accountancy?
Ans. It covers trial balance preparation, types of accounting errors, suspense account and journal entries used to rectify mistakes.
Ques. Does a matching trial balance prove that all accounts are correct?
Ans. No. A matching trial balance only checks arithmetical agreement. Complete omission, compensating error and error of principle may still remain.
Ques. When is suspense account used in rectification of errors?
Ans. Suspense account is used when the trial balance does not agree and a one-sided error has affected the books.
Ques. How should students start a rectification question?
Ans. Students should first write the correct entry, compare it with the wrong entry and then pass the correction entry.
Ques. Is this PDF based on the 2026-27 NCERT book?
Ans. Yes. The PDF is from the Class 11 Accountancy NCERT reprint for the 2026-27 academic session.


Comments