

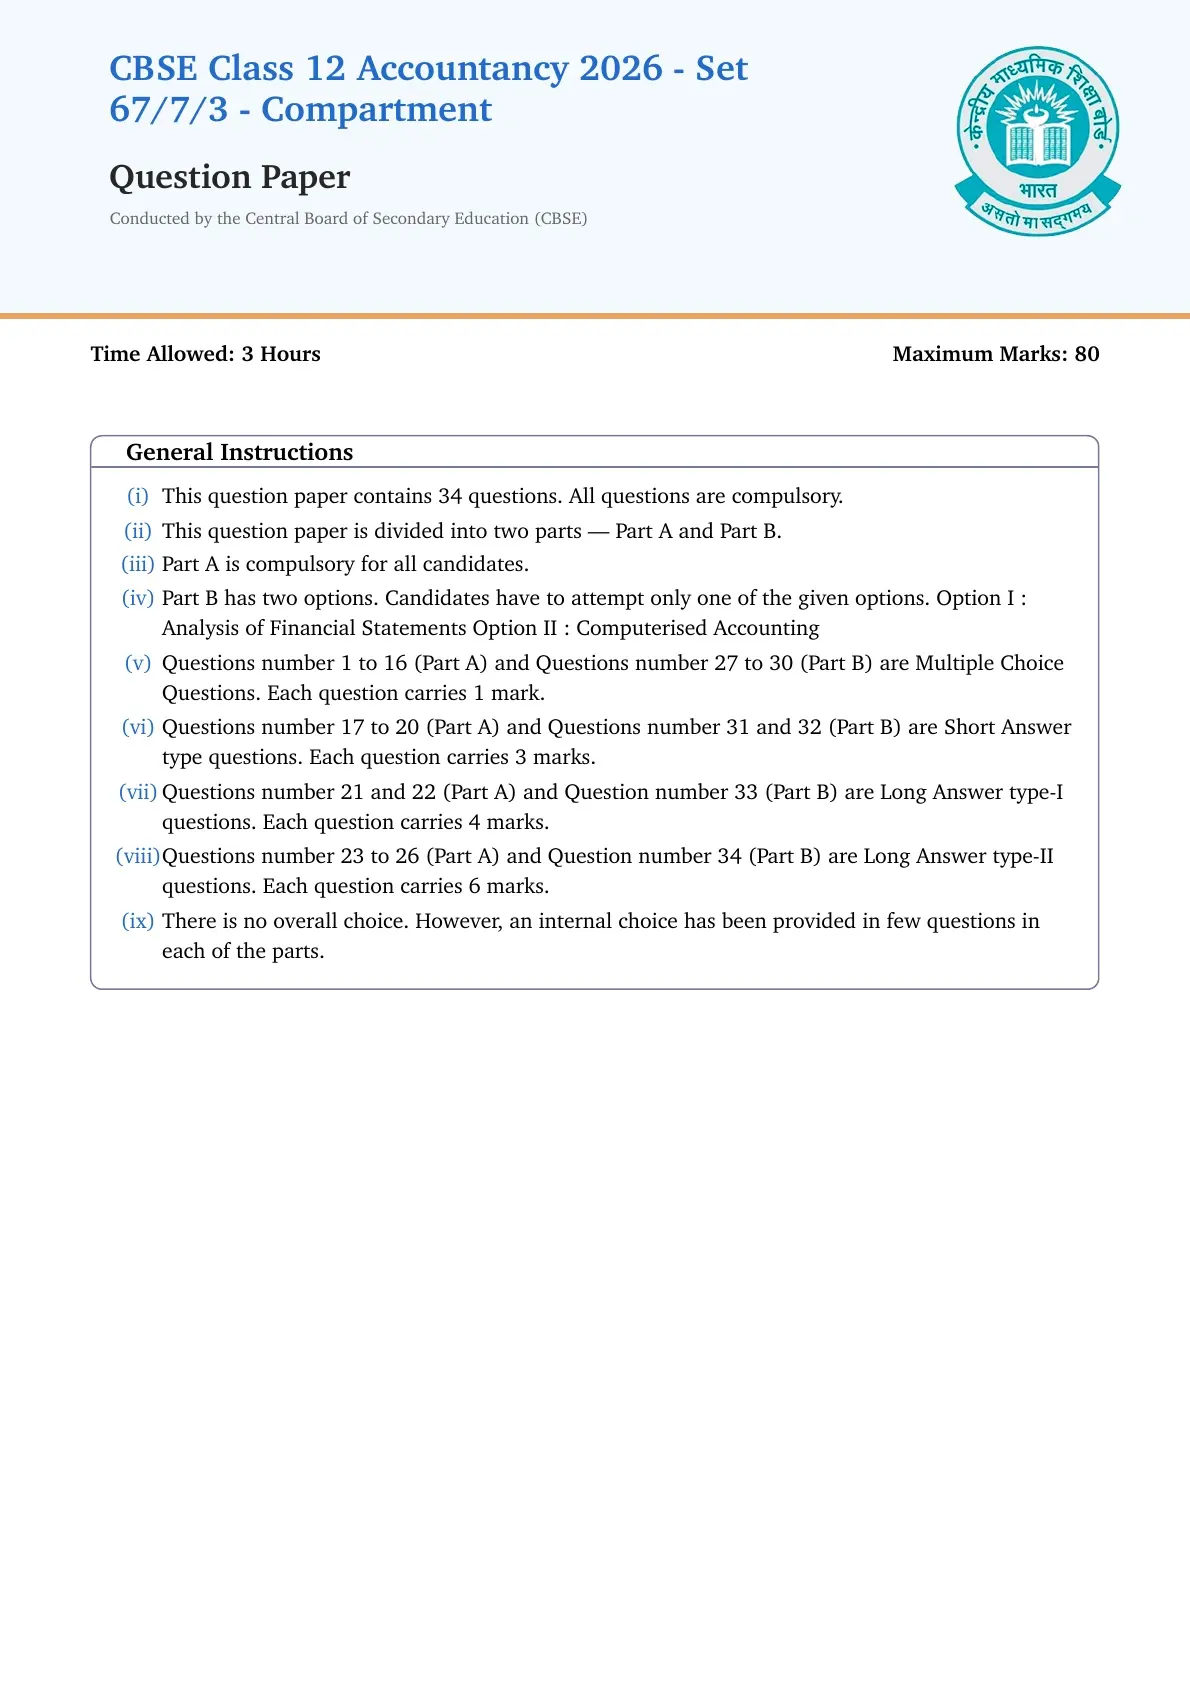
CBSE Class 12 Accountancy Compartment Set 3 - (67/7/3) Question Paper 2026 details are given here. CBSE conducted the Class 12 Accountancy Compartment (supplementary) examination on July 28, 2026, from 10:30 AM to 1:30 PM. The Accountancy paper is of 80 marks and the time allowed is 3 hours. This paper carries the Q.P. code 67/7/3 and is of Set 3. The question paper was handed out at 10:15 AM, and the first 15 minutes were given for reading it.
Also Check: CBSE Class 12 Question Paper 2026 (All Subjects)
The paper has 34 questions in two parts, and all questions are compulsory:
- Part A (Accounting for Partnership Firms and Companies) is compulsory for all candidates
- Part B has two options, Option I (Analysis of Financial Statements) and Option II (Computerised Accounting), and a candidate attempts only one of them
- Multiple choice questions of 1 mark each: Questions 1 - 16 of Part A and 27 - 30 of Part B
- Short answer questions of 3 marks each: Q17 - Q20 and Q31 - Q32
- Long answer type-I questions of 4 marks each: Q21 - Q22 and Q33
- Long answer type-II questions of 6 marks each: Q23 - Q26 and Q34
CBSE Class 12 Accountancy Compartment Set 3 - (67/7/3) Question Paper 2026 with Solution PDF
| CBSE Official PDF | CD PDF | CD PDF with Solutions |
|---|---|---|
| Download official PDF 0.57 MB | Download Collegedunia PDF 0.32 MB | Download solutions PDF 0.40 MB |
CBSE Class 12 Accountancy Compartment 2026 Set 3 (67/7/3) Questions with Solutions
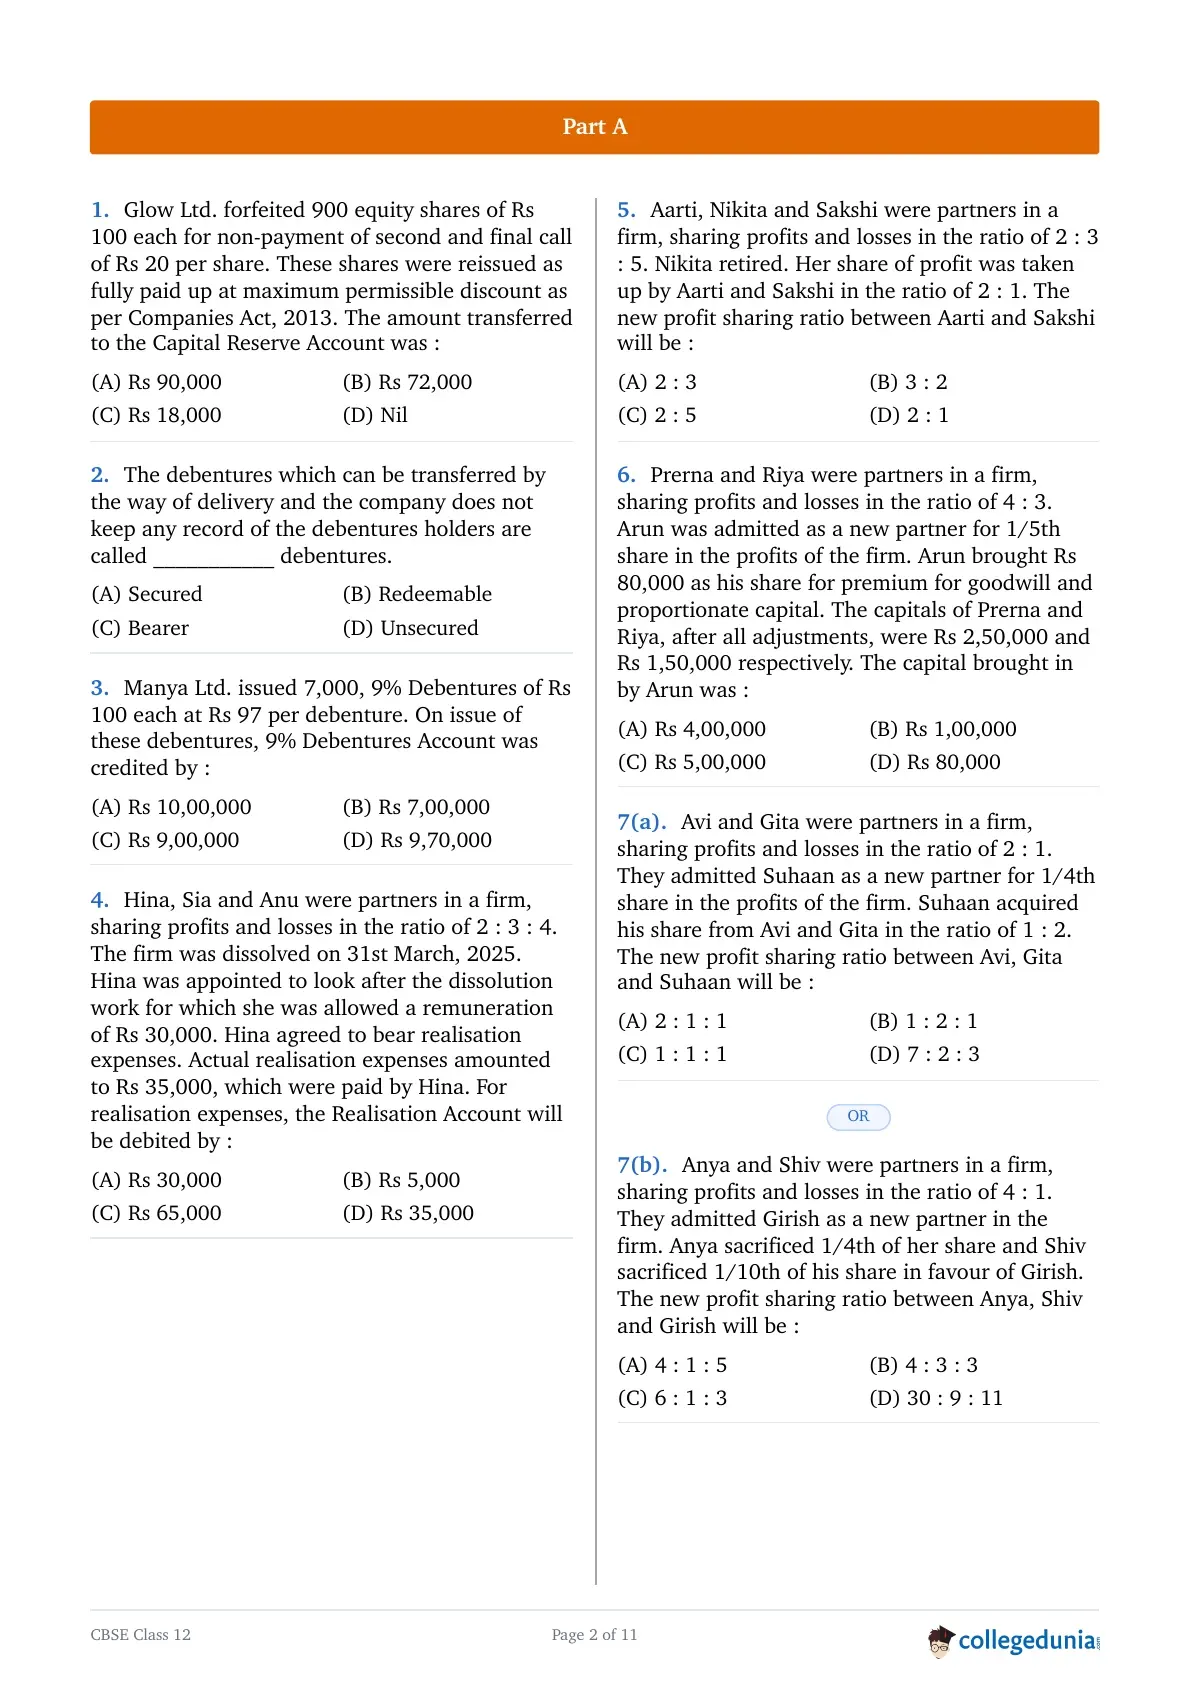
Glow Ltd. forfeited 900 equity shares of Rs 100 each for non-payment of second and final call of Rs 20 per share. These shares were reissued as fully paid up at maximum permissible discount as per Companies Act, 2013. The amount transferred to the Capital Reserve Account was :
The debentures which can be transferred by the way of delivery and the company does not keep any record of the debentures holders are called ___________ debentures.
Manya Ltd. issued 7,000, 9% Debentures of Rs 100 each at Rs 97 per debenture. On issue of these debentures, 9% Debentures Account was credited by :
Hina, Sia and Anu were partners in a firm, sharing profits and losses in the ratio of 2 : 3 : 4. The firm was dissolved on 31st March, 2025. Hina was appointed to look after the dissolution work for which she was allowed a remuneration of Rs 30,000. Hina agreed to bear realisation expenses. Actual realisation expenses amounted to Rs 35,000, which were paid by Hina. For realisation expenses, the Realisation Account will be debited by :
Aarti, Nikita and Sakshi were partners in a firm, sharing profits and losses in the ratio of 2 : 3 : 5. Nikita retired. Her share of profit was taken up by Aarti and Sakshi in the ratio of 2 : 1. The new profit sharing ratio between Aarti and Sakshi will be :
Prerna and Riya were partners in a firm, sharing profits and losses in the ratio of 4 : 3. Arun was admitted as a new partner for 1/5th share in the profits of the firm. Arun brought Rs 80,000 as his share for premium for goodwill and proportionate capital. The capitals of Prerna and Riya, after all adjustments, were Rs 2,50,000 and Rs 1,50,000 respectively. The capital brought in by Arun was :
Avi and Gita were partners in a firm, sharing profits and losses in the ratio of 2 : 1. They admitted Suhaan as a new partner for 1/4th share in the profits of the firm. Suhaan acquired his share from Avi and Gita in the ratio of 1 : 2. The new profit sharing ratio between Avi, Gita and Suhaan will be :
Anya and Shiv were partners in a firm, sharing profits and losses in the ratio of 4 : 1. They admitted Girish as a new partner in the firm. Anya sacrificed 1/4th of her share and Shiv sacrificed 1/10th of his share in favour of Girish. The new profit sharing ratio between Anya, Shiv and Girish will be :
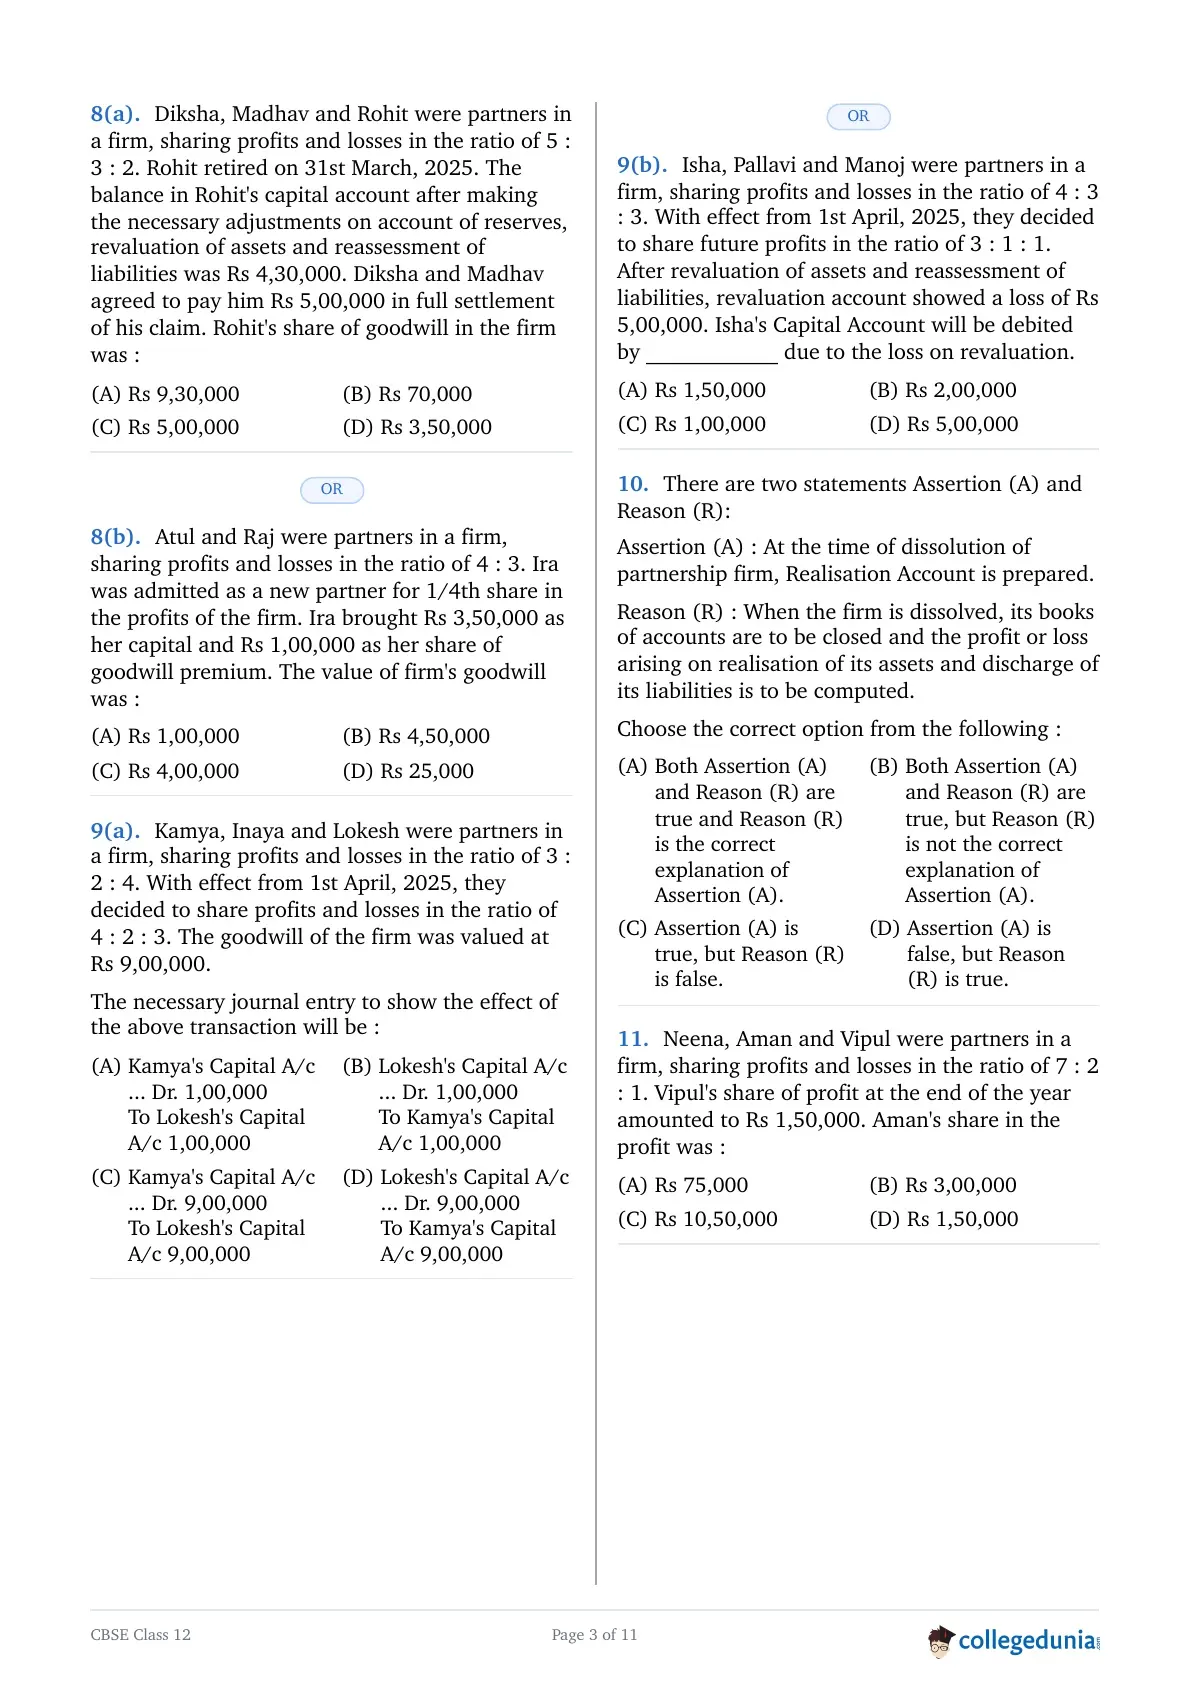
Diksha, Madhav and Rohit were partners in a firm, sharing profits and losses in the ratio of 5 : 3 : 2. Rohit retired on 31st March, 2025. The balance in Rohit's capital account after making the necessary adjustments on account of reserves, revaluation of assets and reassessment of liabilities was Rs 4,30,000. Diksha and Madhav agreed to pay him Rs 5,00,000 in full settlement of his claim. Rohit's share of goodwill in the firm was :
Atul and Raj were partners in a firm, sharing profits and losses in the ratio of 4 : 3. Ira was admitted as a new partner for 1/4th share in the profits of the firm. Ira brought Rs 3,50,000 as her capital and Rs 1,00,000 as her share of goodwill premium. The value of firm's goodwill was :
Kamya, Inaya and Lokesh were partners in a firm, sharing profits and losses in the ratio of 3 : 2 : 4. With effect from 1st April, 2025, they decided to share profits and losses in the ratio of 4 : 2 : 3. The goodwill of the firm was valued at Rs 9,00,000.
The necessary journal entry to show the effect of the above transaction will be :
Isha, Pallavi and Manoj were partners in a firm, sharing profits and losses in the ratio of 4 : 3 : 3. With effect from 1st April, 2025, they decided to share future profits in the ratio of 3 : 1 : 1. After revaluation of assets and reassessment of liabilities, revaluation account showed a loss of Rs 5,00,000. Isha's Capital Account will be debited by ____________ due to the loss on revaluation.
There are two statements Assertion (A) and Reason (R):
Assertion (A) : At the time of dissolution of partnership firm, Realisation Account is prepared.
Reason (R) : When the firm is dissolved, its books of accounts are to be closed and the profit or loss arising on realisation of its assets and discharge of its liabilities is to be computed.
Choose the correct option from the following :
Neena, Aman and Vipul were partners in a firm, sharing profits and losses in the ratio of 7 : 2 : 1. Vipul's share of profit at the end of the year amounted to Rs 1,50,000. Aman's share in the profit was :
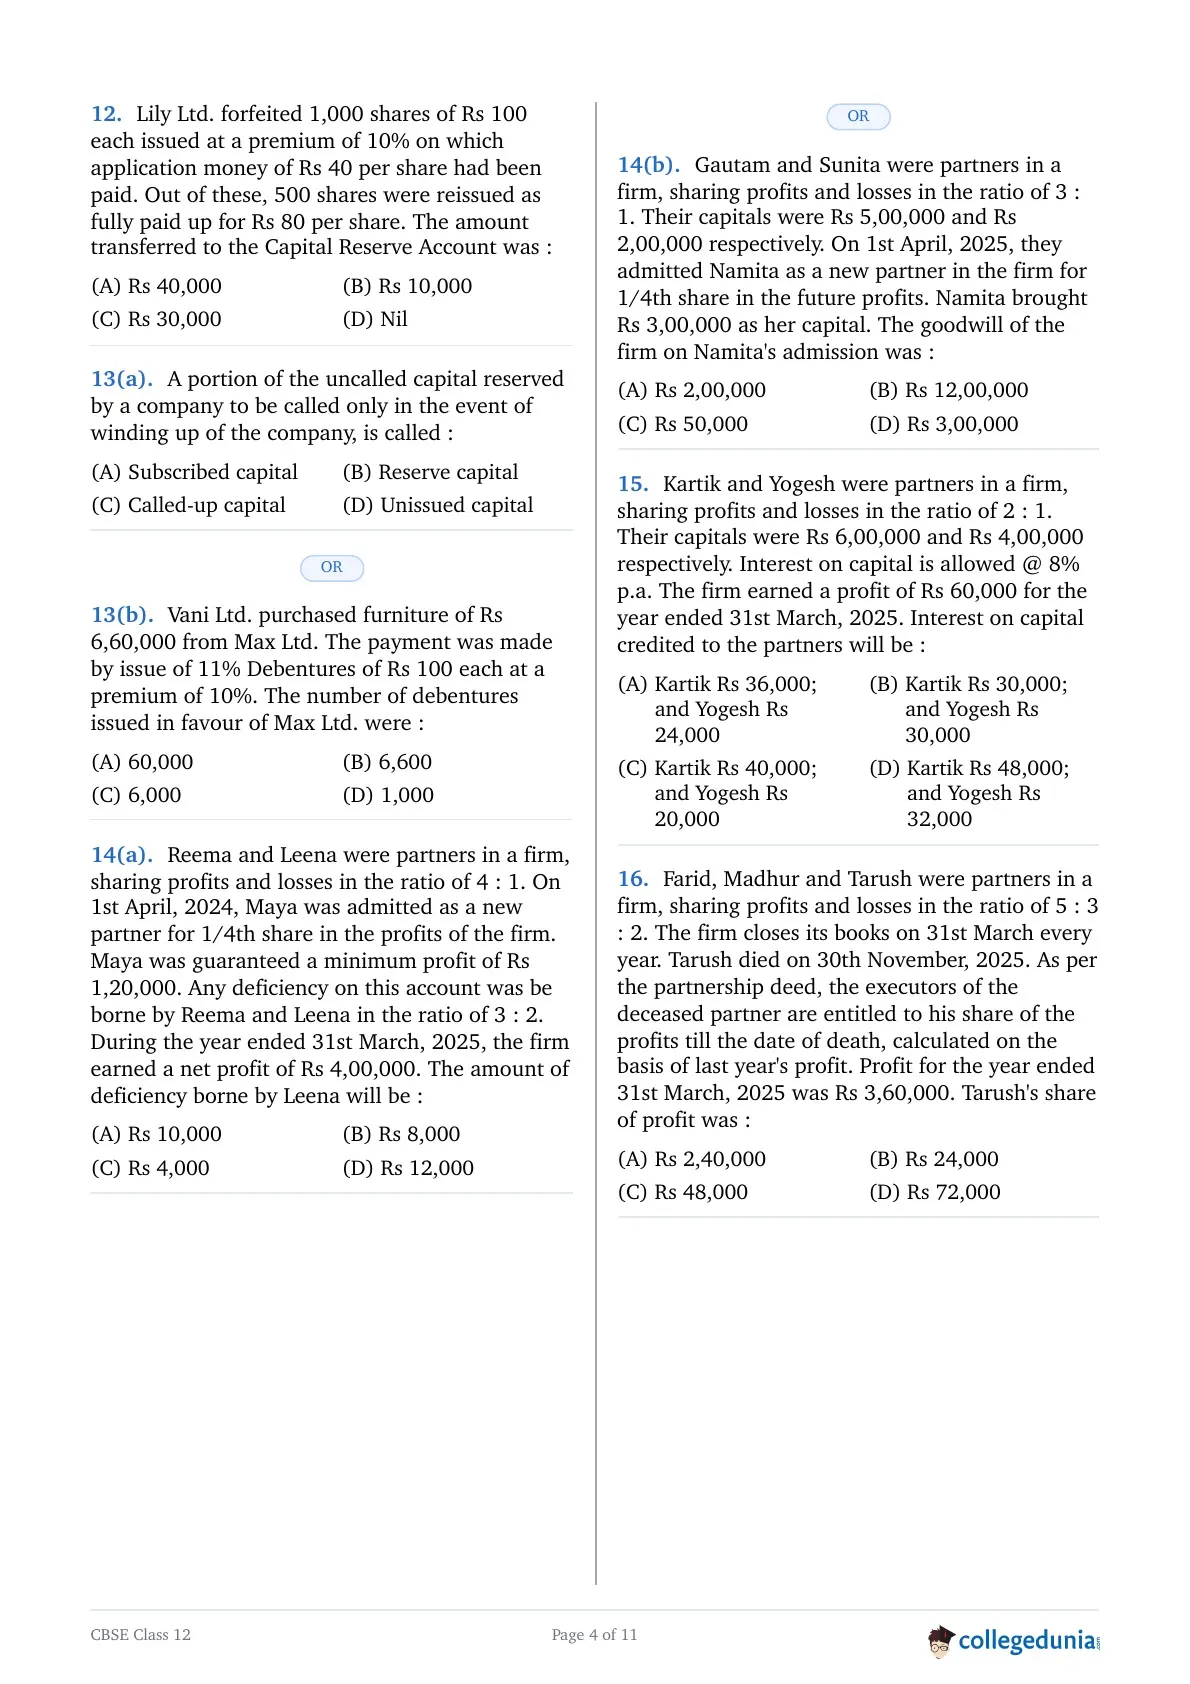
Lily Ltd. forfeited 1,000 shares of Rs 100 each issued at a premium of 10% on which application money of Rs 40 per share had been paid. Out of these, 500 shares were reissued as fully paid up for Rs 80 per share. The amount transferred to the Capital Reserve Account was :
A portion of the uncalled capital reserved by a company to be called only in the event of winding up of the company, is called :
Vani Ltd. purchased furniture of Rs 6,60,000 from Max Ltd. The payment was made by issue of 11% Debentures of Rs 100 each at a premium of 10%. The number of debentures issued in favour of Max Ltd. were :
Reema and Leena were partners in a firm, sharing profits and losses in the ratio of 4 : 1. On 1st April, 2024, Maya was admitted as a new partner for 1/4th share in the profits of the firm. Maya was guaranteed a minimum profit of Rs 1,20,000. Any deficiency on this account was be borne by Reema and Leena in the ratio of 3 : 2. During the year ended 31st March, 2025, the firm earned a net profit of Rs 4,00,000. The amount of deficiency borne by Leena will be :
Gautam and Sunita were partners in a firm, sharing profits and losses in the ratio of 3 : 1. Their capitals were Rs 5,00,000 and Rs 2,00,000 respectively. On 1st April, 2025, they admitted Namita as a new partner in the firm for 1/4th share in the future profits. Namita brought Rs 3,00,000 as her capital. The goodwill of the firm on Namita's admission was :
Kartik and Yogesh were partners in a firm, sharing profits and losses in the ratio of 2 : 1. Their capitals were Rs 6,00,000 and Rs 4,00,000 respectively. Interest on capital is allowed @ 8% p.a. The firm earned a profit of Rs 60,000 for the year ended 31st March, 2025. Interest on capital credited to the partners will be :
Farid, Madhur and Tarush were partners in a firm, sharing profits and losses in the ratio of 5 : 3 : 2. The firm closes its books on 31st March every year. Tarush died on 30th November, 2025. As per the partnership deed, the executors of the deceased partner are entitled to his share of the profits till the date of death, calculated on the basis of last year's profit. Profit for the year ended 31st March, 2025 was Rs 3,60,000. Tarush's share of profit was :
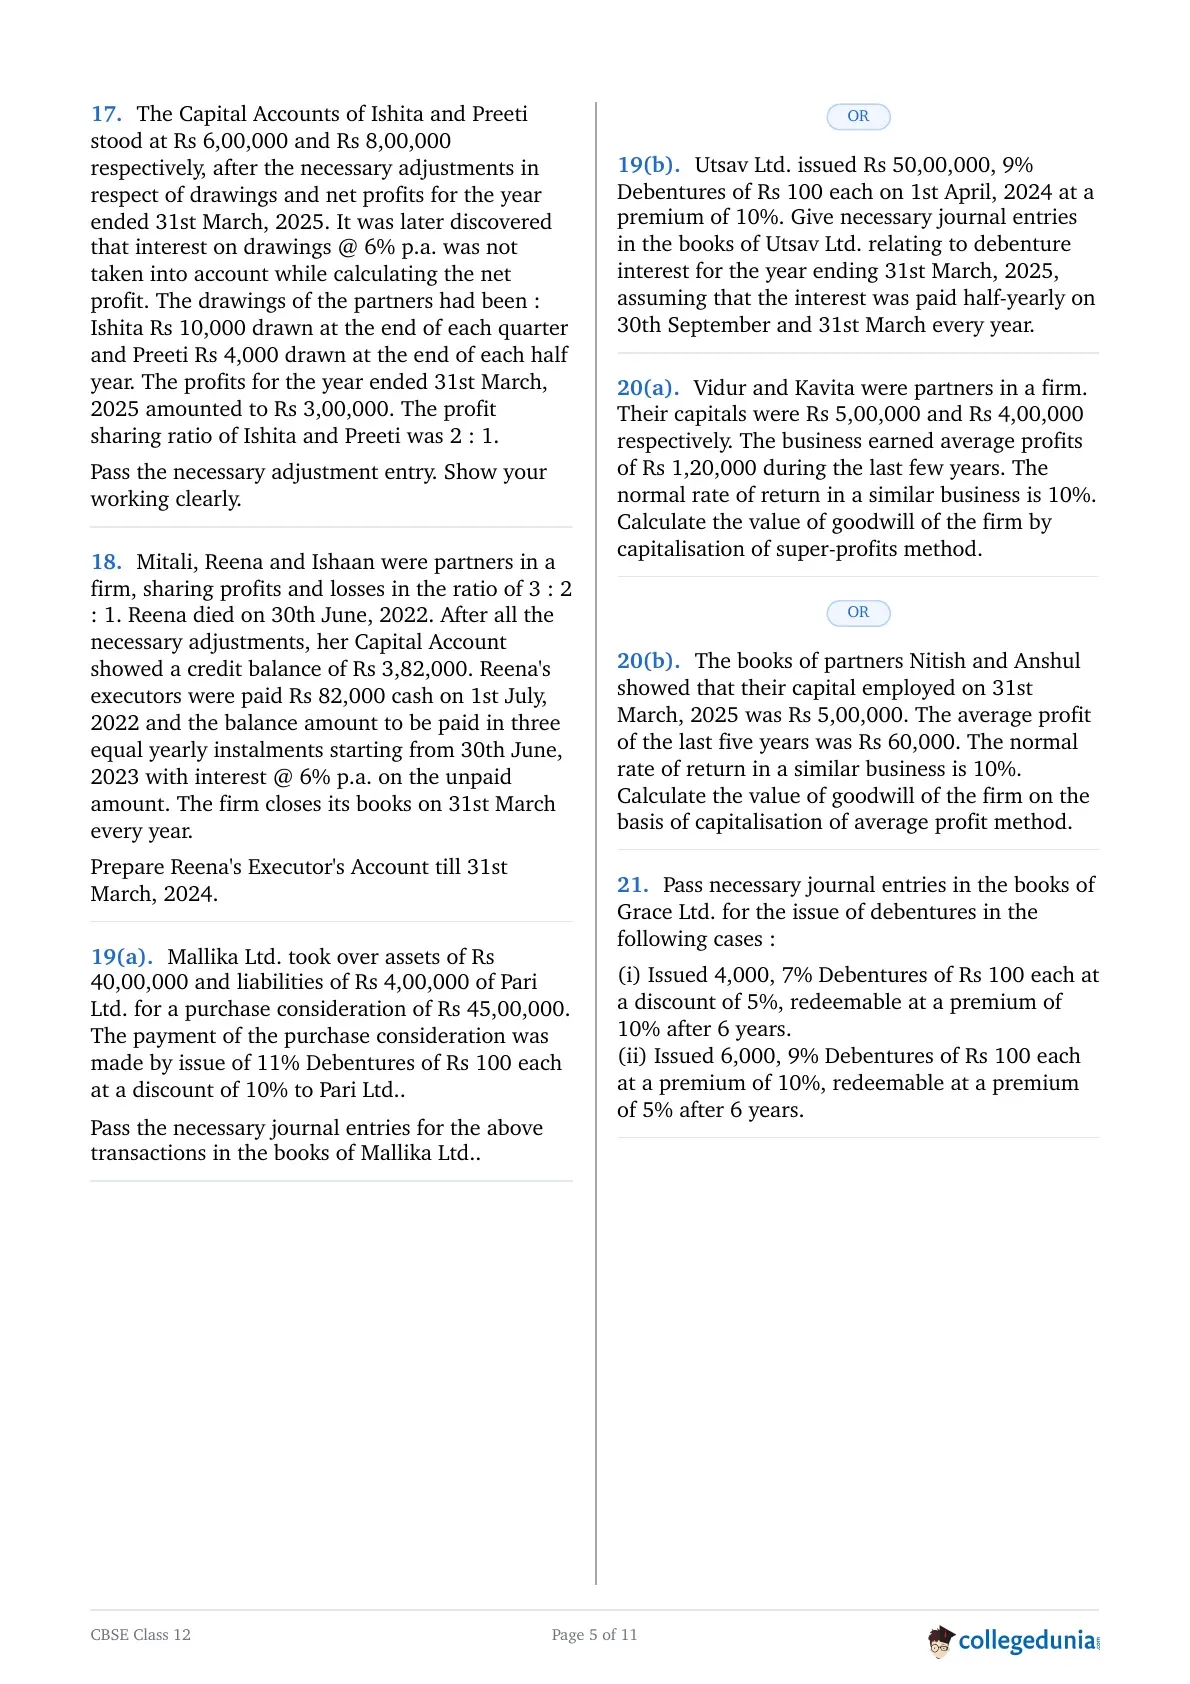
The Capital Accounts of Ishita and Preeti stood at Rs 6,00,000 and Rs 8,00,000 respectively, after the necessary adjustments in respect of drawings and net profits for the year ended 31st March, 2025. It was later discovered that interest on drawings @ 6% p.a. was not taken into account while calculating the net profit. The drawings of the partners had been : Ishita Rs 10,000 drawn at the end of each quarter and Preeti Rs 4,000 drawn at the end of each half year. The profits for the year ended 31st March, 2025 amounted to Rs 3,00,000. The profit sharing ratio of Ishita and Preeti was 2 : 1.
Pass the necessary adjustment entry. Show your working clearly.
Mitali, Reena and Ishaan were partners in a firm, sharing profits and losses in the ratio of 3 : 2 : 1. Reena died on 30th June, 2022. After all the necessary adjustments, her Capital Account showed a credit balance of Rs 3,82,000. Reena's executors were paid Rs 82,000 cash on 1st July, 2022 and the balance amount to be paid in three equal yearly instalments starting from 30th June, 2023 with interest @ 6% p.a. on the unpaid amount. The firm closes its books on 31st March every year.
Prepare Reena's Executor's Account till 31st March, 2024.
Mallika Ltd. took over assets of Rs 40,00,000 and liabilities of Rs 4,00,000 of Pari Ltd. for a purchase consideration of Rs 45,00,000. The payment of the purchase consideration was made by issue of 11% Debentures of Rs 100 each at a discount of 10% to Pari Ltd..
Pass the necessary journal entries for the above transactions in the books of Mallika Ltd..
Utsav Ltd. issued Rs 50,00,000, 9% Debentures of Rs 100 each on 1st April, 2024 at a premium of 10%. Give necessary journal entries in the books of Utsav Ltd. relating to debenture interest for the year ending 31st March, 2025, assuming that the interest was paid half-yearly on 30th September and 31st March every year.
Vidur and Kavita were partners in a firm. Their capitals were Rs 5,00,000 and Rs 4,00,000 respectively. The business earned average profits of Rs 1,20,000 during the last few years. The normal rate of return in a similar business is 10%. Calculate the value of goodwill of the firm by capitalisation of super-profits method.
The books of partners Nitish and Anshul showed that their capital employed on 31st March, 2025 was Rs 5,00,000. The average profit of the last five years was Rs 60,000. The normal rate of return in a similar business is 10%. Calculate the value of goodwill of the firm on the basis of capitalisation of average profit method.
Pass necessary journal entries in the books of Grace Ltd. for the issue of debentures in the following cases :
(i) Issued 4,000, 7% Debentures of Rs 100 each at a discount of 5%, redeemable at a premium of 10% after 6 years.
(ii) Issued 6,000, 9% Debentures of Rs 100 each at a premium of 10%, redeemable at a premium of 5% after 6 years.
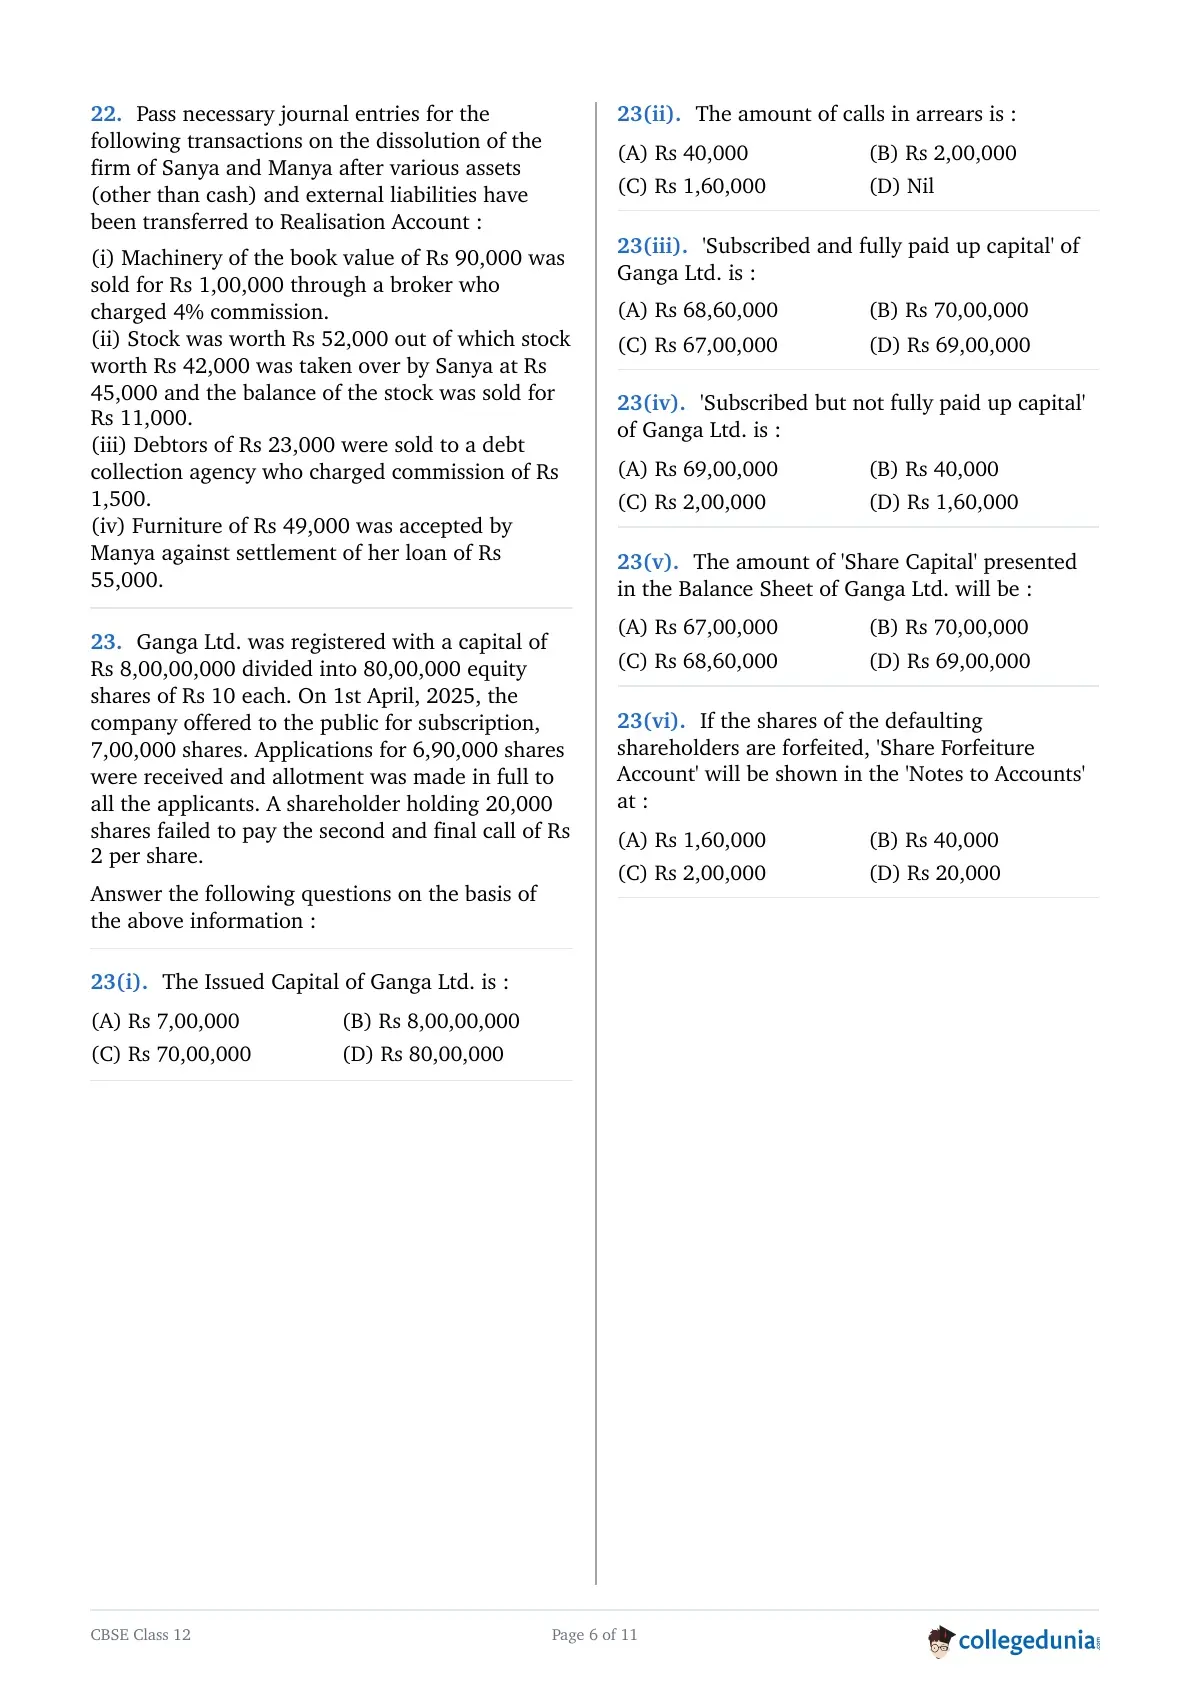
Pass necessary journal entries for the following transactions on the dissolution of the firm of Sanya and Manya after various assets (other than cash) and external liabilities have been transferred to Realisation Account :
(i) Machinery of the book value of Rs 90,000 was sold for Rs 1,00,000 through a broker who charged 4% commission.
(ii) Stock was worth Rs 52,000 out of which stock worth Rs 42,000 was taken over by Sanya at Rs 45,000 and the balance of the stock was sold for Rs 11,000.
(iii) Debtors of Rs 23,000 were sold to a debt collection agency who charged commission of Rs 1,500.
(iv) Furniture of Rs 49,000 was accepted by Manya against settlement of her loan of Rs 55,000.
Comprehension:
Ganga Ltd. was registered with a capital of Rs 8,00,00,000 divided into 80,00,000 equity shares of Rs 10 each. On 1st April, 2025, the company offered to the public for subscription, 7,00,000 shares. Applications for 6,90,000 shares were
Read More
received and allotment was made in full to all the applicants. A shareholder holding 20,000 shares failed to pay the second and final call of Rs 2 per share.Answer the following questions on the basis of the above information :
The amount of 'Share Capital' presented in the Balance Sheet of Ganga Ltd. will be :
If the shares of the defaulting shareholders are forfeited, 'Share Forfeiture Account' will be shown in the 'Notes to Accounts' at :
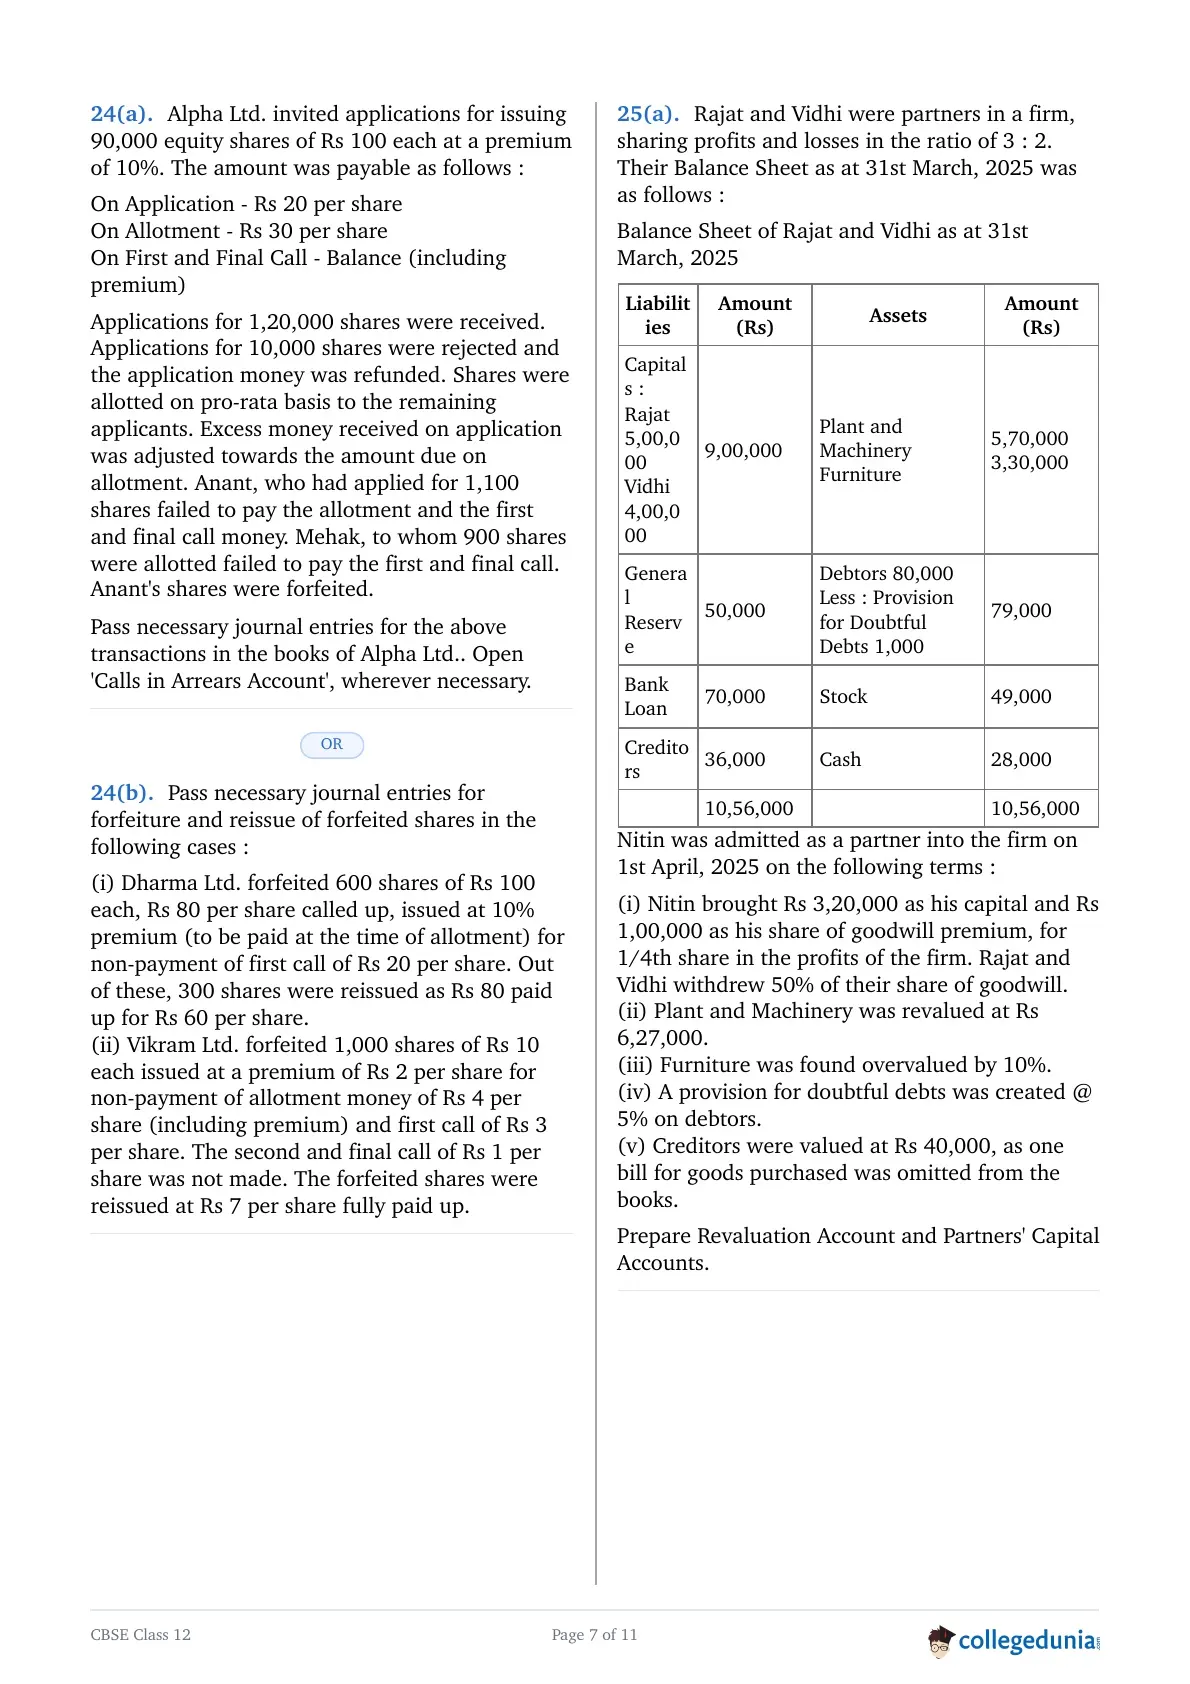
Alpha Ltd. invited applications for issuing 90,000 equity shares of Rs 100 each at a premium of 10%. The amount was payable as follows :
On Application - Rs 20 per share
On Allotment - Rs 30 per share
On First and Final Call - Balance (including premium)
Applications for 1,20,000 shares were received. Applications for 10,000 shares were rejected and the application money was refunded. Shares were allotted on pro-rata basis to the remaining applicants. Excess money received on application was adjusted towards the amount due on allotment. Anant, who had applied for 1,100 shares failed to pay the allotment and the first and final call money. Mehak, to whom 900 shares were allotted failed to pay the first and final call. Anant's shares were forfeited.
Pass necessary journal entries for the above transactions in the books of Alpha Ltd.. Open 'Calls in Arrears Account', wherever necessary.
Pass necessary journal entries for forfeiture and reissue of forfeited shares in the following cases :
(i) Dharma Ltd. forfeited 600 shares of Rs 100 each, Rs 80 per share called up, issued at 10% premium (to be paid at the time of allotment) for non-payment of first call of Rs 20 per share. Out of these, 300 shares were reissued as Rs 80 paid up for Rs 60 per share.
(ii) Vikram Ltd. forfeited 1,000 shares of Rs 10 each issued at a premium of Rs 2 per share for non-payment of allotment money of Rs 4 per share (including premium) and first call of Rs 3 per share. The second and final call of Rs 1 per share was not made. The forfeited shares were reissued at Rs 7 per share fully paid up.
Rajat and Vidhi were partners in a firm, sharing profits and losses in the ratio of 3 : 2. Their Balance Sheet as at 31st March, 2025 was as follows :
Balance Sheet of Rajat and Vidhi as at 31st March, 2025
| Liabilities | Amount (Rs) | Assets | Amount (Rs) |
|---|---|---|---|
| Capitals : Rajat 5,00,000 Vidhi 4,00,000 | 9,00,000 | Plant and Machinery Furniture | 5,70,000 3,30,000 |
| General Reserve | 50,000 | Debtors 80,000 Less : Provision for Doubtful Debts 1,000 | 79,000 |
| Bank Loan | 70,000 | Stock | 49,000 |
| Creditors | 36,000 | Cash | 28,000 |
| 10,56,000 | 10,56,000 |
Nitin was admitted as a partner into the firm on 1st April, 2025 on the following terms :
(i) Nitin brought Rs 3,20,000 as his capital and Rs 1,00,000 as his share of goodwill premium, for 1/4th share in the profits of the firm. Rajat and Vidhi withdrew 50% of their share of goodwill.
(ii) Plant and Machinery was revalued at Rs 6,27,000.
(iii) Furniture was found overvalued by 10%.
(iv) A provision for doubtful debts was created @ 5% on debtors.
(v) Creditors were valued at Rs 40,000, as one bill for goods purchased was omitted from the books.
Prepare Revaluation Account and Partners' Capital Accounts.
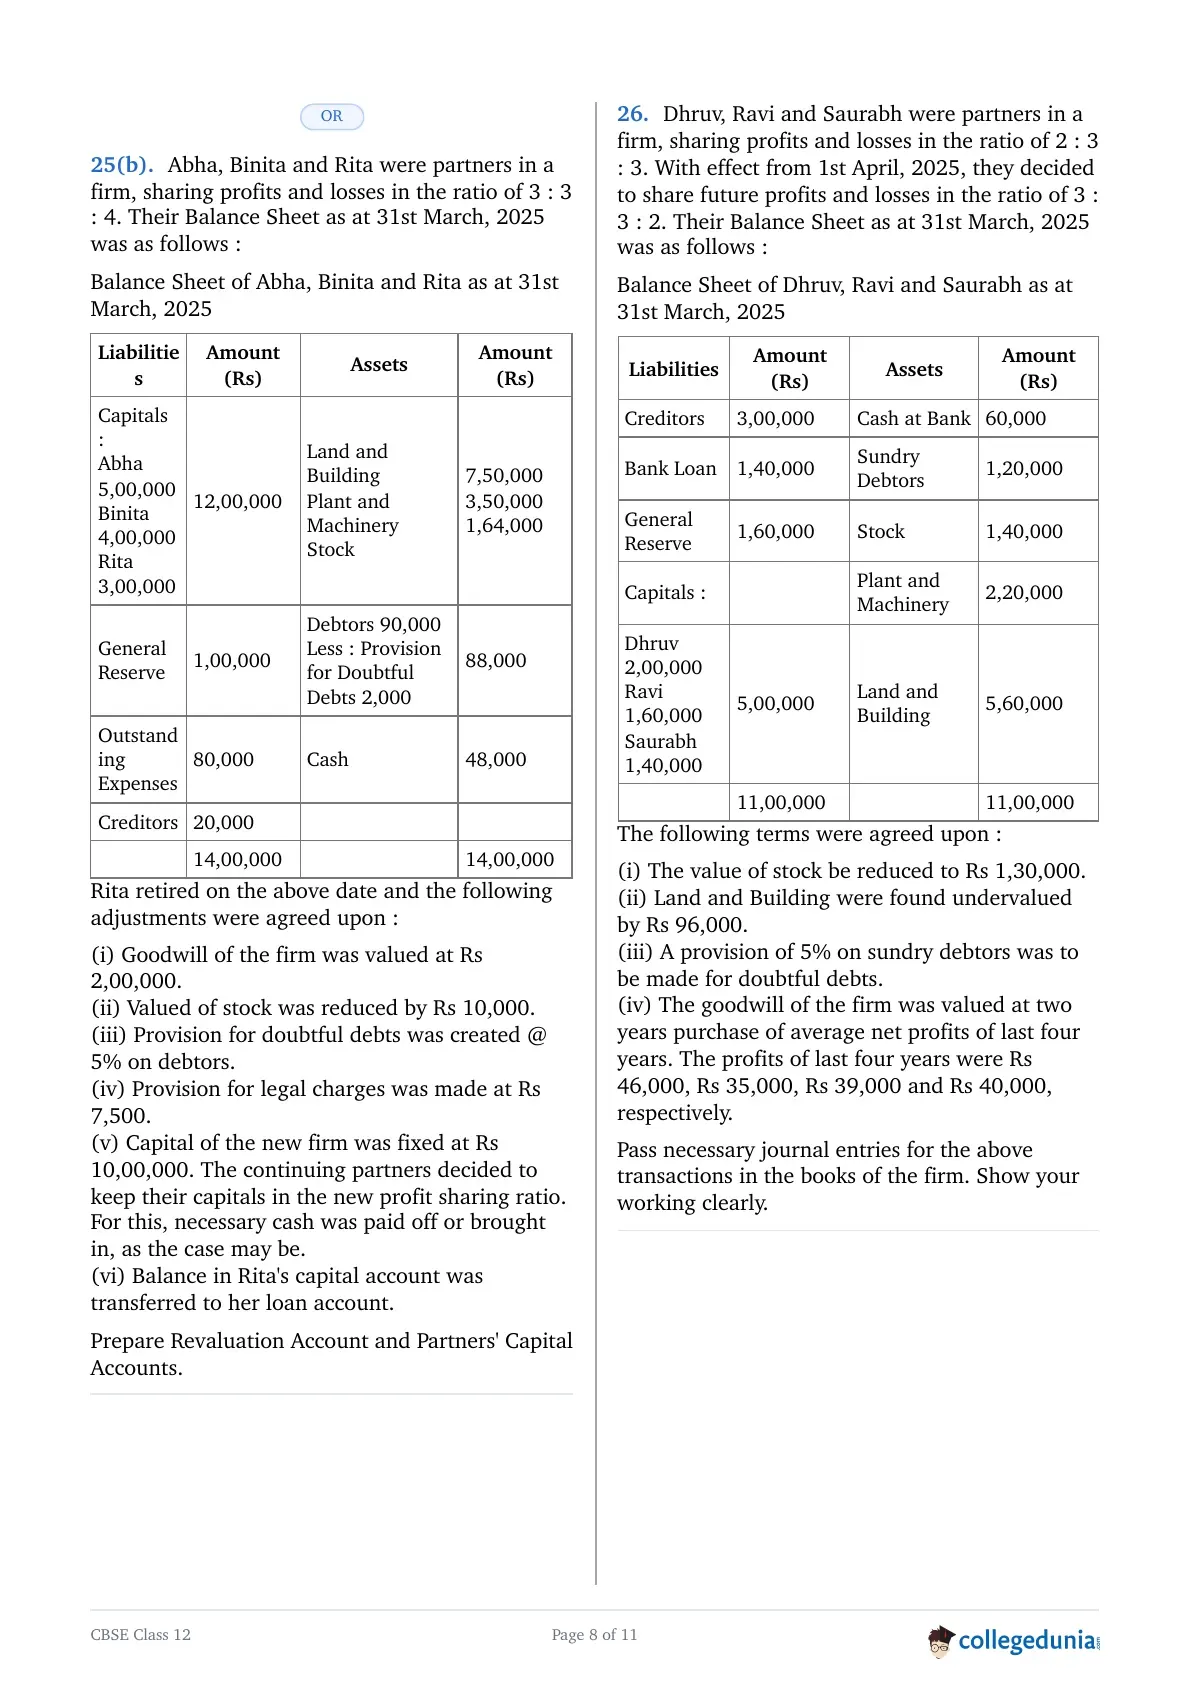
Abha, Binita and Rita were partners in a firm, sharing profits and losses in the ratio of 3 : 3 : 4. Their Balance Sheet as at 31st March, 2025 was as follows :
Balance Sheet of Abha, Binita and Rita as at 31st March, 2025
| Liabilities | Amount (Rs) | Assets | Amount (Rs) |
|---|---|---|---|
| Capitals : Abha 5,00,000 Binita 4,00,000 Rita 3,00,000 | 12,00,000 | Land and Building Plant and Machinery Stock | 7,50,000 3,50,000 1,64,000 |
| General Reserve | 1,00,000 | Debtors 90,000 Less : Provision for Doubtful Debts 2,000 | 88,000 |
| Outstanding Expenses | 80,000 | Cash | 48,000 |
| Creditors | 20,000 | ||
| 14,00,000 | 14,00,000 |
Rita retired on the above date and the following adjustments were agreed upon :
(i) Goodwill of the firm was valued at Rs 2,00,000.
(ii) Valued of stock was reduced by Rs 10,000.
(iii) Provision for doubtful debts was created @ 5% on debtors.
(iv) Provision for legal charges was made at Rs 7,500.
(v) Capital of the new firm was fixed at Rs 10,00,000. The continuing partners decided to keep their capitals in the new profit sharing ratio. For this, necessary cash was paid off or brought in, as the case may be.
(vi) Balance in Rita's capital account was transferred to her loan account.
Prepare Revaluation Account and Partners' Capital Accounts.
Dhruv, Ravi and Saurabh were partners in a firm, sharing profits and losses in the ratio of 2 : 3 : 3. With effect from 1st April, 2025, they decided to share future profits and losses in the ratio of 3 : 3 : 2. Their Balance Sheet as at 31st March, 2025 was as follows :
Balance Sheet of Dhruv, Ravi and Saurabh as at 31st March, 2025
| Liabilities | Amount (Rs) | Assets | Amount (Rs) |
|---|---|---|---|
| Creditors | 3,00,000 | Cash at Bank | 60,000 |
| Bank Loan | 1,40,000 | Sundry Debtors | 1,20,000 |
| General Reserve | 1,60,000 | Stock | 1,40,000 |
| Capitals : | Plant and Machinery | 2,20,000 | |
| Dhruv 2,00,000 Ravi 1,60,000 Saurabh 1,40,000 | 5,00,000 | Land and Building | 5,60,000 |
| 11,00,000 | 11,00,000 |
The following terms were agreed upon :
(i) The value of stock be reduced to Rs 1,30,000.
(ii) Land and Building were found undervalued by Rs 96,000.
(iii) A provision of 5% on sundry debtors was to be made for doubtful debts.
(iv) The goodwill of the firm was valued at two years purchase of average net profits of last four years. The profits of last four years were Rs 46,000, Rs 35,000, Rs 39,000 and Rs 40,000, respectively.
Pass necessary journal entries for the above transactions in the books of the firm. Show your working clearly.
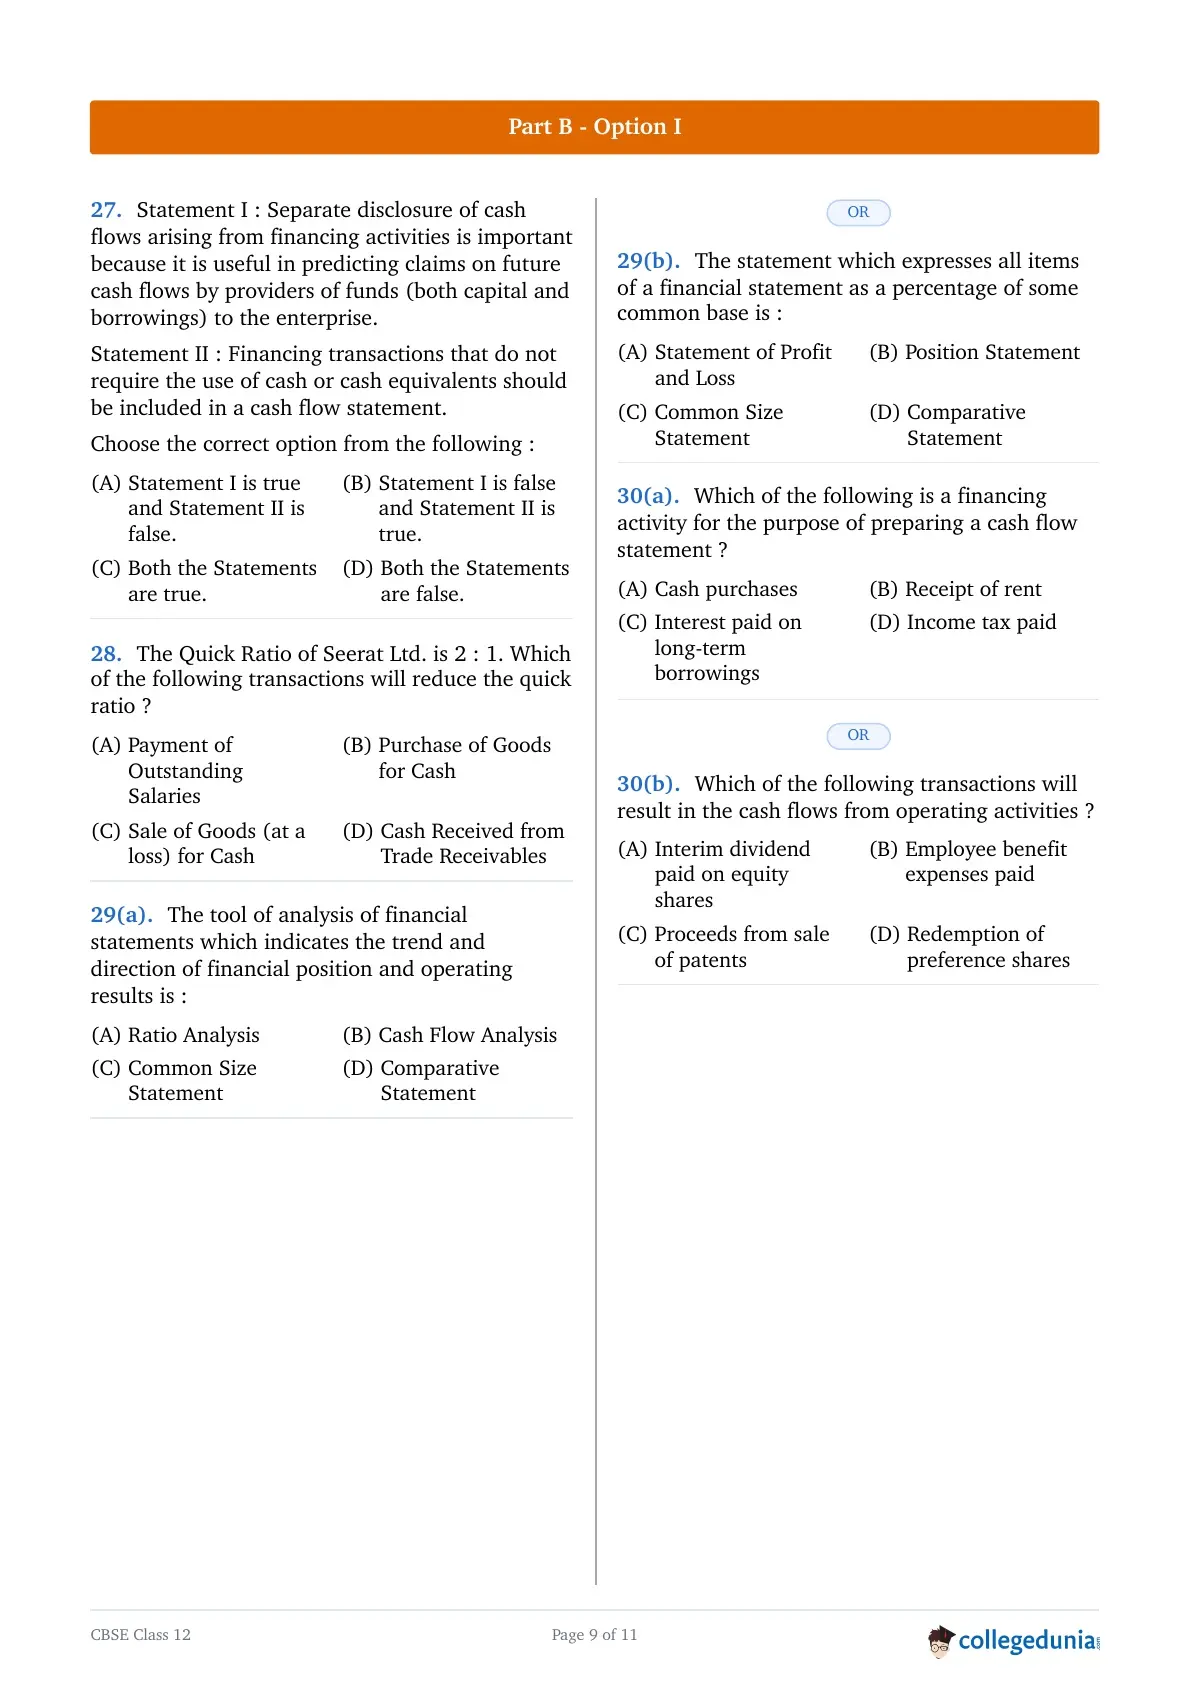
Statement I : Separate disclosure of cash flows arising from financing activities is important because it is useful in predicting claims on future cash flows by providers of funds (both capital and borrowings) to the enterprise.
Statement II : Financing transactions that do not require the use of cash or cash equivalents should be included in a cash flow statement.
Choose the correct option from the following :
The Quick Ratio of Seerat Ltd. is 2 : 1. Which of the following transactions will reduce the quick ratio ?
The tool of analysis of financial statements which indicates the trend and direction of financial position and operating results is :
The statement which expresses all items of a financial statement as a percentage of some common base is :
Which of the following is a financing activity for the purpose of preparing a cash flow statement ?
Which of the following transactions will result in the cash flows from operating activities ?
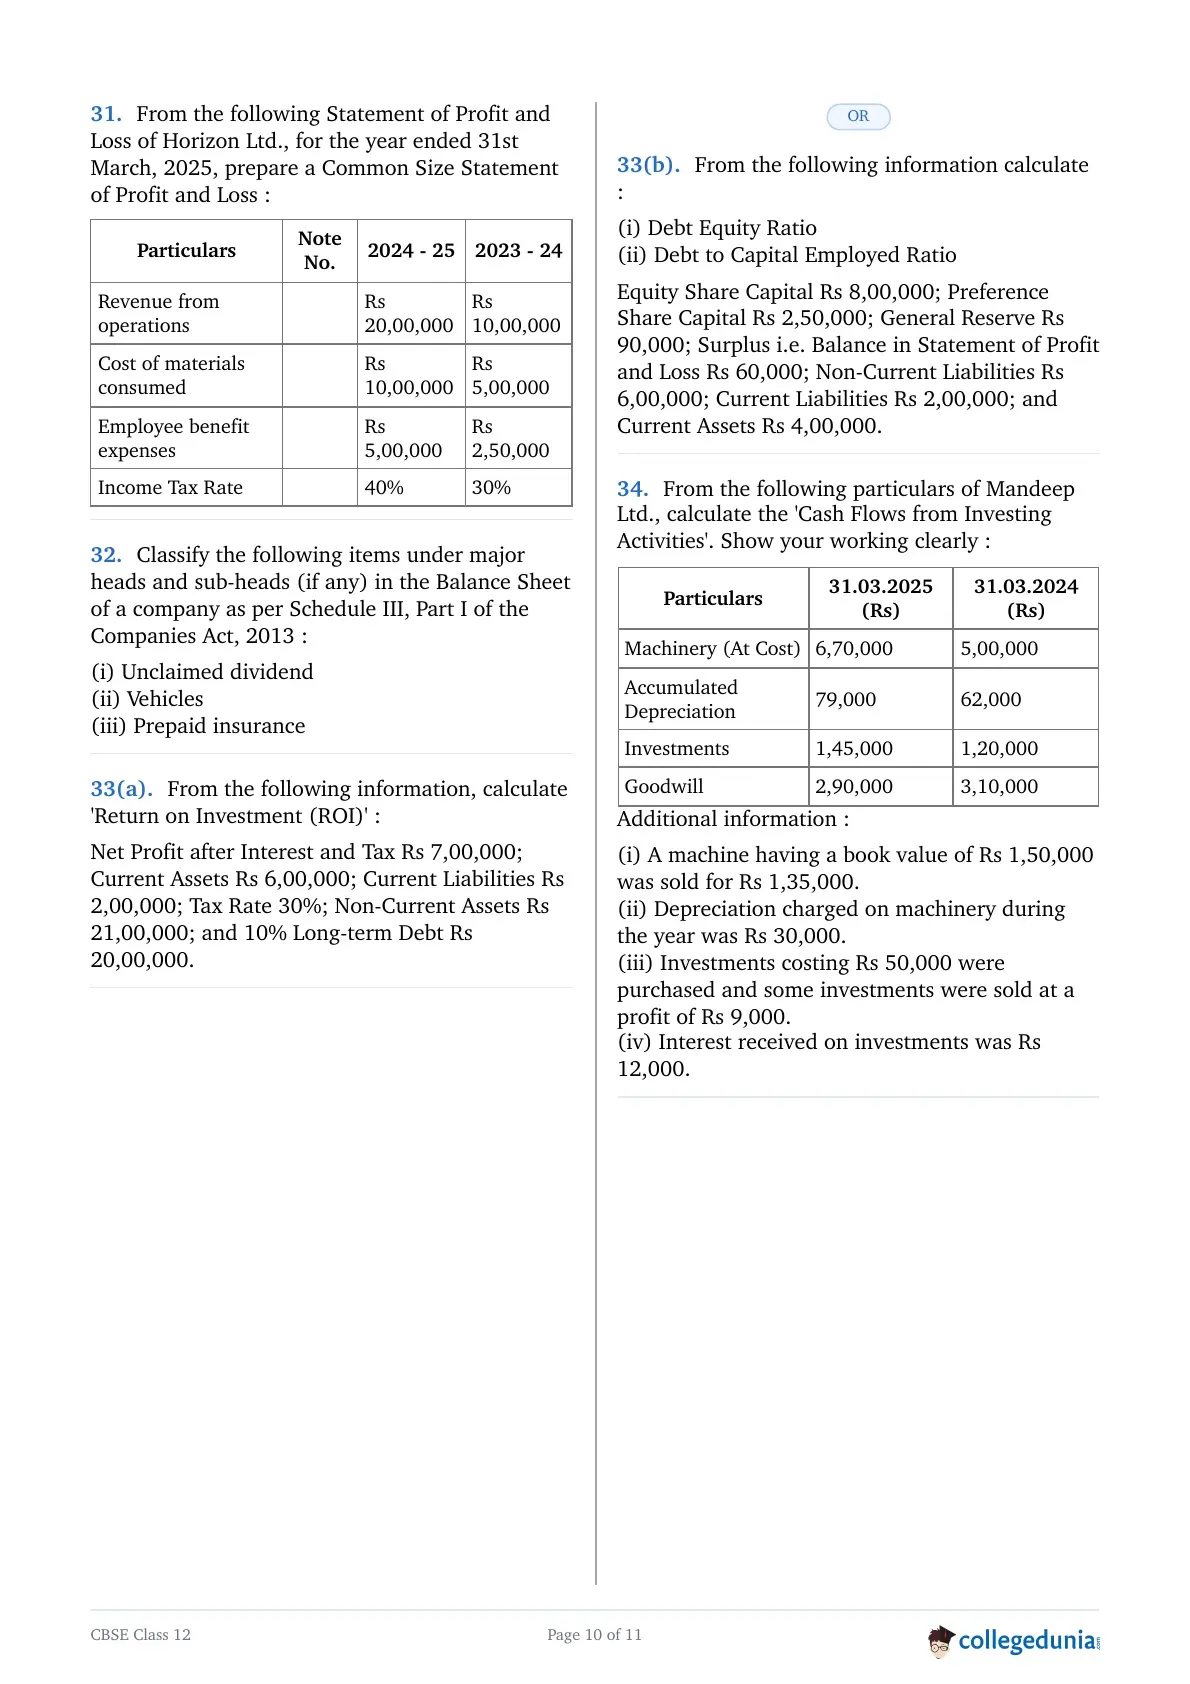
From the following Statement of Profit and Loss of Horizon Ltd., for the year ended 31st March, 2025, prepare a Common Size Statement of Profit and Loss :
| Particulars | Note No. | 2024 - 25 | 2023 - 24 |
|---|---|---|---|
| Revenue from operations | Rs 20,00,000 | Rs 10,00,000 | |
| Cost of materials consumed | Rs 10,00,000 | Rs 5,00,000 | |
| Employee benefit expenses | Rs 5,00,000 | Rs 2,50,000 | |
| Income Tax Rate | 40% | 30% |
Classify the following items under major heads and sub-heads (if any) in the Balance Sheet of a company as per Schedule III, Part I of the Companies Act, 2013 :
(i) Unclaimed dividend
(ii) Vehicles
(iii) Prepaid insurance
From the following information, calculate 'Return on Investment (ROI)' :
Net Profit after Interest and Tax Rs 7,00,000; Current Assets Rs 6,00,000; Current Liabilities Rs 2,00,000; Tax Rate 30%; Non-Current Assets Rs 21,00,000; and 10% Long-term Debt Rs 20,00,000.
From the following information calculate :
(i) Debt Equity Ratio
(ii) Debt to Capital Employed Ratio
Equity Share Capital Rs 8,00,000; Preference Share Capital Rs 2,50,000; General Reserve Rs 90,000; Surplus i.e. Balance in Statement of Profit and Loss Rs 60,000; Non-Current Liabilities Rs 6,00,000; Current Liabilities Rs 2,00,000; and Current Assets Rs 4,00,000.
From the following particulars of Mandeep Ltd., calculate the 'Cash Flows from Investing Activities'. Show your working clearly :
| Particulars | 31.03.2025 (Rs) | 31.03.2024 (Rs) |
|---|---|---|
| Machinery (At Cost) | 6,70,000 | 5,00,000 |
| Accumulated Depreciation | 79,000 | 62,000 |
| Investments | 1,45,000 | 1,20,000 |
| Goodwill | 2,90,000 | 3,10,000 |
Additional information :
(i) A machine having a book value of Rs 1,50,000 was sold for Rs 1,35,000.
(ii) Depreciation charged on machinery during the year was Rs 30,000.
(iii) Investments costing Rs 50,000 were purchased and some investments were sold at a profit of Rs 9,000.
(iv) Interest received on investments was Rs 12,000.
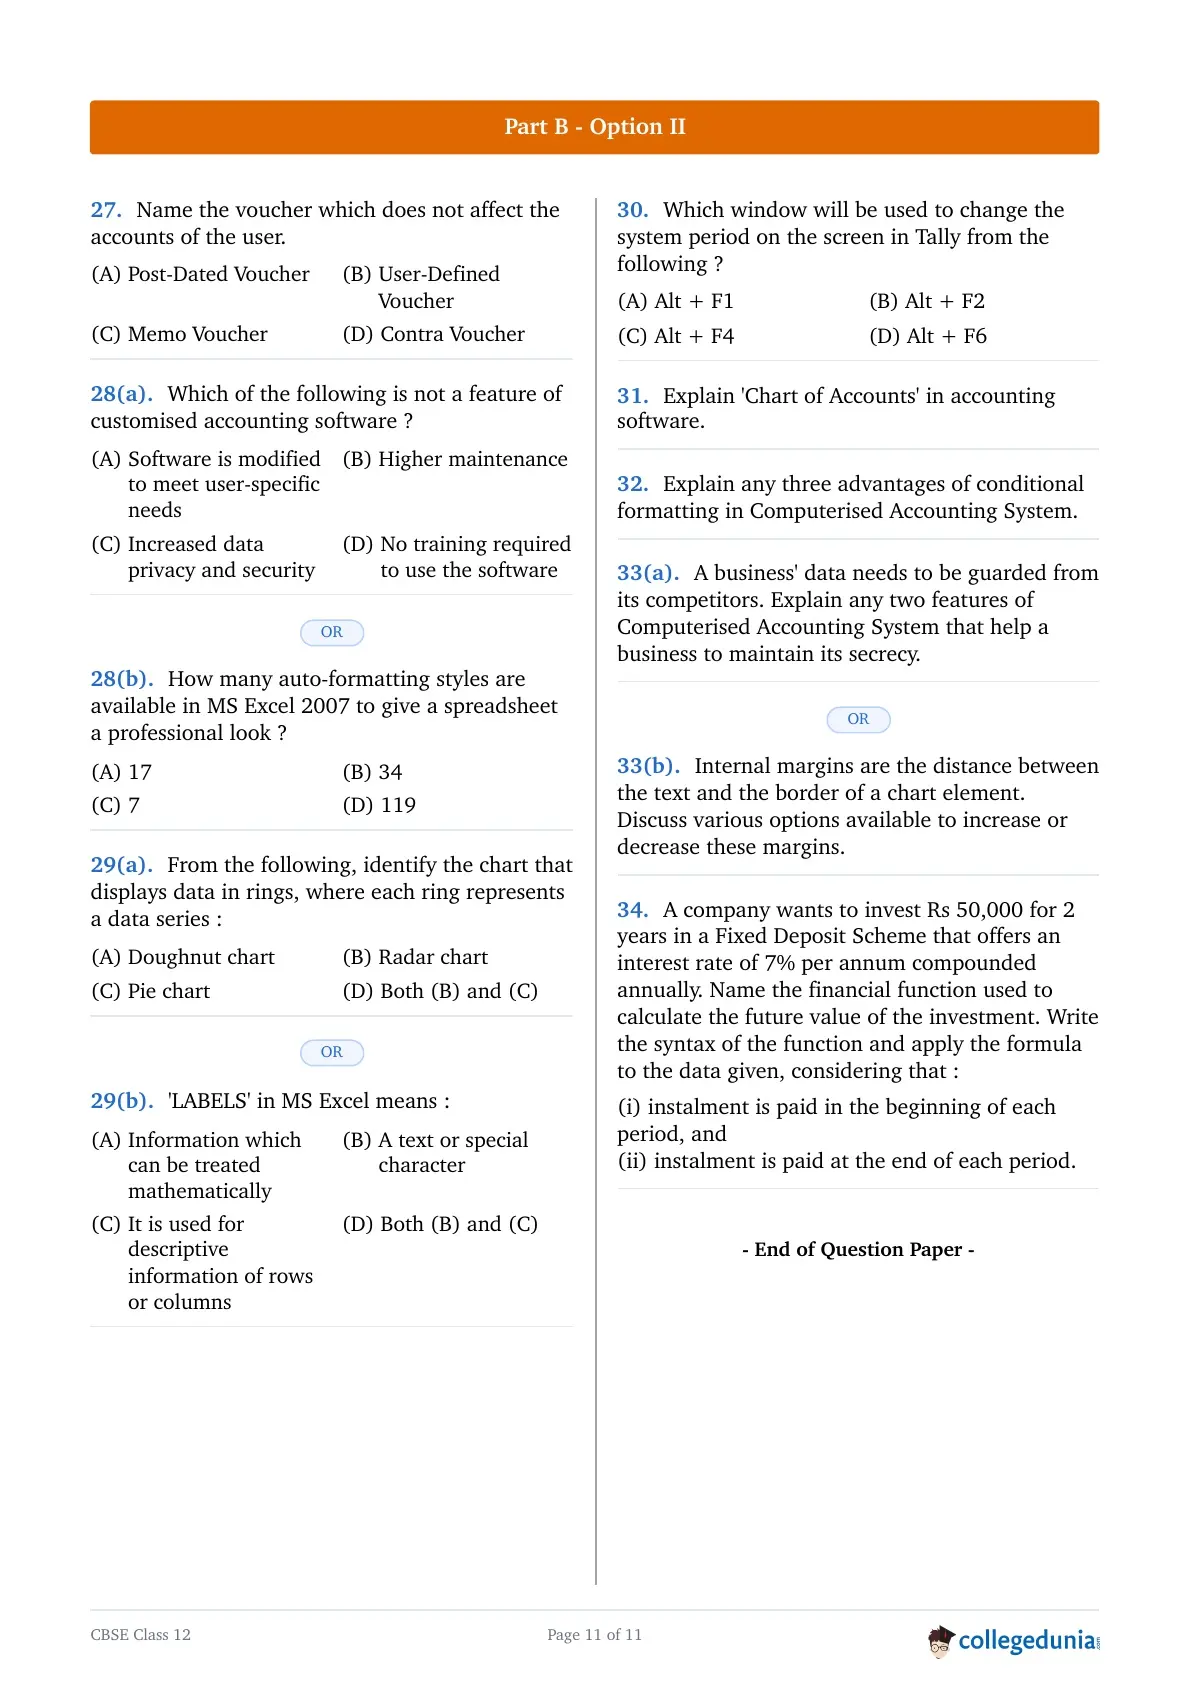
Name the voucher which does not affect the accounts of the user.
Which of the following is not a feature of customised accounting software ?
How many auto-formatting styles are available in MS Excel 2007 to give a spreadsheet a professional look ?
From the following, identify the chart that displays data in rings, where each ring represents a data series :
Which window will be used to change the system period on the screen in Tally from the following ?
Explain any three advantages of conditional formatting in Computerised Accounting System.
A business' data needs to be guarded from its competitors. Explain any two features of Computerised Accounting System that help a business to maintain its secrecy.
Internal margins are the distance between the text and the border of a chart element. Discuss various options available to increase or decrease these margins.
A company wants to invest Rs 50,000 for 2 years in a Fixed Deposit Scheme that offers an interest rate of 7% per annum compounded annually. Name the financial function used to calculate the future value of the investment. Write the syntax of the function and apply the formula to the data given, considering that :
(i) instalment is paid in the beginning of each period, and
(ii) instalment is paid at the end of each period.
CBSE Class 12 Accountancy Compartment 2026 Set 3 - (67/7/3) Exam Pattern and Marking Scheme
| Part | Questions | Question Type | Marks per Question | Marks |
|---|---|---|---|---|
| A | Q1 - Q16 | Multiple choice questions | 1 | 16 |
| A | Q17 - Q20 | Short answer type | 3 | 12 |
| A | Q21 - Q22 | Long answer type-I | 4 | 8 |
| A | Q23 - Q26 | Long answer type-II | 6 | 24 |
| B | Q27 - Q30 | Multiple choice questions | 1 | 4 |
| B | Q31 - Q32 | Short answer type | 3 | 6 |
| B | Q33 | Long answer type-I | 4 | 4 |
| B | Q34 | Long answer type-II | 6 | 6 |
| Total | 34 questions | 80 |
CBSE Class 12 Accountancy Compartment 2026 Set 3 - (67/7/3) Question Paper FAQs
Ques. How many questions are there in the Accountancy Compartment 2026 paper (Set 3 - 67/7/3)?
Ans. The paper has 34 questions in Part A and Part B, and all questions are compulsory.
Ques. How are the marks divided?
Ans. Part A carries 60 marks and Part B carries 20 marks, for a total of 80 marks.
Ques. Is there any choice in the paper?
Ans. There is no overall choice. An internal choice is given in a few questions in each part, and Part B has two options (Analysis of Financial Statements or Computerised Accounting), of which only one has to be attempted.
Ques. How much time is given for the CBSE Class 12 Accountancy Compartment 2026 paper?
Ans. The paper is of 3 hours (10:30 AM to 1:30 PM). The question paper is distributed at 10:15 AM and candidates get 15 minutes to read it before they start writing.
Ques. When was the CBSE Class 12 Accountancy Compartment 2026 exam held?
Ans. The Class 12 compartment (supplementary) paper of Accountancy was held on July 28, 2026.
Ques. Where can I get the official CBSE Class 12 Accountancy Compartment question paper?
Ans. The official question papers are published on the CBSE website, cbse.gov.in.


Comments