

CUET 2026 May 20 Shift 1 Accountancy Question Paper is available for download here. NTA conducted the CUET 2026 exam from 11th May to 31st May.
The CUET 2026 Accountancy question paper includes the following:
- 55 questions in the paper, of which 50 are to be attempted in 60 minutes
- Section A (Accountancy Core), Q1 - Q45: 45 compulsory questions, 225 marks
- Section B (attempt one of the two), 25 marks: B1 Analysis of Financial Statements (Q46 - Q50) or B2 Computerized Accounting Systems (Q51 - Q55), 5 questions each
- Marking: +5 for a correct answer, -1 for an incorrect answer, 0 for an unattempted question
- Maximum marks: 250
CUET 2026 Accountancy May 20 Shift 1 Question Paper with Solution PDF
| NTA Official PDF | CD PDF | CD PDF with Solutions |
|---|---|---|
| Download official PDF 7.81 MB | Download Collegedunia PDF 0.41 MB | Download solutions PDF 0.36 MB |
Also Check:
- CUET 2027 Latest Updates
- Download CUET UG Previous Year Papers for free
- CUET 2026 May 20 Shift 1 Accountancy Answer Key
- CUET UG 2026 Accountancy Marks vs Expected Percentile and Colleges
CUET 2026 Accountancy May 20 Shift 1 Questions with Solutions
Section A - Accountancy Core (Q1 - Q45)
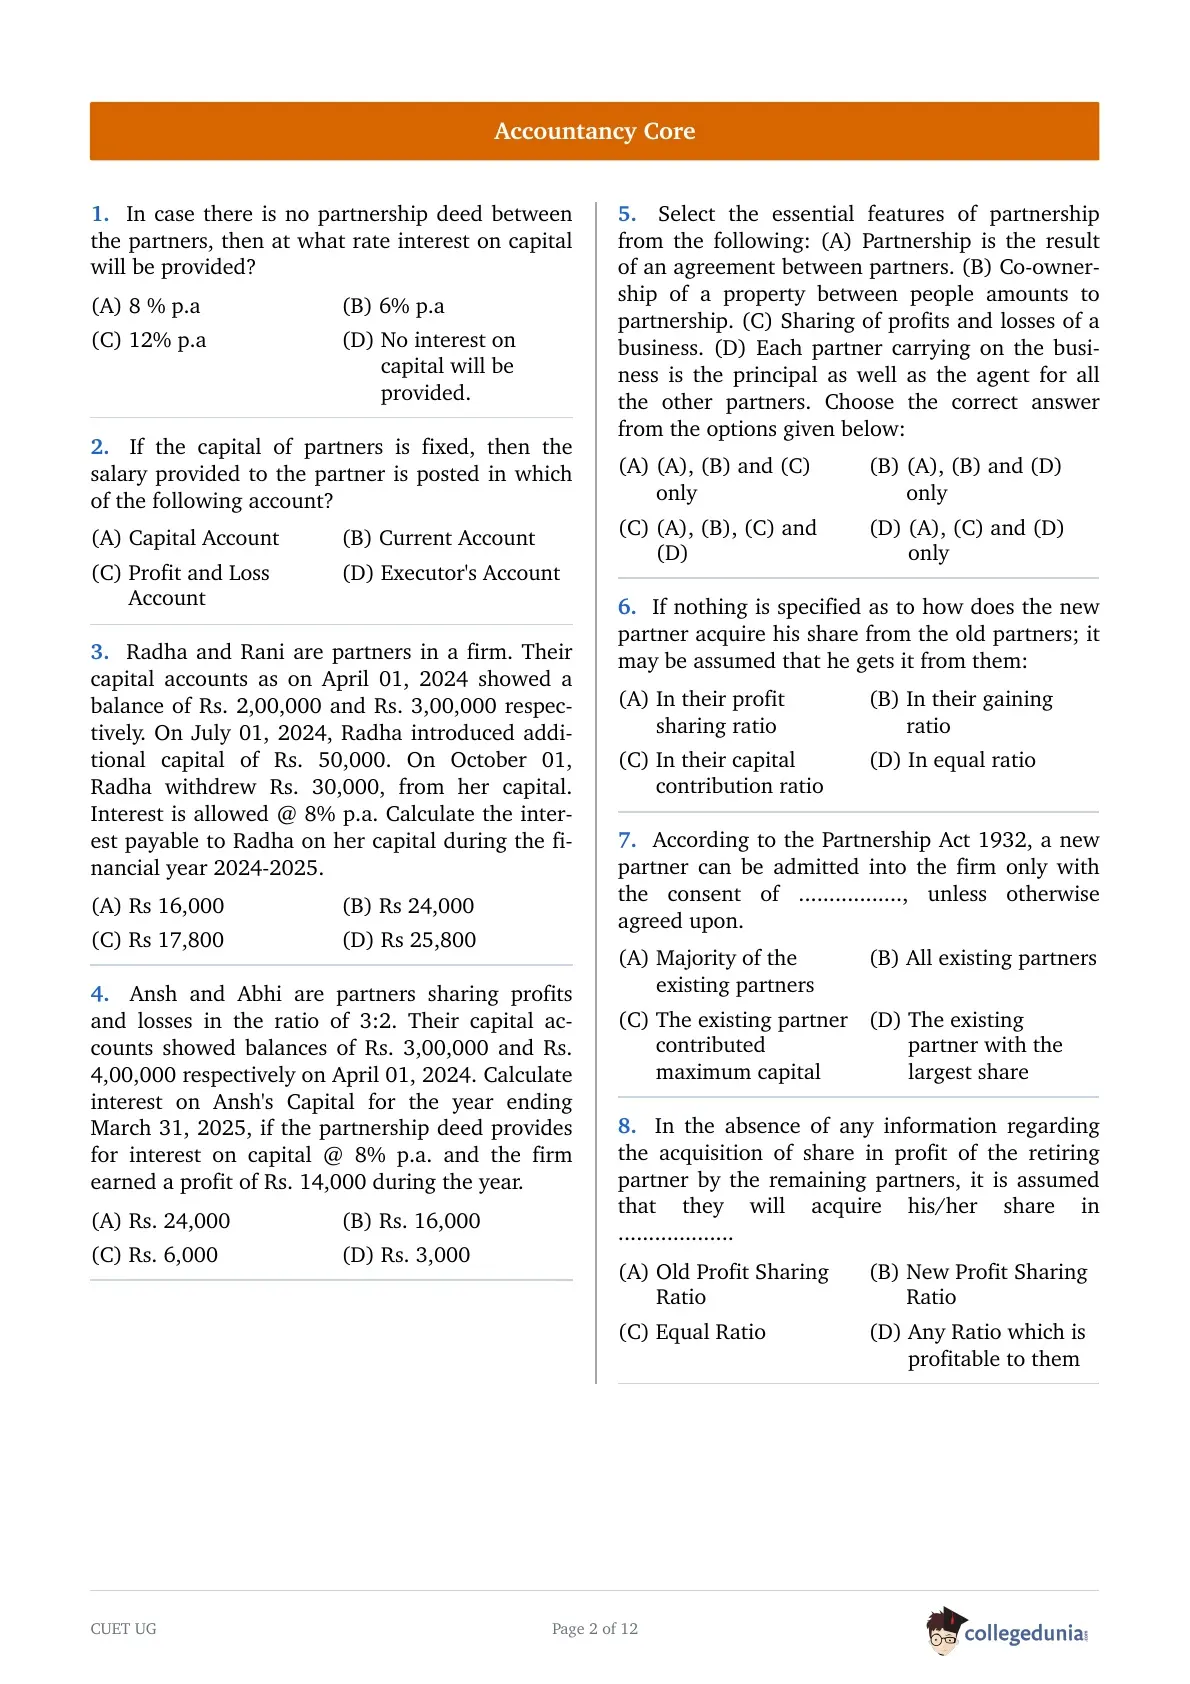
In case there is no partnership deed between the partners, then at what rate interest on capital will be provided?
If the capital of partners is fixed, then the salary provided to the partner is posted in which of the following account?
Radha and Rani are partners in a firm. Their capital accounts as on April 01, 2024 showed a balance of Rs. 2,00,000 and Rs. 3,00,000 respectively. On July 01, 2024, Radha introduced additional capital of Rs. 50,000. On October 01, Radha withdrew Rs. 30,000, from her capital. Interest is allowed @ 8% p.a. Calculate the interest payable to Radha on her capital during the financial year 2024-2025.
Ansh and Abhi are partners sharing profits and losses in the ratio of 3 : 2. Their capital accounts showed balances of Rs. 3,00,000 and Rs. 4,00,000 respectively on April 01, 2024. Calculate interest on Ansh's Capital for the year ending March 31, 2025, if the partnership deed provides for interest on capital @ 8% p.a. and the firm earned a profit of Rs. 14,000 during the year.
Select the essential features of partnership from the following:
(A) Partnership is the result of an agreement between partners.
(B) Co-ownership of a property between people amounts to partnership.
(C) Sharing of profits and losses of a business.
(D) Each partner carrying on the business is the principal as well as the agent for all the other partners.
Choose the correct answer from the options given below:
If nothing is specified as to how does the new partner acquire his share from the old partners; it may be assumed that he gets it from them:
According to the Partnership Act 1932, a new partner can be admitted into the firm only with the consent of ................, unless otherwise agreed upon.
In the absence of any information regarding the acquisition of share in profit of the retiring partner by the remaining partners, it is assumed that they will acquire his/her share in .
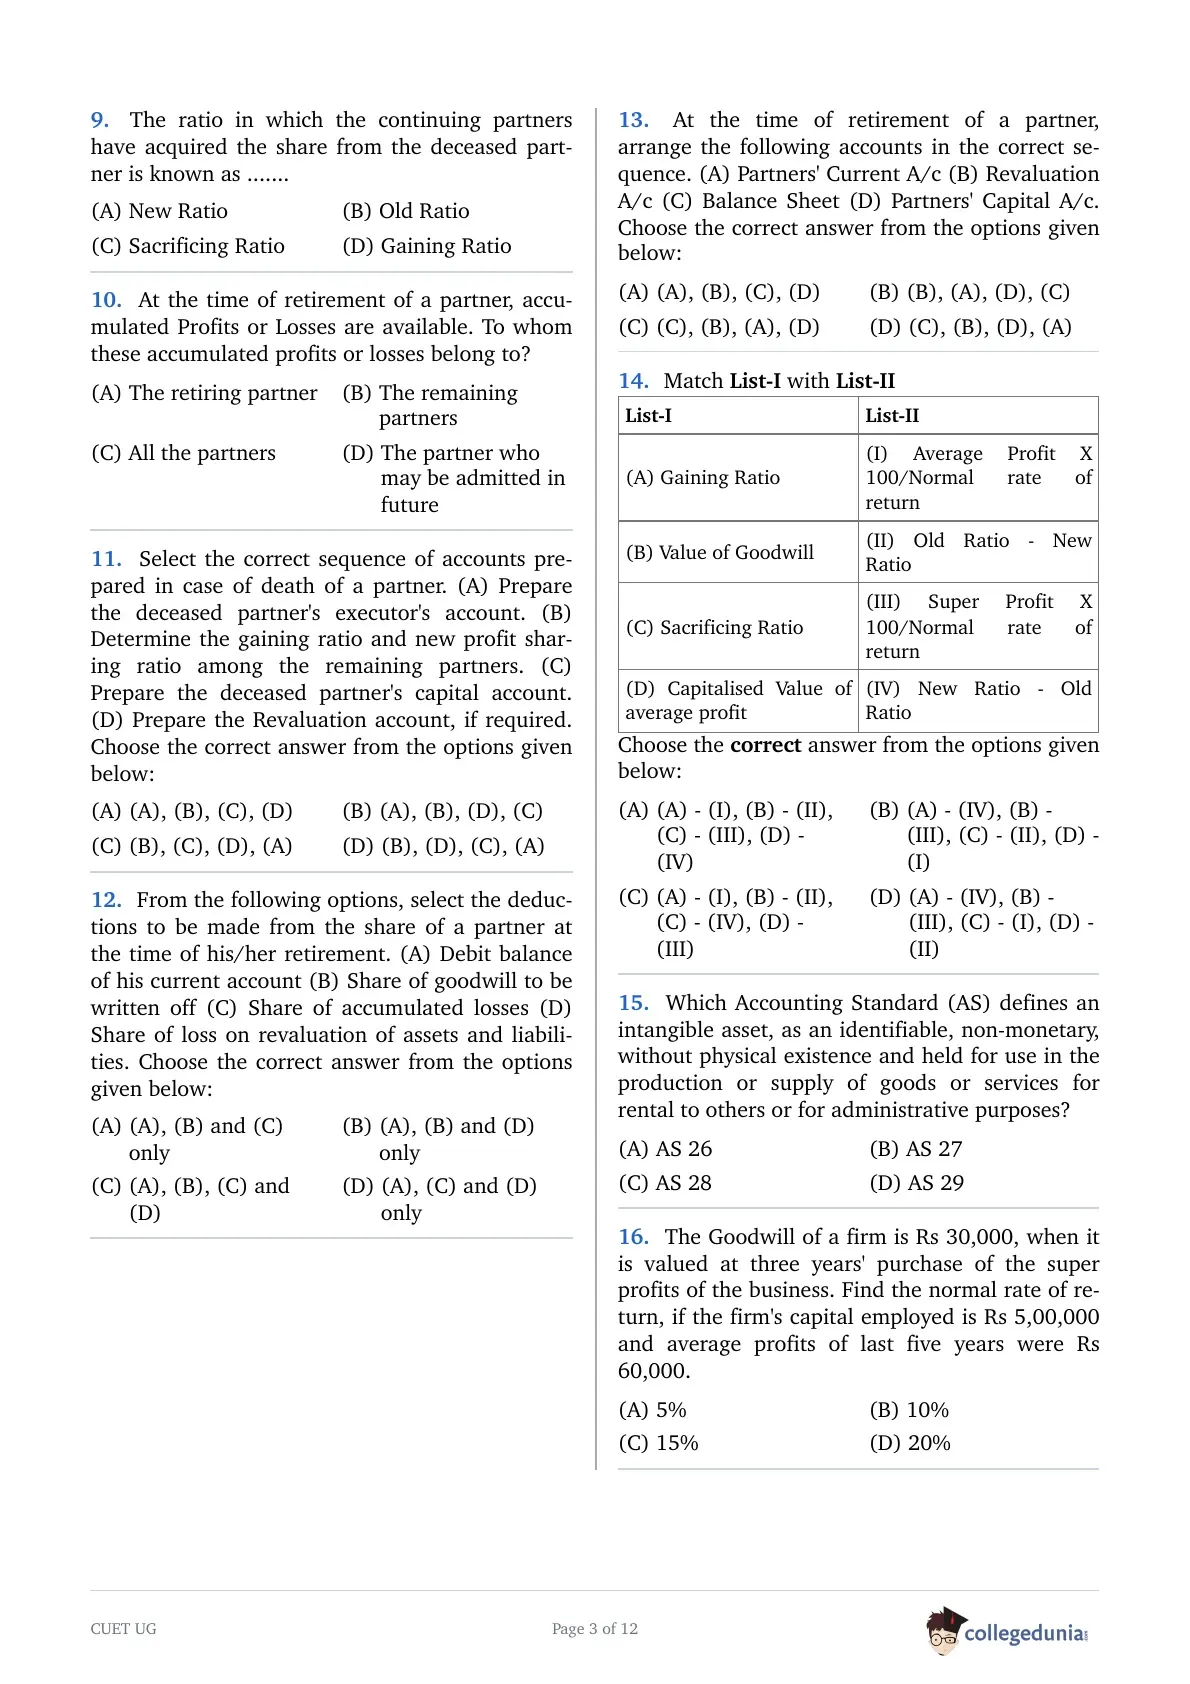
The ratio in which the continuing partners have acquired the share from the deceased partner is known as .
At the time of retirement of a partner, accumulated Profits or Losses are available. To whom these accumulated profits or losses belong to?
Select the correct sequence of accounts prepared in case of death of a partner.
(A) Prepare the deceased partner's executor's account.
(B) Determine the gaining ratio and new profit sharing ratio among the remaining partners.
(C) Prepare the deceased partner's capital account.
(D) Prepare the Revaluation account, if required.
Choose the correct answer from the options given below:
From the following options, select the deductions to be made from the share of a partner at the time of his/her retirement.
(A) Debit balance of his current account
(B) Share of goodwill to be written off
(C) Share of accumulated losses
(D) Share of loss on revaluation of assets and liabilities
Choose the correct answer from the options given below:
At the time of retirement of a partner, arrange the following accounts in the correct sequence.
(A) Partners' Current A/c
(B) Revaluation A/c
(C) Balance Sheet
(D) Partners' Capital A/c
Choose the correct answer from the options given below:
Match List-I with List-II
| List-I | List-II |
|---|---|
| (A) Gaining Ratio | (I) Average Profit X 100/Normal rate of return |
| (B) Value of Goodwill | (II) Old Ratio - New Ratio |
| (C) Sacrificing Ratio | (III) Super Profit X 100/Normal rate of return |
| (D) Capitalised Value of average profit | (IV) New Ratio - Old Ratio |
Which Accounting Standard (AS) defines an intangible asset, as an identifiable, non-monetary, without physical existence and held for use in the production or supply of goods or services for rental to others or for administrative purposes?
The Goodwill of a firm is Rs 30,000, when it is valued at three years' purchase of the super profits of the business. Find the normal rate of return, if the firm's capital employed is Rs 5,00,000 and average profits of last five years were Rs 60,000.
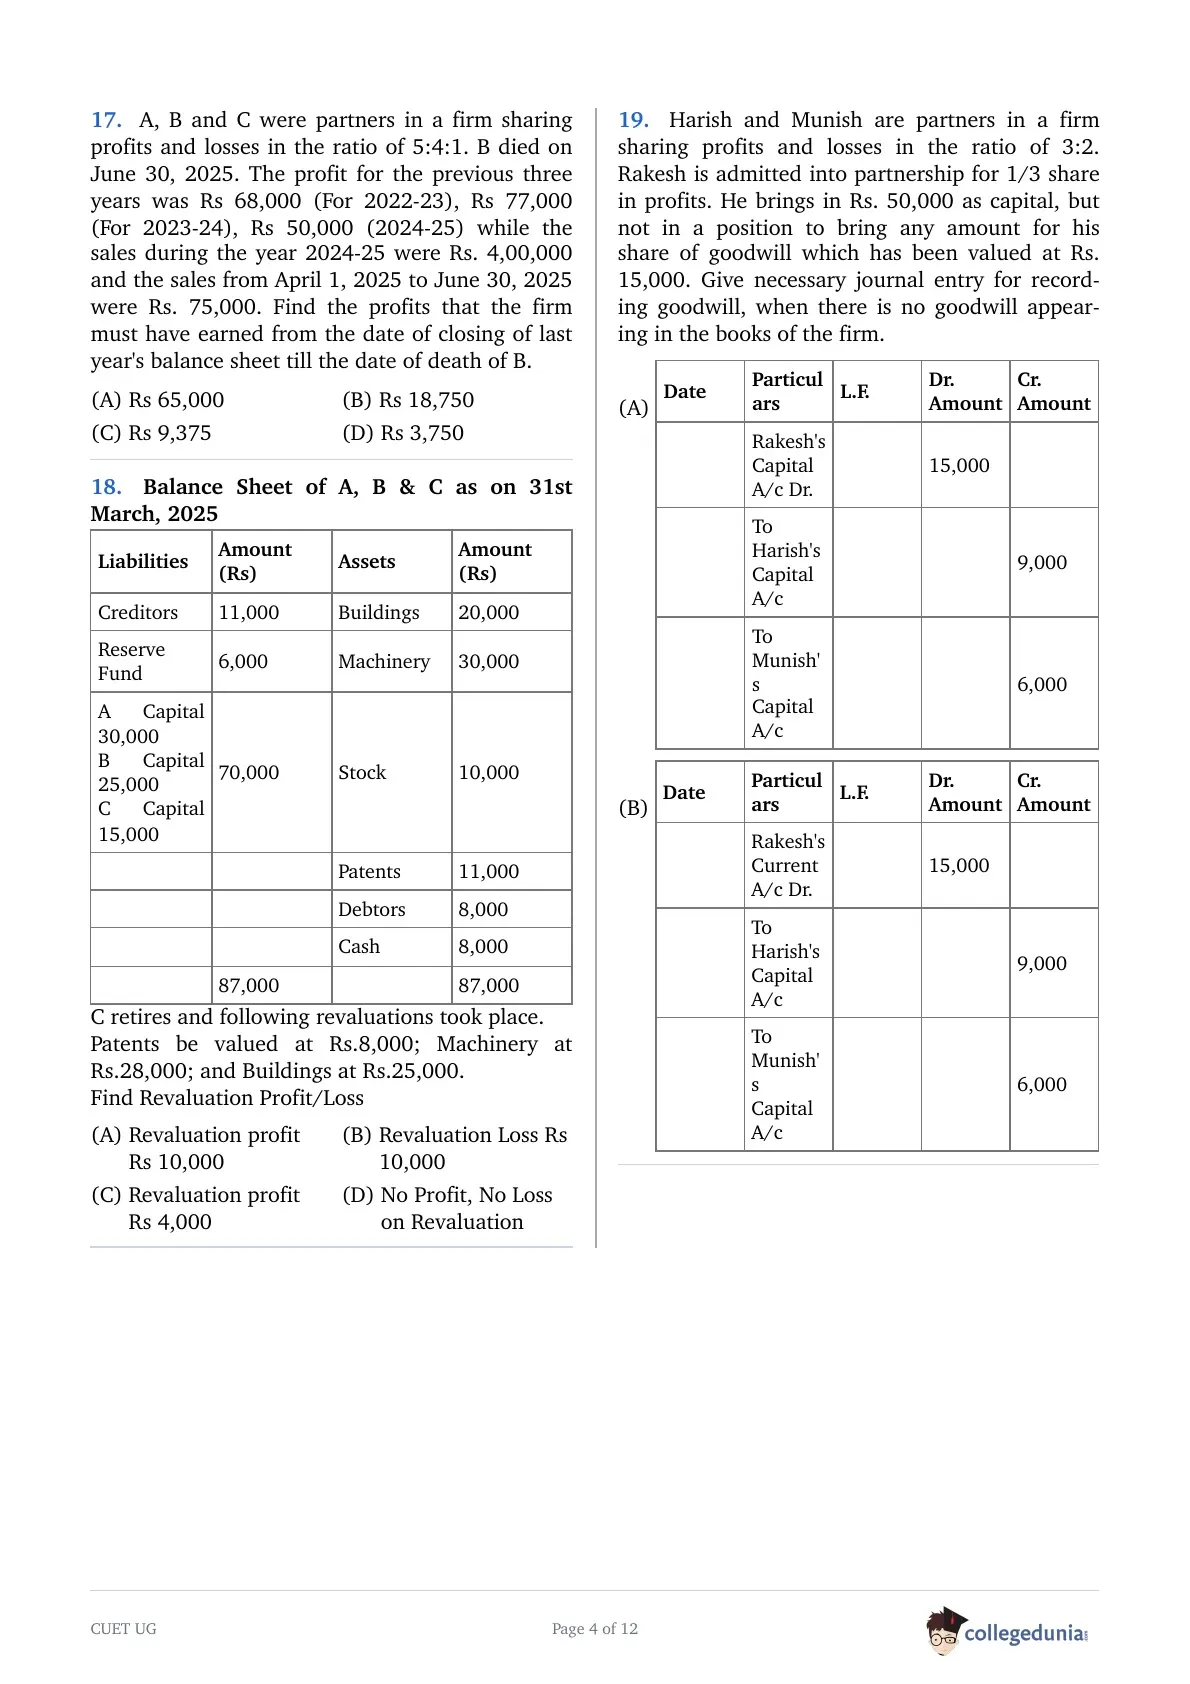
A, B and C were partners in a firm sharing profits and losses in the ratio of 5:4:1. B died on June 30, 2025. The profit for the previous three years were Rs 68,000 (For 2022-23), Rs 77,000 (For 2023-24), Rs 50,000 (2024-25) while the sales during the year 2024-25 were Rs. 4,00,000 and the sales from April 1, 2025 to June 30, 2025 were Rs. 75,000. Find the profits that the firm must have earned from the date of closing of last year's balance sheet till the date of death of B.
Balance Sheet of A, B & C as on 31st March, 2025
| Liabilities | Amount (Rs) | Assets | Amount (Rs) |
|---|---|---|---|
| Creditors | 11,000 | Buildings | 20,000 |
| Reserve Fund | 6,000 | Machinery | 30,000 |
| A Capital 30,000 B Capital 25,000 C Capital 15,000 | 70,000 | Stock | 10,000 |
| Patents | 11,000 | ||
| Debtors | 8,000 | ||
| Cash | 8,000 | ||
| 87,000 | 87,000 |
Patents be valued at Rs.8,000; Machinery at Rs.28,000; and Buildings at Rs.25,000.
Find Revaluation Profit/Loss
Harish and Munish are partners in a firm sharing profits and losses in the ratio of 3:2. Rakesh is admitted into partnership for 1/3 share in profits. He brings in Rs. 50,000 as capital, but not in a position to bring any amount for his share of goodwill which has been valued at Rs. 15,000. Give necessary journal entry for recording goodwill, when there is no goodwill appearing in the books of the firm.
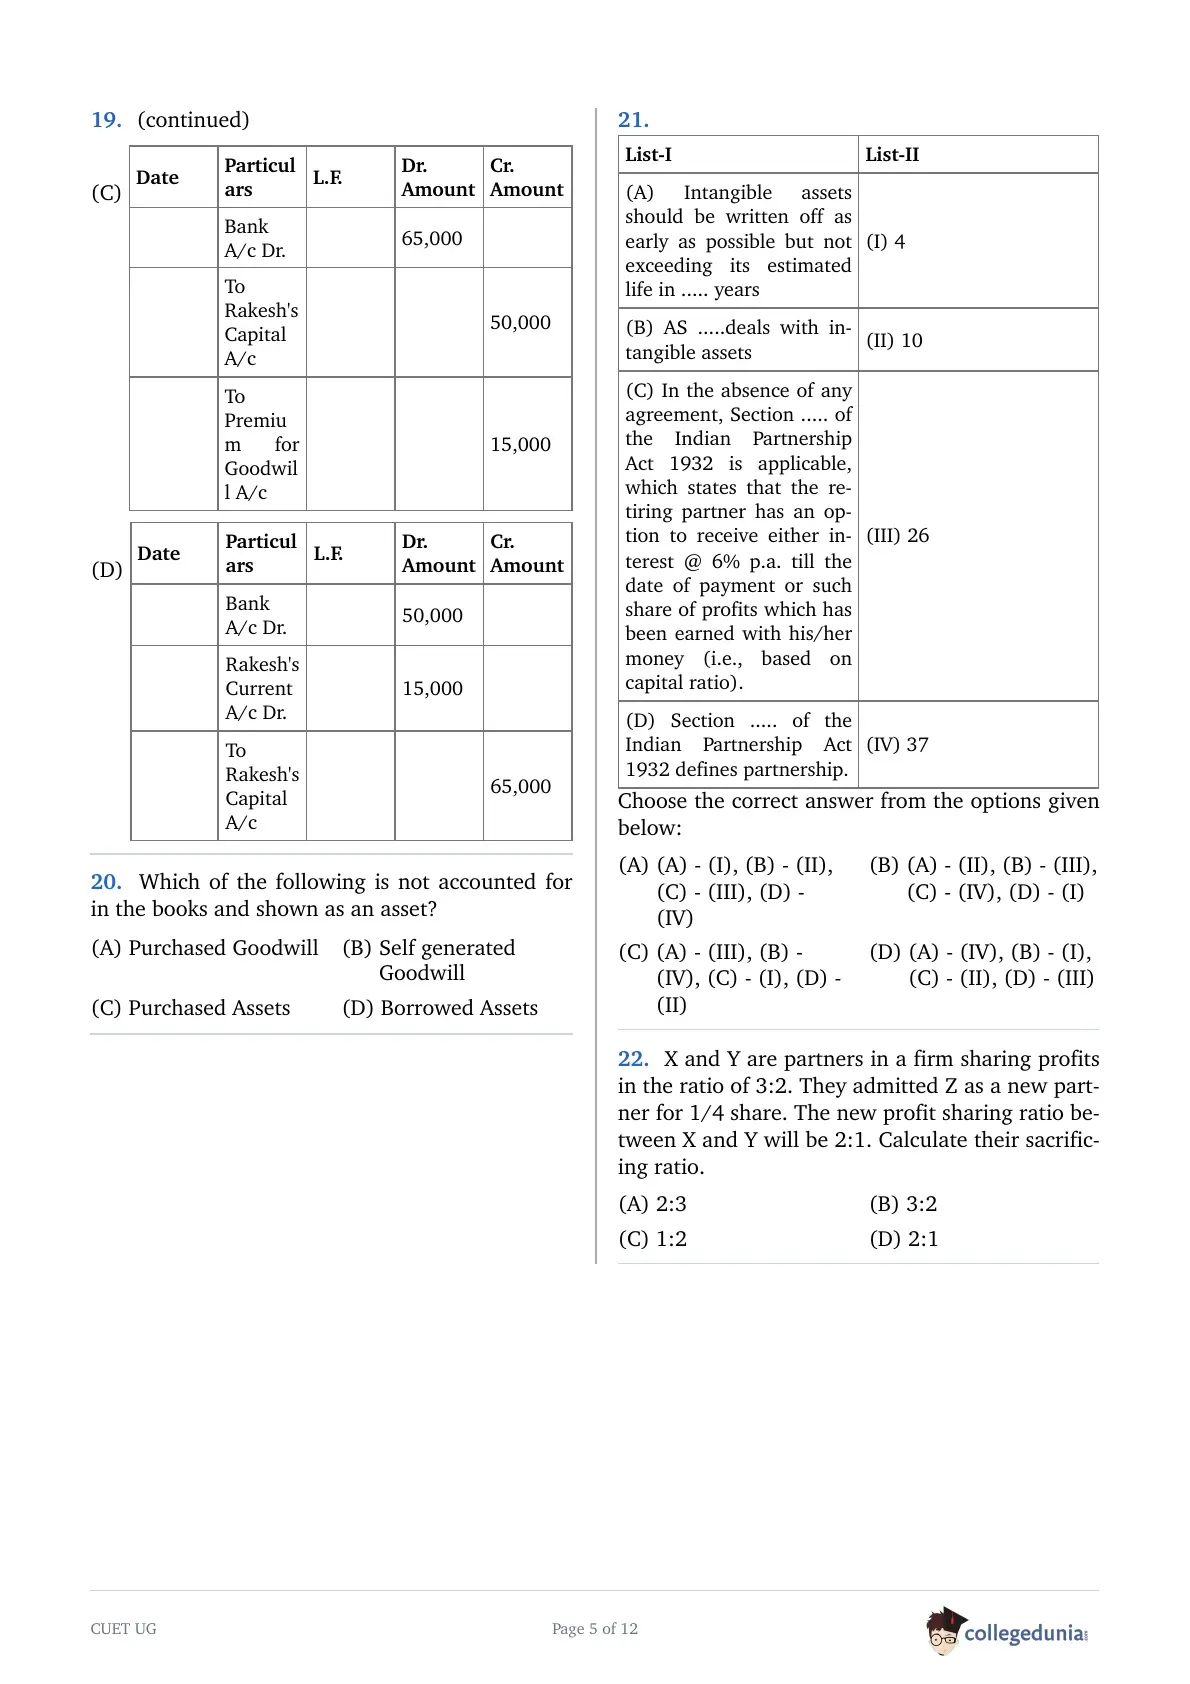
Which of the following is not accounted for in the books and shown as an asset?
Match List-I with List-II
| List-I | List-II |
|---|---|
| (A) Intangible assets should be written off as early as possible but not exceeding its estimated life in ......... years | (I) 4 |
| (B) AS ..... deals with intangible assets | (II) 10 |
| (C) In the absence of any agreement, Section ...... of the Indian Partnership Act, 1932 is applicable, which states that the retiring partner has an option to receive either interest @ 6% p.a. till the date of payment or such share of profits which has been earned with his/her money (i.e., based on capital ratio). | (III) 26 |
| (D) Section ...... of the Indian Partnership Act 1932 defines partnership. | (IV) 37 |
Choose the correct answer from the options given below:
X and Y are partners in a firm sharing profits in the ratio of 3:2. They admitted Z as a new partner for 1/4 share. The new profit sharing ratio between X and Y will be 2:1. Calculate their sacrificing ratio.
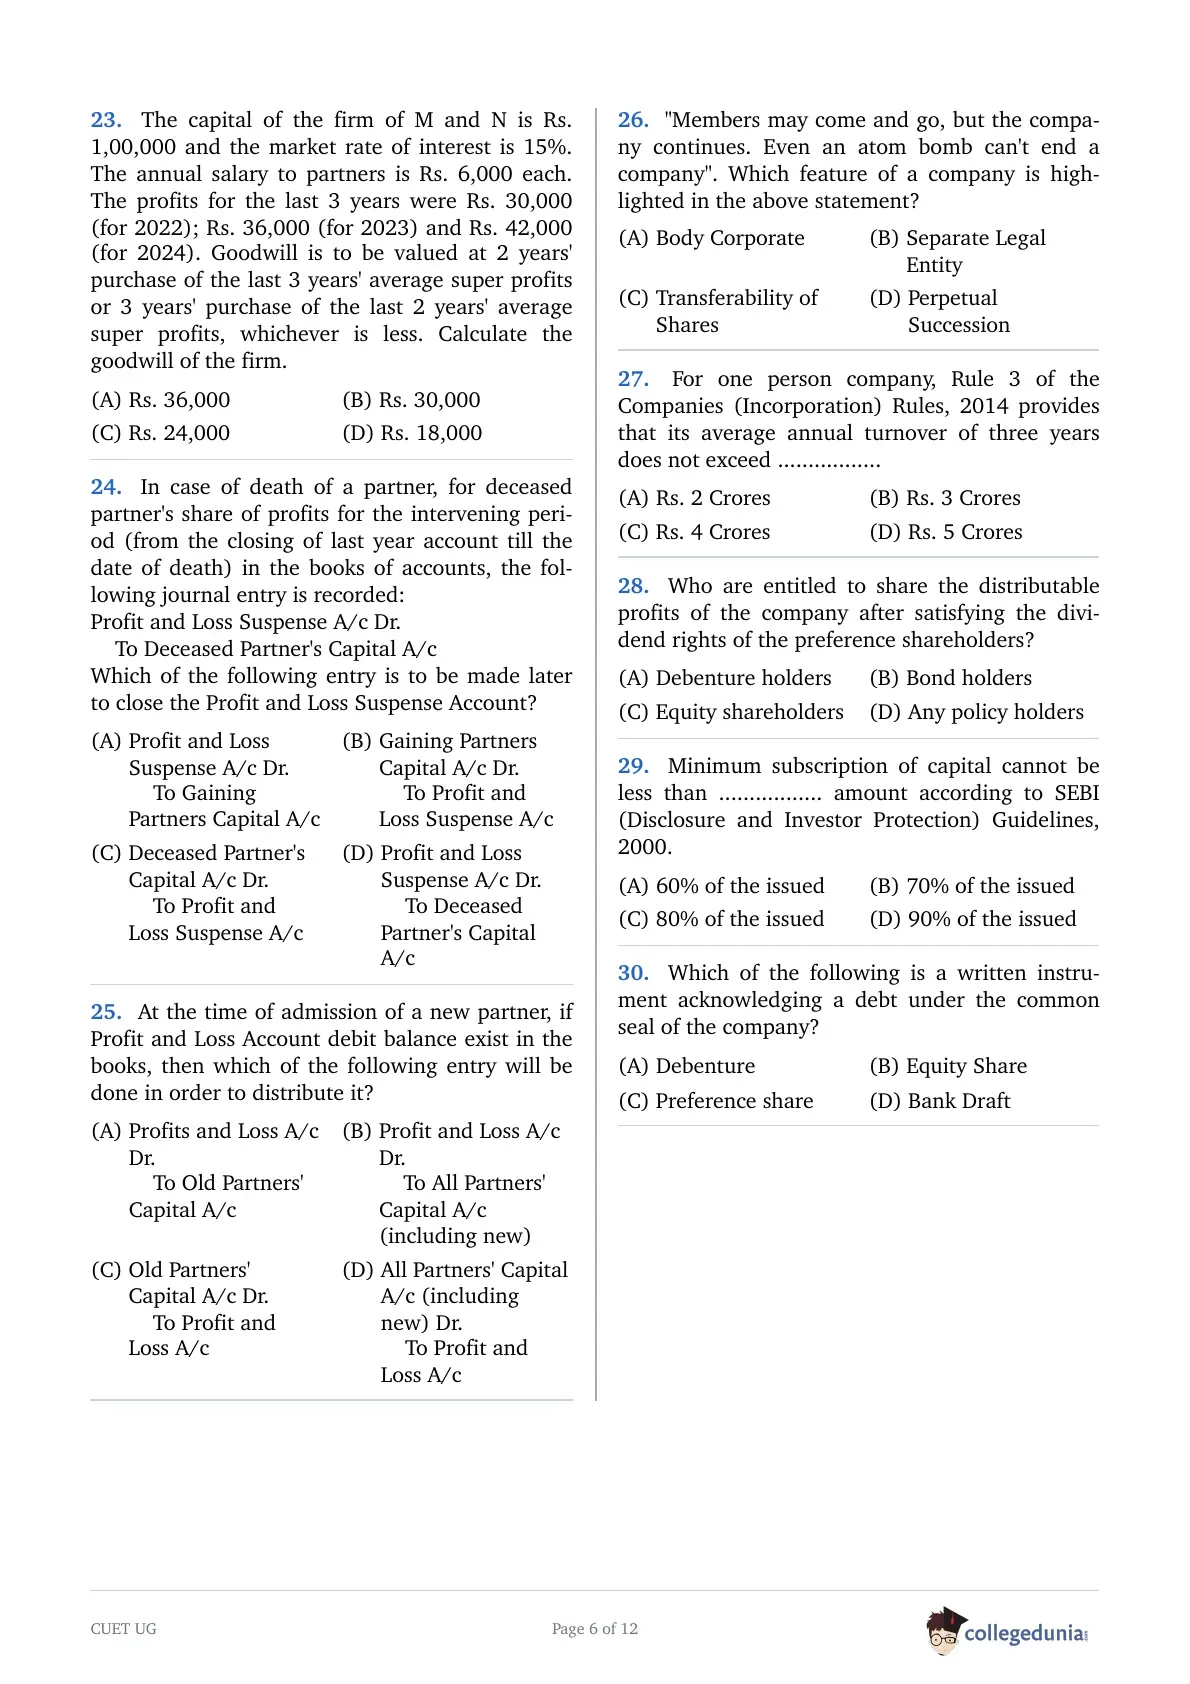
The capital of the firm of M and N is Rs. 1,00,000 and the market rate of interest is 15%. The annual salary to partners is Rs. 6,000 each. The profits for the last 3 years were Rs. 30,000 (for 2022); Rs. 36,000 (for 2023) and Rs. 42,000 (for 2024). Goodwill is to be valued at 2 years' purchase of the last 3 years' average super profits or 3 years' purchase of the last 2 years' average super profits, whichever is less. Calculate the goodwill of the firm.
In case of death of a partner, for deceased partner's share of profits for the intervening period (from the closing of last year account till the date of death) in the books of accounts, the following journal entry is recorded:
Profit and Loss Suspense A/c Dr.
To Deceased Partner's Capital A/c
Which of the following entry is to be made later to close the Profit and Loss Suspense Account?
At the time of admission of a new partner, if Profit and Loss Account debit balance exist in the books, then which of the following entry will be done in order to distribute it?
"Members may come and go, but the company continues. Even an atom bomb can't end a company".
Which feature of a company is highlighted in the above statement?
For one person company, Rule 3 of the Companies (Incorporation) Rules, 2014 provides that its average annual turnover of three years does not exceed ...................
Who are entitled to share the distributable profits of the company after satisfying the dividend rights of the preference shareholders?
Minimum subscription of capital cannot be less than ................... amount according to SEBI (Disclosure and Investor Protection) Guidelines, 2000.
Which of the following is a written instrument acknowledging a debt under the common seal of the company?
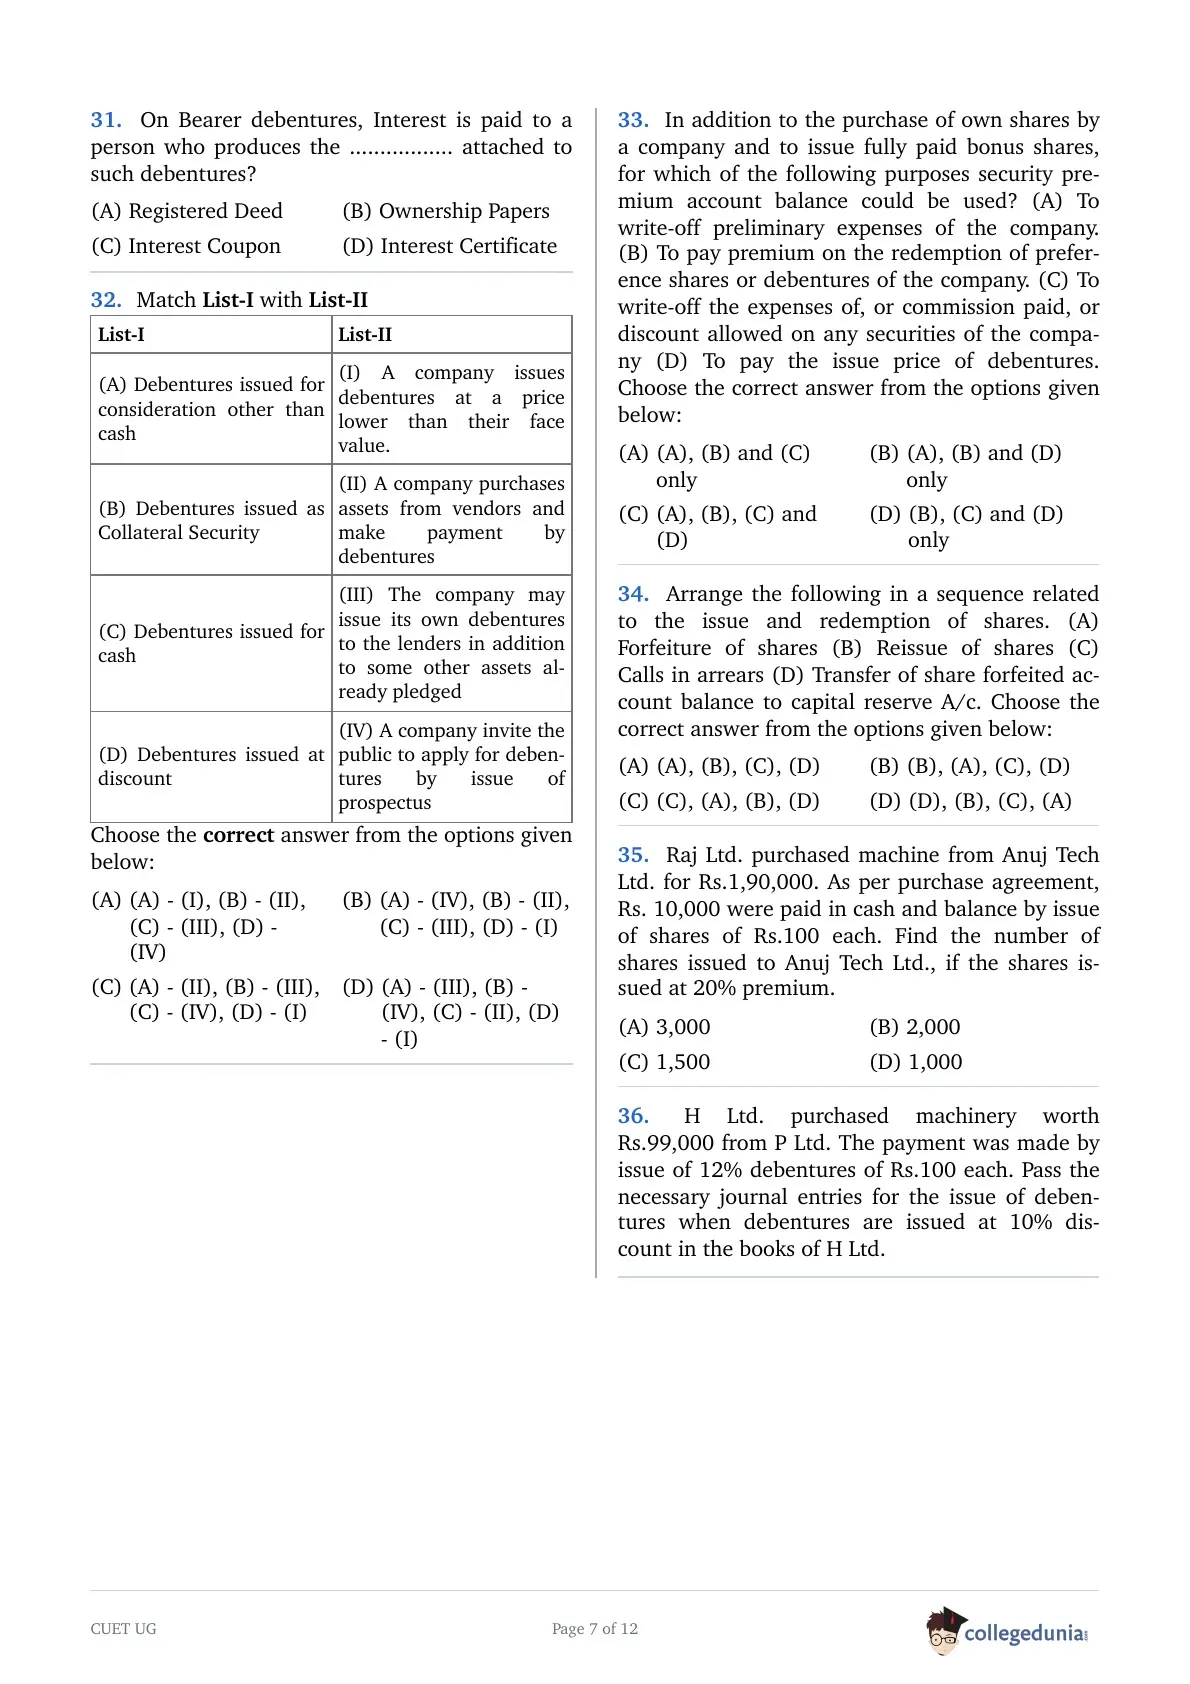
On Bearer debentures, Interest is paid to a person who produces the ................... attached to such debentures?
Match List-I with List-II
| List-I | List-II |
|---|---|
| (A) Debentures issued for consideration other than cash | (I) A company issues debentures at a price lower than their face value. |
| (B) Debentures issued as Collateral Security | (II) A company purchases assets from vendors and make payment by debentures |
| (C) Debentures issued for cash | (III) The company may issue its own debentures to the lenders in addition to some other assets already pledged |
| (D) Debentures issued at discount | (IV) A company invite the public to apply for debentures by issue of prospectus |
In addition to the purchase of own shares by a company and to issue fully paid bonus shares, for which of the following purposes security premium account balance could be used?
(A) To write-off preliminary expenses of the company.
(B) To pay premium on the redemption of preference shares or debentures of the company.
(C) To write-off the expenses of, or commission paid, or discount allowed on any securities of the company
(D) To pay the issue price of debentures.
Choose the correct answer from the options given below:
Arrange the following in a sequence related to the issue and redemption of shares
(A) Forfeiture of shares
(B) Reissue of shares
(C) Calls in arrears
(D) Transfer of share forfeited account balance to capital reserve A/c
Choose the correct answer from the options given below:
Raj Ltd. purchased a machine from Anuj Tech Ltd. for Rs.1,90,000. As per purchase agreement, Rs. 10,000 were paid in cash and balance by issue of shares of Rs.100 each. Find the number of shares issued to Anuj Tech Ltd., if the shares issued at 20% premium.
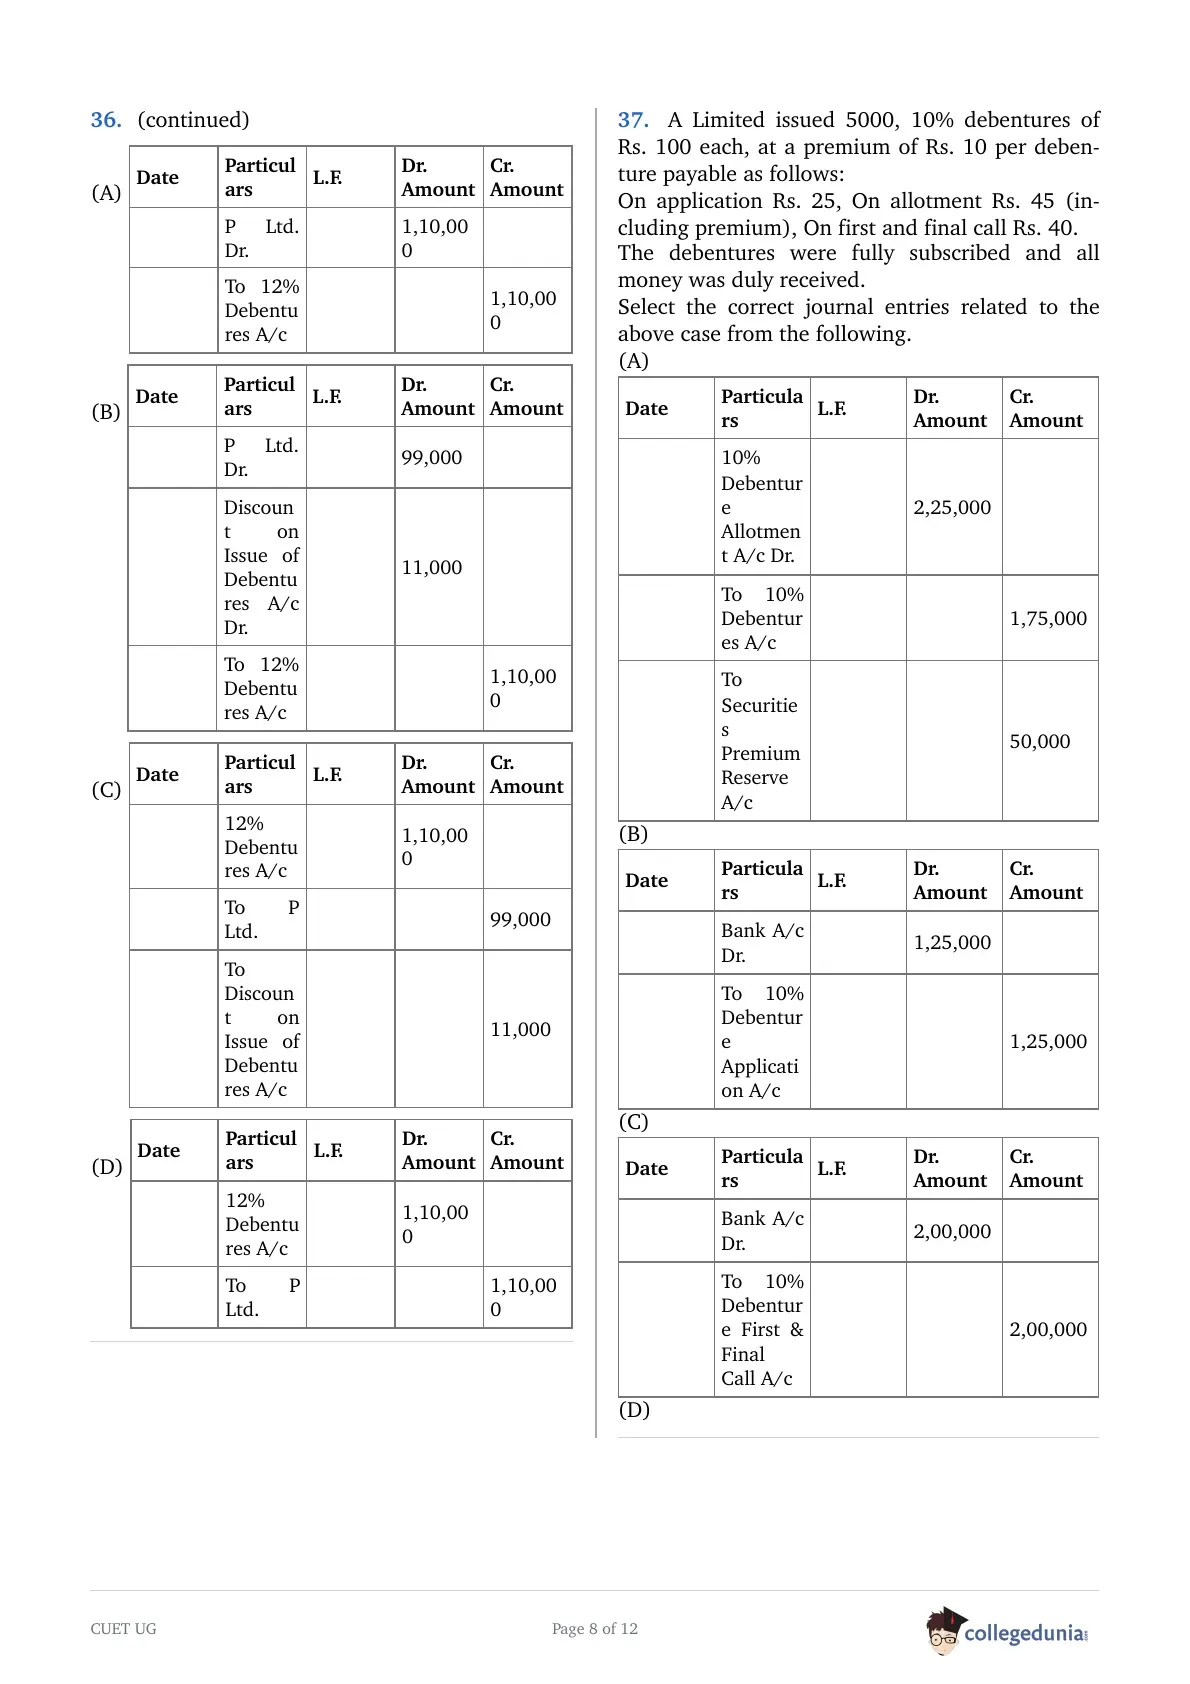
H Ltd. purchased machinery worth Rs.99,000 from P Ltd. The payment was made by issue of 12% debentures of Rs.100 each. Pass the necessary journal entries for the issue of debentures when debentures are issued at 10% discount in the books of H Ltd.
A Limited issued 5000, 10% debentures of Rs. 100 each, at a premium of Rs. 10 per debenture payable as follows:
On application Rs. 25, On allotment Rs. 45 (including premium), On first and final call Rs. 40.
The debentures were fully subscribed and all money was duly received.
Select the correct journal entries related to the above case from the following.
(A)
| Date | Particulars | L.F. | Dr. Amount | Cr. Amount |
|---|---|---|---|---|
| 10% Debenture Allotment A/c Dr. | 2,25,000 | |||
| To 10% Debentures A/c | 1,75,000 | |||
| To Securities Premium Reserve A/c | 50,000 |
| Date | Particulars | L.F. | Dr. Amount | Cr. Amount |
|---|---|---|---|---|
| Bank A/c Dr. | 1,25,000 | |||
| To 10% Debenture Application A/c | 1,25,000 |
| Date | Particulars | L.F. | Dr. Amount | Cr. Amount |
|---|---|---|---|---|
| Bank A/c Dr. | 2,00,000 | |||
| To 10% Debenture First & Final Call A/c | 2,00,000 |
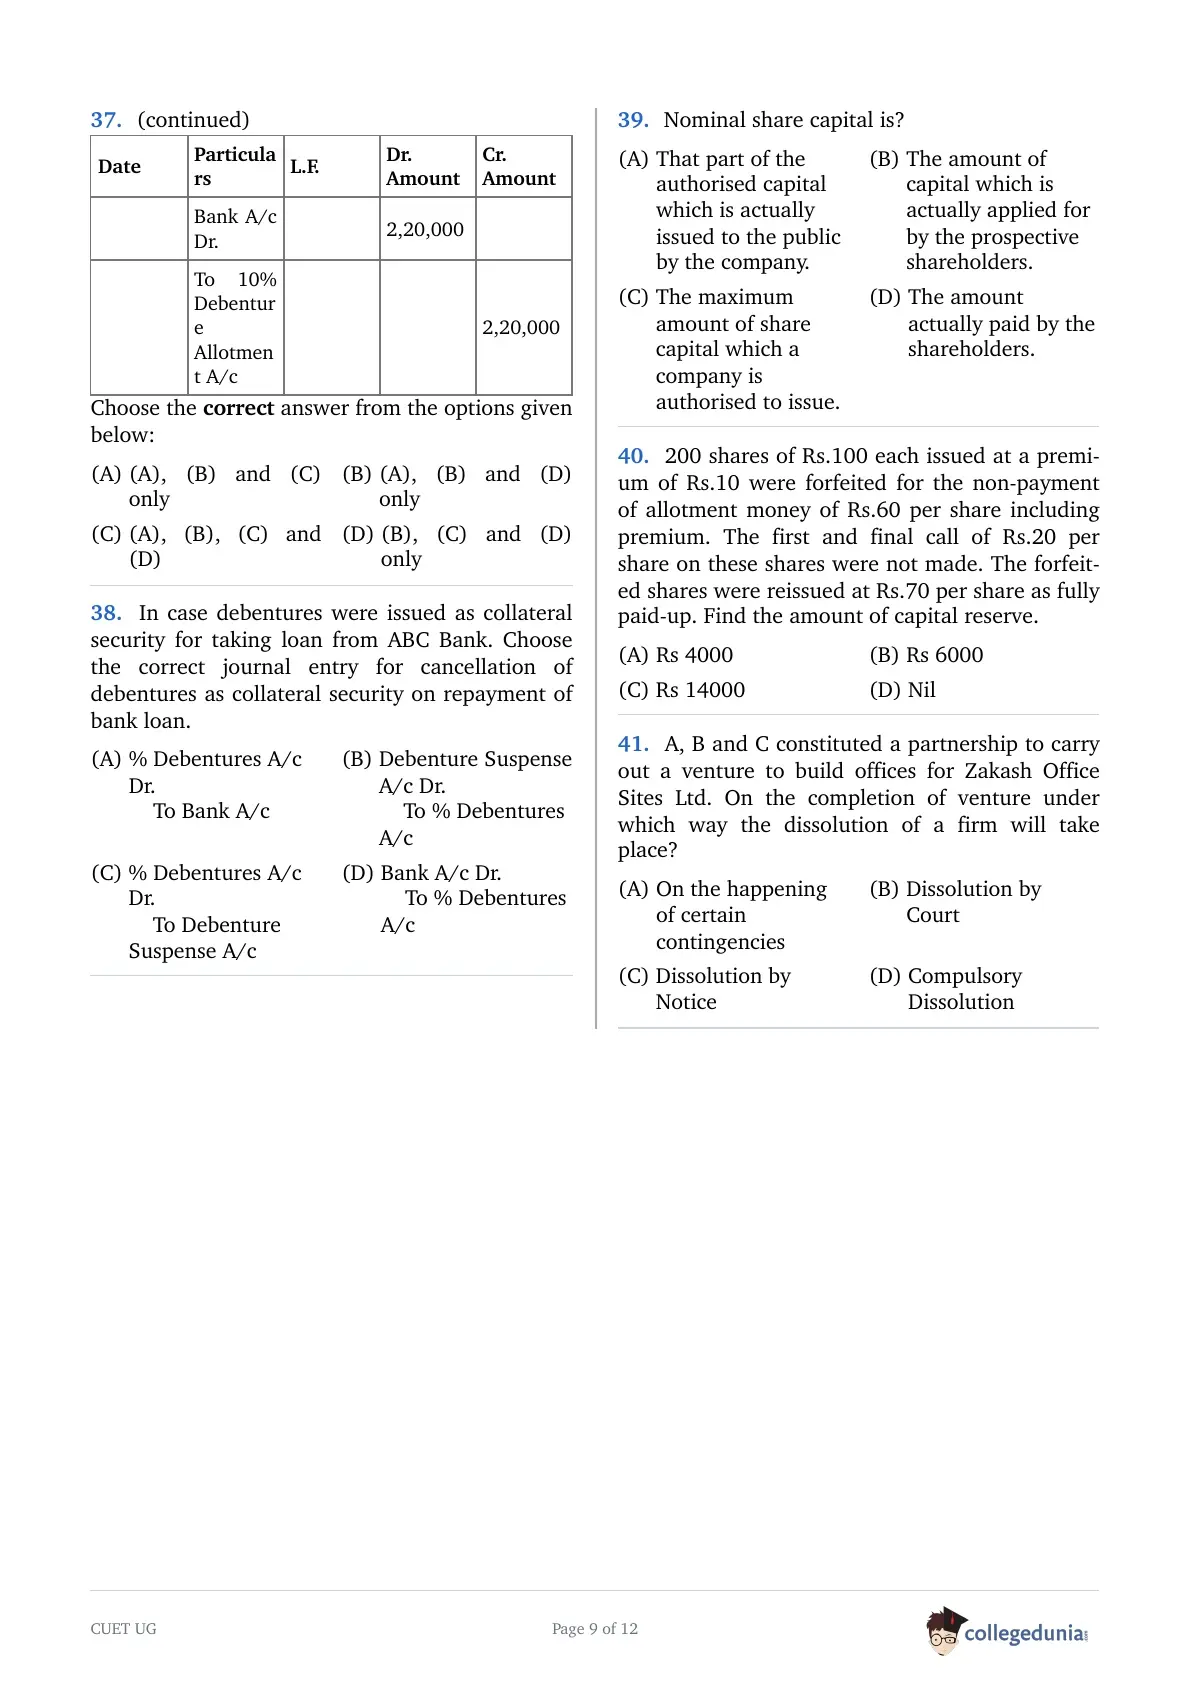
| Date | Particulars | L.F. | Dr. Amount | Cr. Amount |
|---|---|---|---|---|
| Bank A/c Dr. | 2,20,000 | |||
| To 10% Debenture Allotment A/c | 2,20,000 |
In case debentures were issued as collateral security for taking loan from ABC Bank. Choose the correct journal entry for cancellation of debentures as collateral security on repayment of bank loan.
Nominal share capital is ?
200 shares of Rs.100 each issued at a premium of Rs.10 were forfeited for the non-payment of allotment money of Rs.60 per share including premium. The first and final call of Rs.20 per share on these shares were not made. The forfeited shares were reissued at Rs.70 per share as fully paid-up. Find the amount of capital reserve.
A, B and C constituted a partnership to carry out a venture to build offices for Zakash Office Sites Ltd. On the completion of venture under which way the dissolution of a firm will takes place?
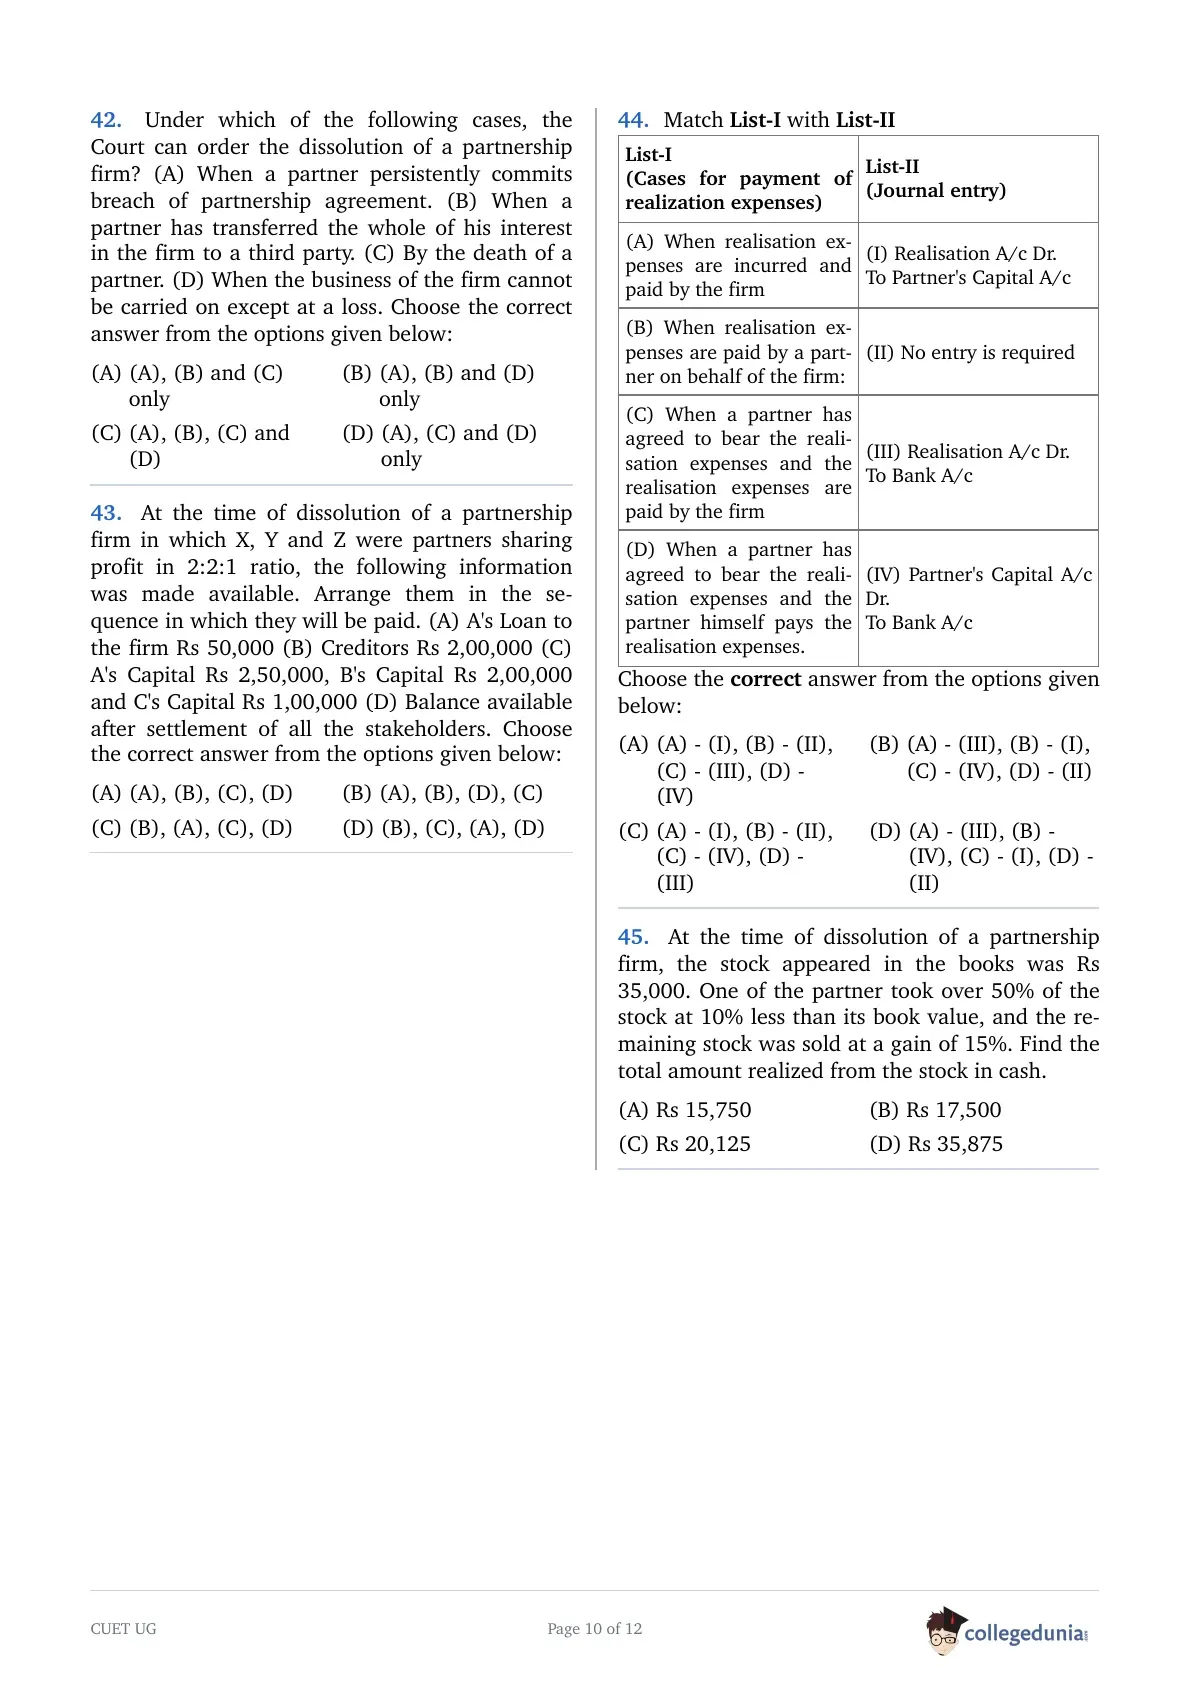
Under which of the following cases, the Court can order the dissolution of a partnership firm?
(A) When a partner persistently commits breach of partnership agreement.
(B) When a partner has transferred the whole of his interest in the firm to a third party.
(C) By the death of a partner.
(D) When the business of the firm cannot be carried on except at a loss.
Choose the correct answer from the options given below:
At the time of the dissolution of a partnership firm in which X, Y and Z were partners sharing profit in 2:2:1 ratio, the following information was made available. Arrange them in the sequence in which they will be paid.
(A) A's Loan to the firm Rs 50,000
(B) Creditors Rs 2,00,000
(C) A's Capital Rs 2,50,000 , B's Capital Rs 2,00,000 and C's Capital Rs 1,00,000
(D) Balance available after settlement of all the stakeholders.
Choose the correct answer from the options given below:
Match List-I with List-II
| List-I (Cases for payment of realization expenses) | List-II (Journal entry) |
|---|---|
| (A) When realisation expenses are incurred and paid by the firm | (I) Realisation A/c Dr. To Partner's Capital A/c |
| (B) When realisation expenses are paid by a partner on behalf of the firm: | (II) No entry is required |
| (C) When a partner has agreed to bear the realisation expenses and the realisation expenses are paid by the firm | (III) Realisation A/c Dr. To Bank A/c |
| (D) When a partner has agreed to bear the realisation expenses and the partner himself pays the realisation expenses. | (IV) Partner's Capital A/c Dr. To Bank A/c |
At the time of dissolution of a partnership firm, the stock appeared in the books was Rs 35,000. One of the partner took over 50% of the stock at 10% less than its book value, and the remaining stock was sold at a gain of 15%. Find the total amount realized from the stock in cash.
Section B1 - Analysis of Financial Statements (Q46 - Q50)
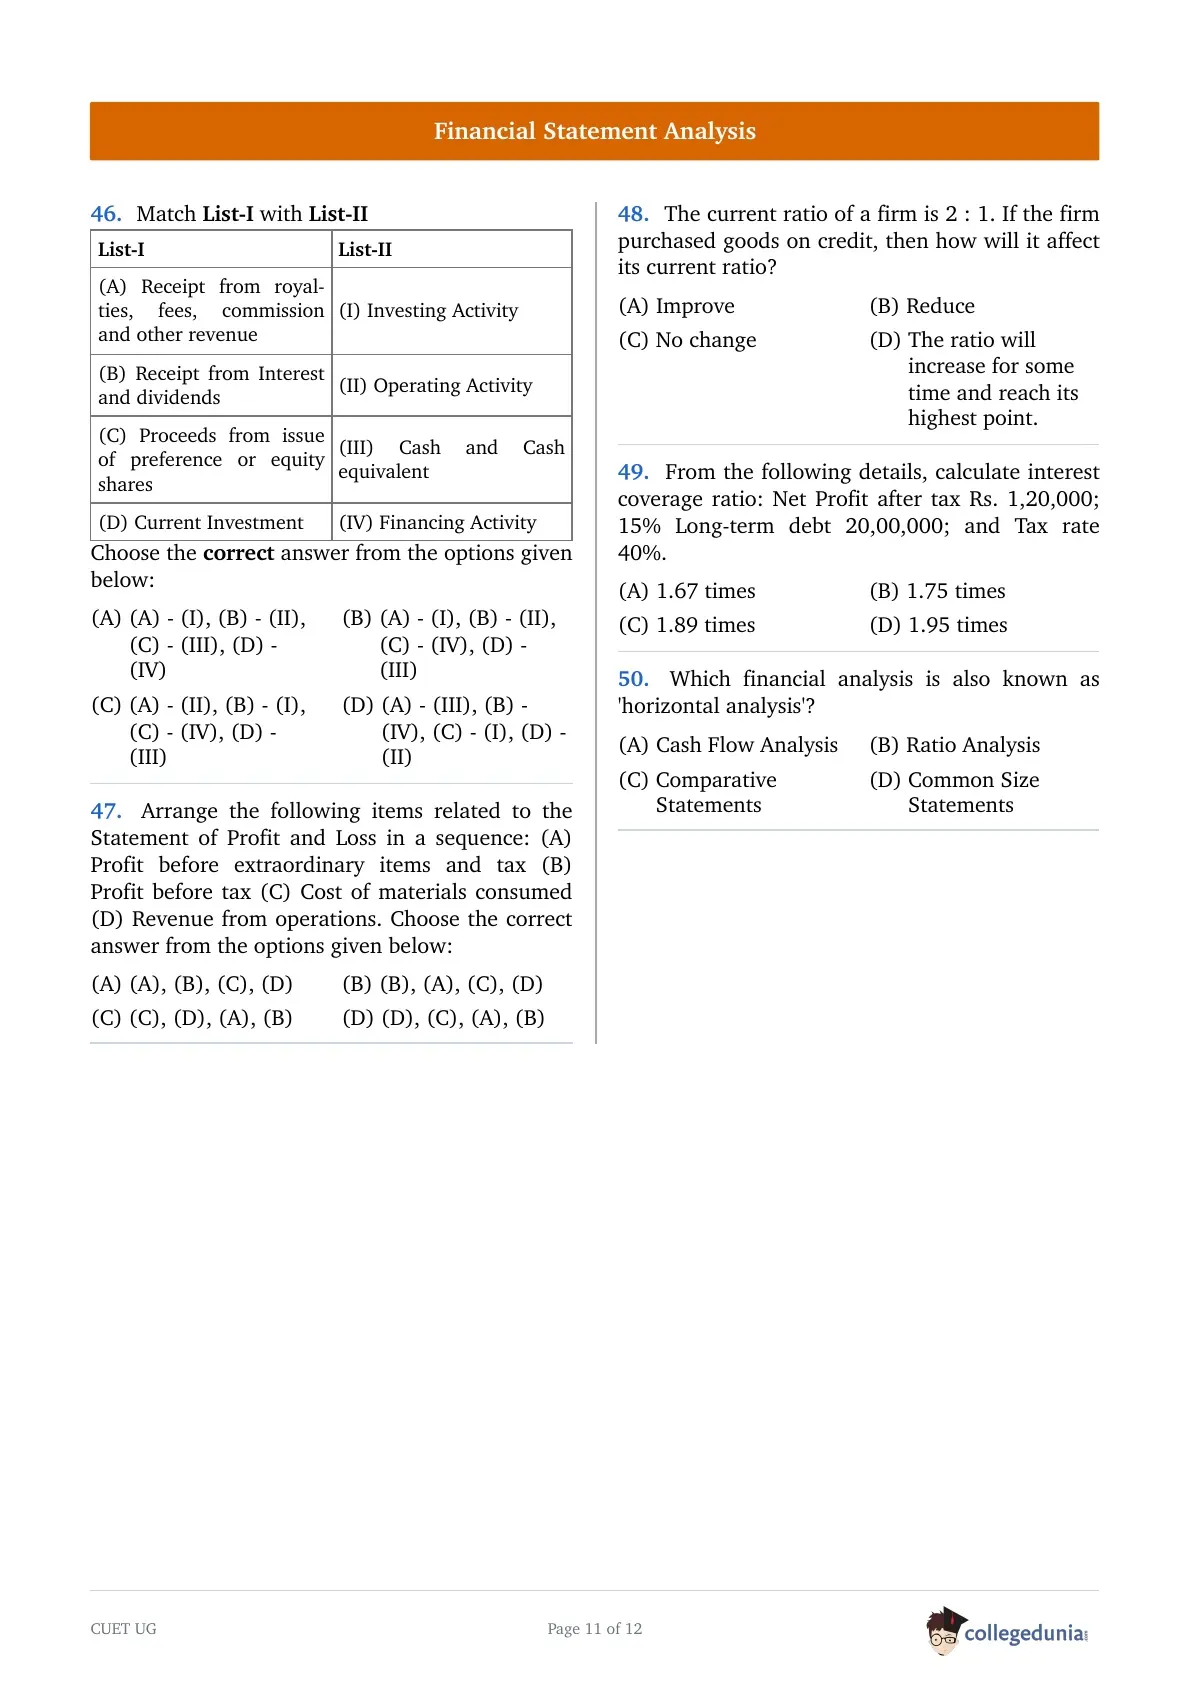
Match List-I with List-II
| List-I | List-II |
|---|---|
| (A) Receipt from royalties, fees, commission and other revenue | (I) Investing Activity |
| (B) Receipt from Interest and dividends | (II) Operating Activity |
| (C) Proceeds from issue of preference or equity shares | (III) Cash and Cash equivalent |
| (D) Current Investment | (IV) Financing Activity |
Arrange the following items related to the Statement of Profit and Loss in a sequence:
(A) Profit before extraordinary items and tax
(B) Profit before tax
(C) Cost of materials consumed
(D) Revenue from operations
Choose the correct answer from the options given below:
The current ratio of a firm is 2 : 1. If the firm purchased goods on credit, then how will it affect its current ratio?
From the following details, calculate interest coverage ratio: Net Profit after tax Rs. 1,20,000; 15% Long-term debt 20,00,000; and Tax rate 40%.
Which financial analysis is also known as 'horizontal analysis'?
Section B2 - Computerized Accounting Systems (Q51 - Q55)
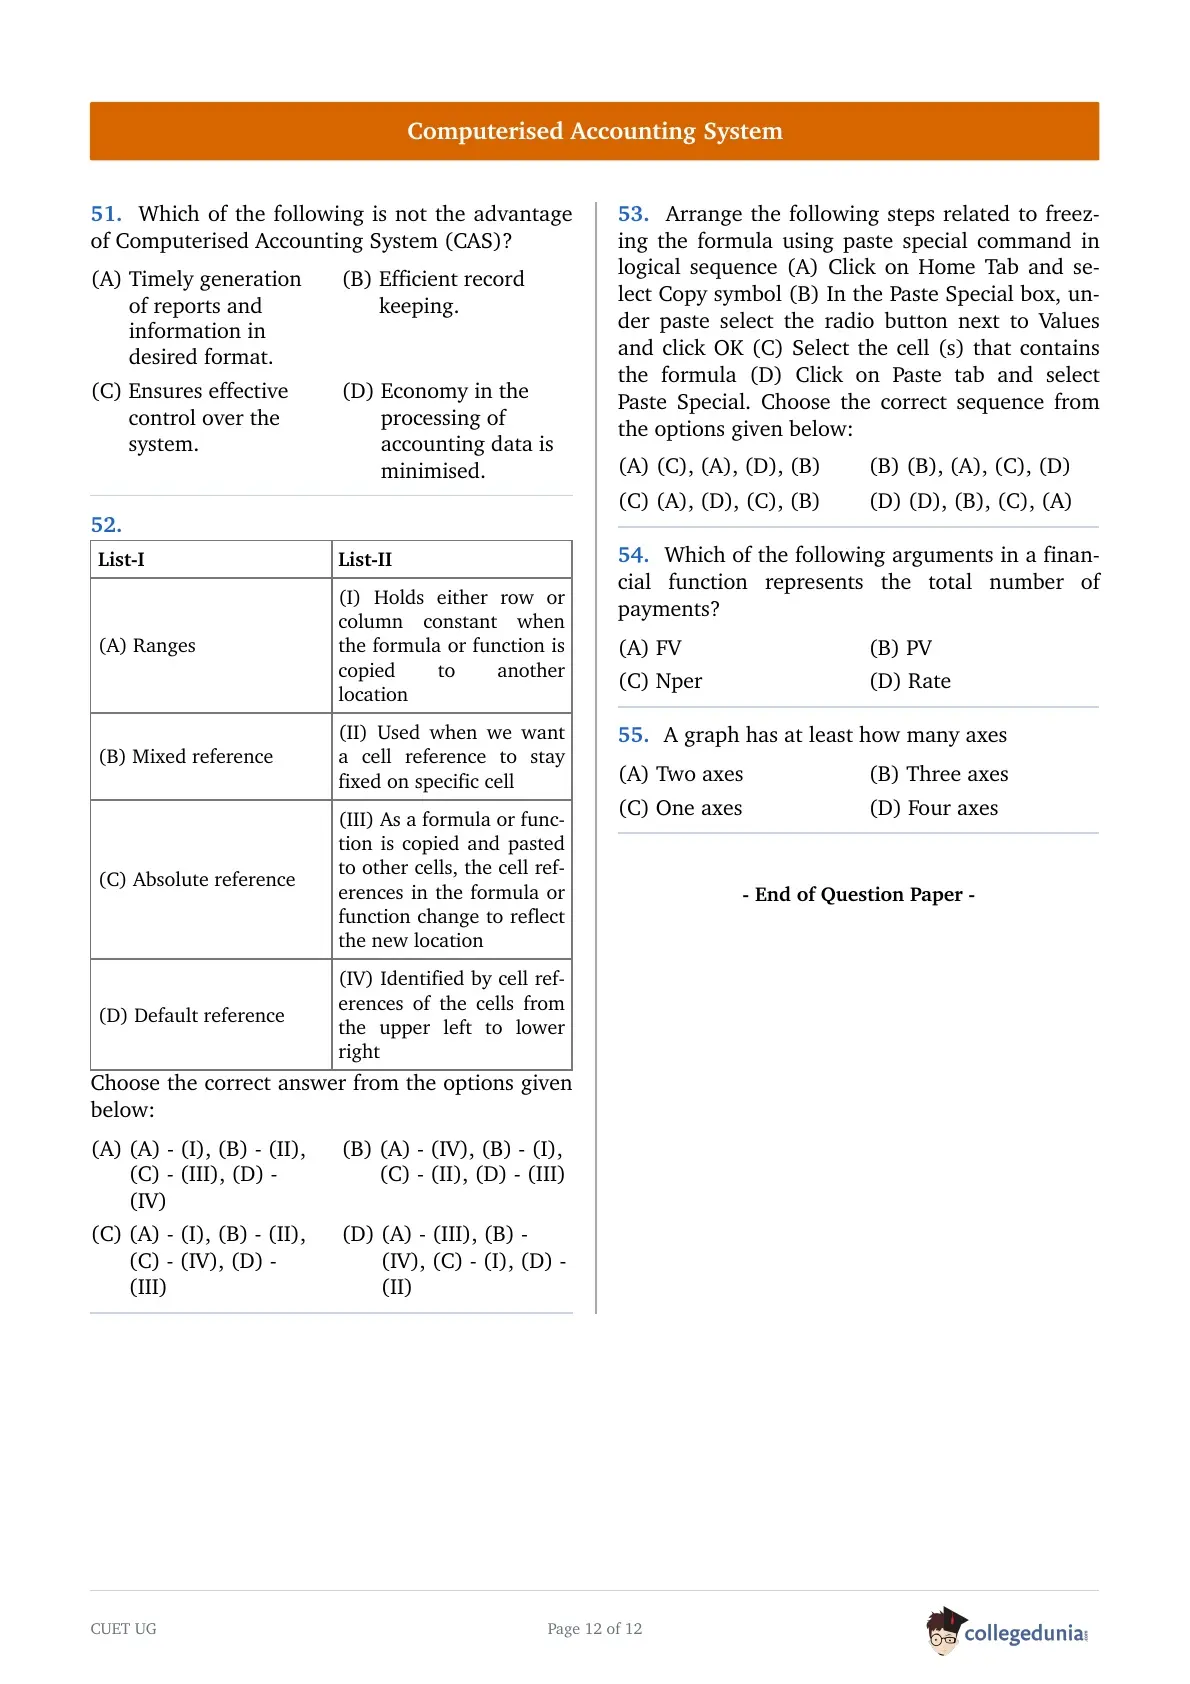
Which of the following is not the advantage of Computerised Accounting System (CAS)?
Match List-I with List-II
| List-I | List-II |
|---|---|
| (A) Ranges | (I) Holds either row or column constant when the formula or function is copied to another location |
| (B) Mixed reference | (II) Used when we want a cell reference to stay fixed on specific cell |
| (C) Absolute reference | (III) As a formula or function is copied and pasted to other cells, the cell references in the formula or function change to reflect the new location |
| (D) Default reference | (IV) Identified by cell references of the cells from the upper left to lower right |
Arrange the following steps related to freezing the formula using paste special command in logical sequence
(A) Click on Home Tab and select Copy symbol
(B) In the Paste Special box, under paste select the radio button next to Values and click OK
(C) Select the cell (s) that contains the formula
(D) Click on Paste tab and select Paste Special
Choose the correct sequence from the options given below:
Which of the following arguments in a financial function represents the total number of payments?
A graph has at least how many axes
CUET UG 2026 Exam Pattern and Marking Scheme
| Parameter | Details |
|---|---|
| Exam Name | Common University Entrance Test (CUET UG) 2026 |
| Conducting Body | National Testing Agency (NTA) |
| Exam Mode | Computer-Based Test (CBT) |
| Exam Duration | 60 minutes per test |
| Total Sections | 3 (Languages, Domain Subjects, General Test) |
| Question Type | Multiple Choice Questions (MCQs) |
| Questions per Test | 50 questions (all compulsory) |
| Marking Scheme | +5 for correct, -1 for incorrect |
| Maximum Marks | 250 marks per test |
| Maximum Subject Choices | 5 subjects in total |
| Syllabus Base | Class 12 NCERT (mainly for Domain Subjects) |


Comments